

Overview
According to PIB reports, India's female labor force participation rate increased from 23.3% in 2017–18 to 40.0% in 2025. The female worker population ratio also reached 38.8% in 2025.
As more women contribute to household income and support financial dependents, life insurance becomes an important part of financial planning. Term insurance can help protect their families against income loss and outstanding liabilities.
This guide covers the benefits, eligibility criteria, and key features of term insurance plans for women to help you choose coverage that fits your needs.
Best Term Plans for Women
1) Axis Max Life Smart Term Plan Plus
Smart Term Plan Plus offers women-specific premium discounts, health management services, and a top-up feature after the spouse’s death. It also provides an optional critical illness rider covering up to 64 illnesses for 30 years and an accelerated terminal illness benefit of up to ₹1 crore.
2) HDFC Life Click 2 Protect Supreme Plus
Click 2 Protect Supreme Plus offers female premium discounts, multiple coverage options, and flexible death benefit payouts. Nominees can receive structured income instead of a single lump sum. Its optional critical illness rider covers up to 60 illnesses for up to 15 years.
3) ICICI Life iProtect Smart Plus
ICICI Life iProtect Smart Plus offers flexible features for women who may experience income disruptions. Eligible policyholders can use the Premium Break option to pause payments for up to 12 months, subject to policy conditions. Higher-cover policies may also qualify for an instant partial payout of ₹3 lakh at claim intimation.
4) Bajaj Life eTouch II
Bajaj Life eTouch II offers flexible death benefit payouts, limited premium payment options, and additional protection through optional riders. It includes an accelerated terminal illness benefit of up to ₹2 crore and a built-in waiver of premium option in case of accidental disability or terminal illness, subject to conditions.
5) Aditya Birla Sun Life Super Term Plan
Super Term Plan offers female premium discounts and an optional critical illness benefit for 42 listed diseases. It includes an accelerated terminal illness benefit of up to ₹1 crore. The plan also offers a Cover Continuance Benefit that allows eligible policyholders to temporarily defer their premiums for a year.
Each plan is evaluated using Ditto’s detailed policy rating framework, which compares key features, insurer performance, and long-term value.
Note: Term life insurance for women is a pure life insurance policy that pays a death benefit to the nominee if the insured woman passes away during the policy term. However, eligibility for plans can vary from woman to woman.
Talk to an expert
today and
find
the right
insurance for you.
Women from different employment and family backgrounds can apply for term insurance, subject to the insurer's eligibility and underwriting criteria:
- Salaried Women: Working women are eligible for flagship plans from the best term insurance companies, subject to underwriting.
- Self-Employed Women: You can explore plans such as HDFC Life Click 2 Protect Supreme Plus, subject to the insurer's eligibility and underwriting criteria. Choose a cover that accounts for fluctuating income, business liabilities, and your family's financial needs.
- Housewives: Term insurance for housewives can help protect a family's finances if the homemaker passes away during the policy term. Since housewives do not have a personal income, insurers assess eligibility based on the earning spouse's income, education, and existing life insurance coverage.
- Women-Specific Plans: Established insurers offer women-specific plans such as Bajaj Superwoman Term Plan and ICICI Life iProtect Smart Her. Plans such as Super Woman offer benefits like an accelerated terminal illness payout of up to ₹2 crore and a Life Stage Benefit that allows you to increase your cover after major milestones such as marriage or childbirth, subject to policy conditions.
Sample Premium Comparison: Male vs. Female
Note: The annual premiums shown are for healthy, salaried, non-smoking individuals residing in Delhi (pincode: 110010), with ₹2 crore life cover until age 65. These figures exclude first-year discounts.
Use the Ditto term insurance premium calculator to get a rough estimate of base premiums.
Actual premiums for a term insurance plan for women may vary based on your age, health, and underwriting assessment.
Eligibility Criteria for Term Insurance for Women
Besides the pricing advantage, term insurance eligibility and underwriting scrutiny remain the same compared to male profiles.
- Entry Age: Most insurers accept applicants from age 18, with the maximum entry age generally ranging from 60 to 65 years.
- Maximum Coverage Age: Depending on the plan, coverage may continue until age 85–99. Choose a policy term that accounts for retirement, your youngest child's financial independence, and repaying major loans.
- Medical Tests: Insurers require medical tests based on your age, health history, and chosen sum assured.
- Education Eligibility: Insurers prefer applicants with a graduate degree. However, diploma holders and 10th- or 12th-pass applicants can also qualify, subject to higher minimum income requirements and the insurer’s underwriting criteria.
- Salary Requirements: Most insurers require salaried applicants to earn at least ₹2.5–₹5 lakh annually, depending on their profile, and to provide valid proof of income. Self-employed applicants may need to submit ITRs for the last 2–3 years to establish income stability. For more clarity, explore the income criteria for term insurance.
Benefits of Term Insurance for Women
Income Replacement
Financial Protection for Homemakers
Protection for Single Mothers
Protection for Unmarried Women
Independent Cover for Working Couples
Affordable Long-Term Cover
Additional Protection Through Riders
Why Does Term Insurance Cost Less for Women?
Women pay lower term insurance premiums than men because insurers often expect lower mortality rates among female applicants with comparable ages and risk profiles. This can mean a lower probability of a claim during the policy term.
However, insurers do not calculate premiums based on life expectancy alone. They consider age-specific mortality rates, health history, policy duration, expected claims, and other pricing factors. A woman's medical risks can also affect her premium.
Why Choose Ditto for Term Insurance?
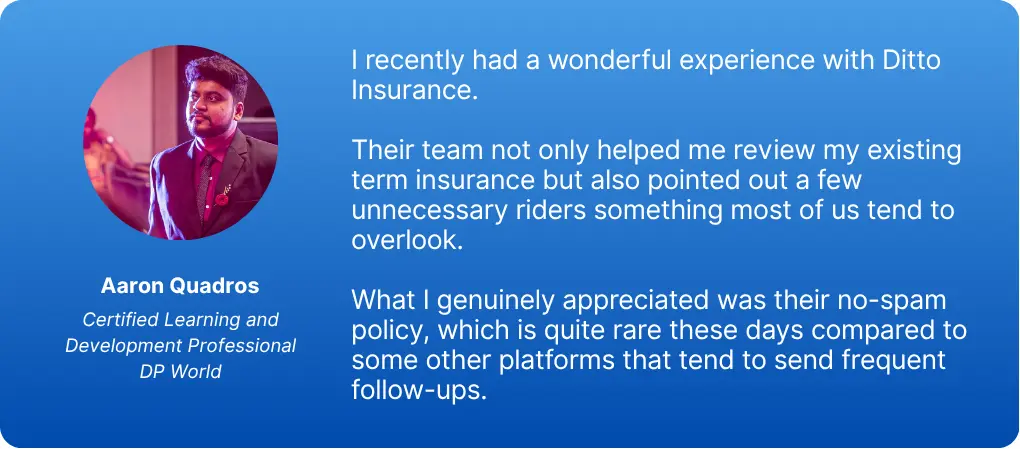
At Ditto, we’ve assisted over 12,00,000 people with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
You can book a FREE consultation. Slots are running out, so make sure you book a call or chat on WhatsApp now!
Conclusion
Term insurance is an important part of financial planning for women, whether they earn an income or manage household responsibilities. Choose a cover that reflects your dependents, liabilities, and long-term financial commitments. Compare the best term insurance plans for women based on premiums, policy features, and insurer track record.
Frequently Asked Questions
Last updated on: