

Overview
HDFC Life ranks third among India’s largest listed life insurers by market capitalization, with a strong business presence and a higher claim settlement ratio. Bajaj Life, meanwhile, stands out with the highest solvency ratio among the best term insurance companies.
While both insurers have strengths, which one is better for you?
To help you decide, this guide compares HDFC Life and Bajaj Life across key performance metrics, term plan features, premiums, and available riders, making it easier to choose the insurer that best fits your needs.
About the Insurers
Bajaj Life
- Establishment: Bajaj Life Insurance was established in 2001.
- Ownership: Following Allianz SE’s exit in March 2026, Bajaj promoter-group entities collectively hold 100% ownership of Bajaj Life Insurance.
- Branches: The insurer operates over 598 branches across India.
- IRDAI Registration: Bajaj Life Insurance holds IRDAI registration number 116.
- Individual Agents: The insurer has a network of approximately 1.64 lakh individual agents.
HDFC Life
- Establishment: HDFC Life was established in 2000.
- IRDAI Registration: The insurer holds IRDAI registration number 101.
- Promoter: HDFC Bank Limited is HDFC Life’s primary promoter.
- Network: HDFC Life operates 715 offices across India.
- Agent Network: The insurer has 2.71 lakh agents.
Talk to an expert
today and
find
the right
insurance for you.
Bajaj Life and HDFC Life: Performance Metrics
Note: The data is sourced from Bajaj Life public disclosures, HDFC Life’s public disclosures, and IRDAI annual reports. Explore the Ditto Data Lab for more such metrics.
Bajaj Life eTouch II vs. HDFC Life Click 2 Protect Supreme Plus: Key Features Compared
- Terminal Illness Benefit: Both plans offer an accelerated terminal illness benefit of up to ₹2 crore. HDFC Life Click 2 Protect Supreme Plus requires certification from two doctors stating that the policyholder is not expected to survive beyond six months. Bajaj Life eTouch II uses a similar six-month definition involving a medical practitioner and its appointed medical practitioner. Bajaj Life also offers a waiver of future premiums on the remaining sum assured, subject to policy terms.
- Life Stage Cover Increase: Both plans allow policyholders to increase their cover after major life events, such as marriage, childbirth, or a home purchase, subject to eligibility and additional premiums. Click 2 Protect Supreme Plus also allows a 50% increase for a home loan, capped at ₹50 lakh. On the other hand, eTouch II also allows increases for education loans and adoption, with specific limits for each event.
- Special Exit Benefit: Both plans offer an option to exit the policy and recover eligible premiums after 25 policy years, subject to conditions. Click 2 Protect Supreme Plus requires a minimum policy term of 31 years, while eTouch II requires the policyholder to be at least 60 years old when exercising the benefit. HDFC Life excludes policies with the Return of Premium option or Life Goal variant, while Bajaj Life excludes policies that have used the Life Stage Benefit.
- Premium Break or Continuance Benefit: Click 2 Protect Supreme Plus allows eligible policyholders to defer premiums for 12 months after five policy years while retaining cover. Bajaj Life eTouch II offers a similar 12-month deferral after three policy years, subject to conditions. Both require advance written notice and generally impose a five-year gap between uses.
- Instant Claim Payout: Click 2 Protect Supreme Plus offers an immediate payout of ₹2 lakh for eligible policies with a sum assured of ₹1 crore to below ₹2 crore, or ₹5 lakh for cover of ₹2 crore or more. Payment is targeted within one working day of claim intimation, subject to documents. eTouch II offers ₹2 lakh within three working days for eligible policies with at least ₹50 lakh cover, subject to claim requirements.
- Health and Wellness Benefits: HDFC Life offers teleconsultations, preventive health checks, cancer screening, mental wellness support, nutrition consultations, and network discounts through its Life Rewards app. Bajaj Life offers teleconsultations, psychologist consultations, nutrition guidance, fitness resources, health checks, and discounts through its Life Assist app. Bajaj Life also includes certain women-specific benefits, such as pregnancy-related OPD support, subject to the applicable terms.
Note: Besides the flagship plans mentioned above, Bajaj Life also offers iSecure II and Superwoman, while HDFC Life offers Click 2 Protect Elite Pro and Click 2 Protect Ultimate.
For more details, refer to the HDFC Life Insurance review and Bajaj Life Insurance term plan review.
Riders Offered
Critical Illness Rider
Both plans offer an optional critical illness rider that pays a lump sum in addition to the base cover. HDFC Life covers 60 illnesses, with a 90-day waiting period and a 15-day survival period. Bajaj Life offers versions covering 10, 25, or 60 illnesses, with a 90-day waiting period and a 14-day survival period. Both offer up to ₹1.5 crore in rider cover, subject to policy limits.
Waiver of Premium
HDFC Life offers an optional rider that waives future premiums after a qualifying critical illness or permanent disability, subject to the policy terms. Bajaj Life includes a waiver of premium benefit for accidental total and permanent disability and terminal illness. Its stated waiting and survival period is 180 days. Check each policy’s wording for exact eligibility conditions and the scope of the premium waiver.
Accidental Death Benefit
HDFC Life offers accidental death cover through its LiveWell rider, with a maximum cover of ₹5 crore. The payout can be a lump sum or a lump sum plus monthly income for 10 years. Bajaj Life offers an Accidental Death Benefit Rider, with cover limits that vary by plan variant. The maximum is ₹1 crore under Life Shield and Life Shield ROP, and ₹2 crore under Life Shield Plus for Indian residents.
Accidental Disability Benefit
HDFC Life’s Accidental Income Benefit pays a monthly income equal to 1% of the rider sum assured for 10 years after qualifying total and permanent disability due to an accident. Its maximum rider cover is ₹2 crore. Bajaj Life’s disability rider pays 100% of the rider sum assured for total permanent disability and 50% for partial permanent disability, subject to policy terms.
Note: We recommend considering riders such as the critical illness rider and waiver of premium rider to strengthen your term insurance coverage, based on your needs and budget.
Sample Premiums Comparison by Age and Cover
The annual premium comparison assumes a healthy, salaried, non-smoking male from Delhi (pincode: 110010) seeking ₹2 crore in term coverage until age 65. First-year discounts are excluded.
Note: Actual premiums vary based on underwriting, age, health, and individual risk factors. You can use the Ditto premium calculator for rough estimates of your premiums.
Pros and Cons of Bajaj Life and HDFC Life Insurance
Pros of Bajaj Life
- Higher Solvency Ratio: Bajaj Life’s solvency ratio is higher than HDFC Life, indicating a stronger capital buffer relative to regulatory requirements.
- NRI Offerings: Bajaj Life offers better term insurance for NRIs tailored to Non-Resident Indians (NRIs), giving eligible applicants more flexibility to secure life cover while living abroad.
Cons of Bajaj Life
- Lower Claim Settlement Record: Bajaj Life Insurance claim settlement ratio is slightly lower than HDFC Life Insurance claim settlement ratio. HDFC Life has maintained a marginally better record over the same period.
- Higher Complaint Levels: Bajaj Life receives slightly more complaints than HDFC Life, which may matter if you prioritize a smoother customer service experience.
Pros of HDFC Life
- Larger Business Scale: HDFC Life’s annual business volume is 2.58 times higher, reflecting its larger business operations and market presence.
- Higher Instant Claim Payout: HDFC Life offers higher instant claim payouts for eligible policies, helping families access funds sooner after a claim is reported, subject to policy conditions and documentation.
Cons of HDFC Life
- Potentially Higher Premiums: HDFC Life Insurance plans can charge more than Bajaj Life for comparable term cover. Compare personalized quotes before deciding, as rates depend on your age, health, and policy options.
- Waiver of Premium Comes at an Extra Cost: HDFC Life’s Waiver of Premium benefit requires an optional rider and additional premiums.
Why Choose Ditto for Term Insurance?
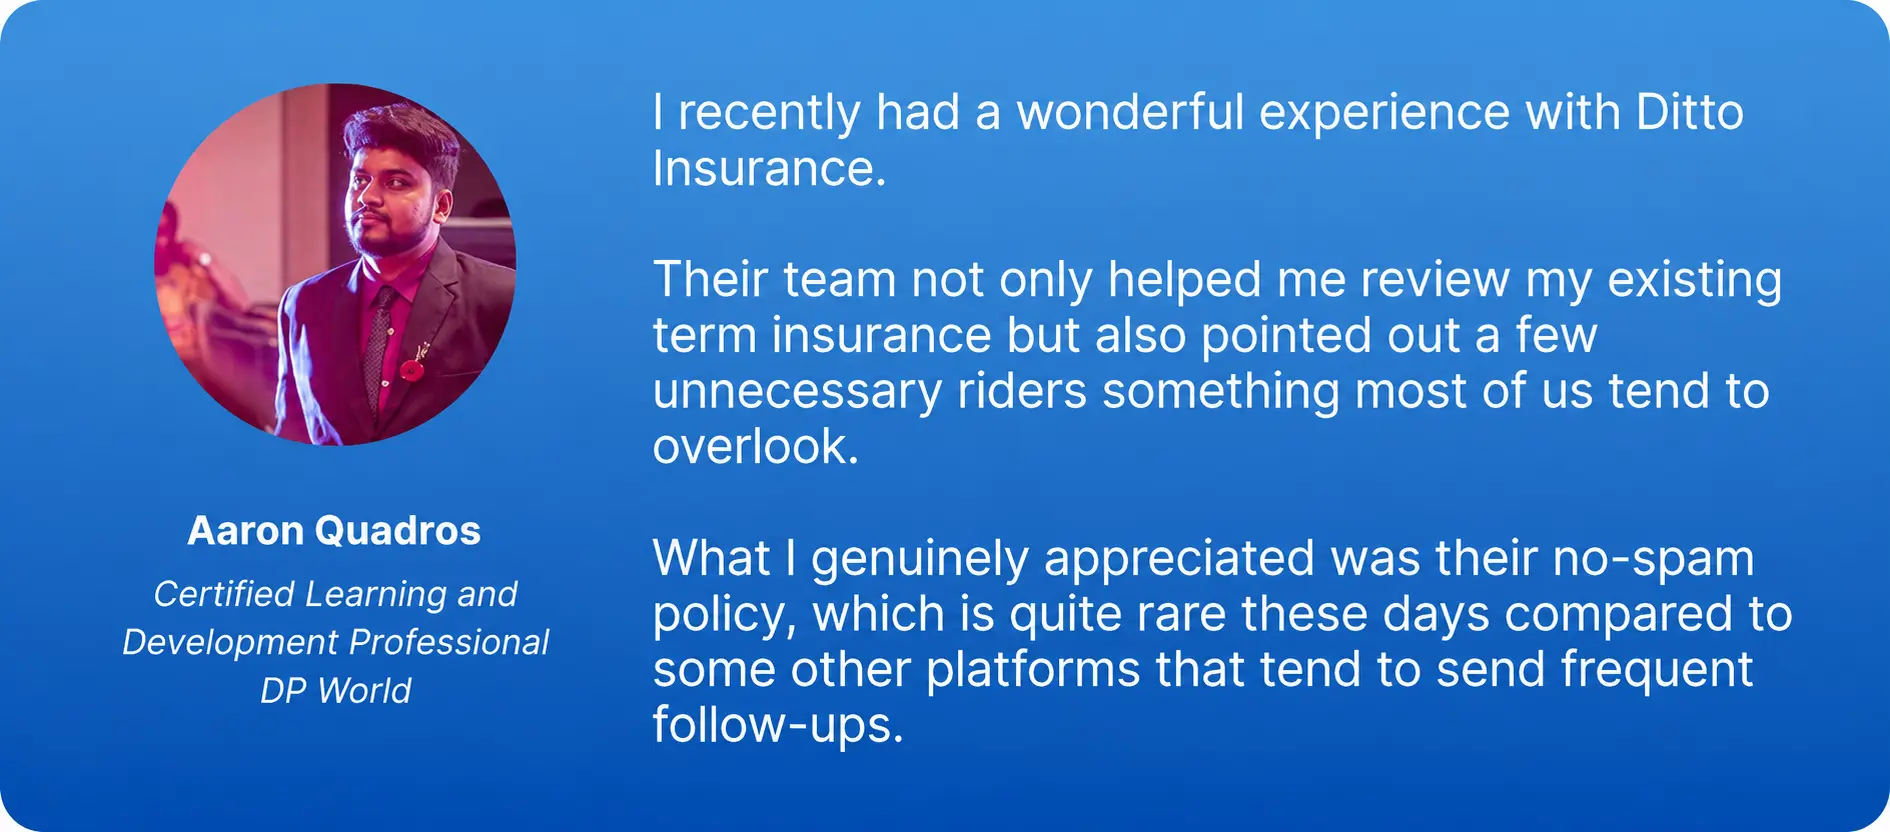
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Both HDFC Life and Bajaj Life offer strong term insurance options, but HDFC Life has an edge in claim settlement performance, business scale, plan features, and complaint metrics. Bajaj Life stands out for its higher solvency ratio and potentially more affordable premiums.
Choose:
- HDFC Life: If you value a higher claim settlement ratio and a larger business presence.
- Bajaj Life: If you prioritize a higher solvency ratio and potentially lower premiums.
At Ditto, we recommend HDFC Life Click 2 Protect Supreme Plus for its range of features. However, both flagship plans rank among the best term insurance plans. Compare personalized quotes and policy terms before choosing.
Frequently Asked Questions
Last updated on: