

Overview
According to IRDAI’s FY 2024-25 annual report, non-participating life products collected over ₹3.75 lakh crore in premiums in FY 2024-25, compared with over ₹3.39 lakh crore for participating life products.
However, higher premium collections do not necessarily translate into better returns or greater value for policyholders. These figures include existing policies and group business, so they don't show which product type offers better returns or attracts more new buyers.
To make an informed choice, it’s important to understand how these two product types differ in their benefits, returns, and risk profiles. In this guide, we explain how a participating and non-participating policy works, what to check before buying, and how to evaluate their potential returns.
What Is Participating Life Insurance?
Participating (Par) life insurance policies allow policyholders to share in the insurer’s surplus through bonuses or other declared benefits. These payouts are not guaranteed and depend on the insurer’s financial performance and the policy’s terms and conditions.
Participating benefits aim to reflect the policyholder’s share of the insurer’s surplus, subject to smoothing practices, the insurer’s bonus policy, and the product structure.
Note: The key difference between participating and non-participating life insurance plans lies in how they share profits and provide benefits.
How Do Insurers Distribute Surplus to Participating Policyholders?
Let's take the example of LIC's surplus distribution policy.
From FY 2024–25 onward, Life Insurance Corporation of India (LIC) allocates or reserves 90% of the surplus emerging from its participating business for participating policyholders. In contrast, 100% of the surplus arising from its non-participating business is allocated or reserved for shareholders.
However, this does not mean individual policyholders receive 90% of investment profits. LIC determines discretionary bonuses using factors such as bonus-earning capacity, asset share, smoothing, policyholder expectations, and solvency requirements. It may also cross-subsidize benefits across products and generations of policyholders.
Talk to an expert
today and
find
the right
insurance for you.
Types of Bonuses Under Participating Plans
Simple Reversionary Bonus
Declared periodically and added to the policy benefits. Future bonuses are not guaranteed, while vested bonuses are generally payable under the policy terms.
Compound Reversionary Bonus
Similar to a simple reversionary bonus, but previous bonuses may also form part of the base for future bonus calculations.
Cash Bonus
Paid to the policyholder at specified intervals if declared, rather than accumulated until maturity.
Interim Bonus
May cover the period between the last bonus declaration or actuarial valuation and a claim or maturity event, subject to policy rules.
Terminal Bonus (Final Additional Bonus)
A discretionary additional benefit that may be payable on maturity, death, or another specified event.
Loyalty Addition
An additional benefit some insurers offer to eligible policies, subject to product-specific conditions.
Note: Participating (Par) policies allow eligible policyholders to receive a share of the insurer’s surplus. However, this does not make policyholders shareholders or owners of the insurance company.
Participating does not mean market-linked, and non-participating does not mean risk-free. Bonuses are not always guaranteed, and their presence does not automatically make participating plans better for wealth creation. Compare the policy’s guaranteed benefits, projected returns, and costs before deciding.
What Is Non-Participating Life Insurance?
Non-participating (Non-Par) life insurance policies do not allow policyholders to share in the insurer’s profits. Instead, they offer benefits defined by the policy, which may be guaranteed or non-guaranteed depending on the product’s terms and conditions.
A non-par product can offer guaranteed additions. LIC Jeevan Utsav, for example, provides ₹40 per ₹1,000 of basic sum assured during the premium-paying term. These are contractual benefits, not discretionary bonuses, and may not be payable immediately when credited.
Here’s a snippet from IRDAI regulations defining the two terms.
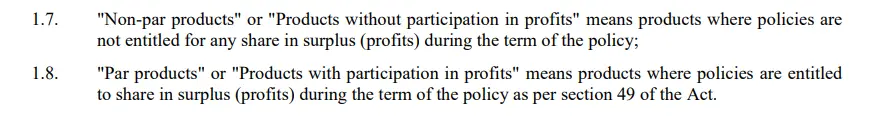
Note: Besides participating and non-participating plans, IRDAI classifies life insurance products into other categories, including linked and non-linked products, pension plans, annuity plans, savings and pure-risk products.
There are several types of life insurance plans.
Note: A Return of Premium (ROP) term plan combines life cover with a base premium refund if the policyholder survives the policy term, subject to policy conditions. This makes it a savings plan, different from a pure term plan, which offers protection without a maturity payout.
Sample Premiums: Participating vs. Non-Participating Life Plans
Illustration 1: Participating Plan
Consider a 30-year-old policyholder who purchases the LIC Jeevan Labh plan with a basic sum assured of ₹2 lakh and a policy term of 25 years. The annual premium is ₹10,025, payable for 16 years, for a total premium outlay of ₹1,60,400. The figures are derived from the LIC Jeevan Labh plan brochure.
Maturity Benefit
Note: IRDAI currently stipulates 4% and 8% gross investment-return assumptions for non-guaranteed benefit illustrations. These are illustration assumptions, not guaranteed returns.
LIC Jeevan Labh is a traditional participating life insurance plan, not a high-return investment product. Based on LIC’s official benefit illustrations, the estimated annualized Internal Rate of Return (IRR) is approximately 1.8% to 1.9% under the 4% scenario and 4.8% to 5.0% under the 8% scenario.
These estimates depend on LIC declaring bonuses similar to those shown in the benefit illustration. Actual returns may differ because future bonuses are not guaranteed.
Illustration 2: Non-Participating Plan
This example uses illustrative premiums for LIC New Bima Jyoti, based on a basic sum assured of ₹10 lakh for a 35-year-old with a 20-year policy term. Actual premiums vary by age, policy term, underwriting factors, and insurer pricing. The figures are based on the official plan brochure.
Sample Premiums and Returns
LIC New Bima Jyoti offers guaranteed additions starting at 6% of eligible annualized premiums, but this is not the investment return. Based on the illustration, the estimated IRR is 4.2% annually.
Note: The two examples differ in investment structure, premiums, policy terms, charges, and risk exposure. Therefore, their maturity values and IRRs cannot establish whether participating or non-participating plans deliver higher returns.
Participating plans may charge higher premiums (bonus loading) than comparable non-participating plans to account for potential profit distributions, but the difference varies by product and policy terms. Do not assume a fixed 20% to 30% premium gap across all plans.
Non-par plans offer defined benefits that may be guaranteed under the contract but are easier to measure, while par plans may provide additional bonuses based on declared surplus. These bonuses are not guaranteed and may not offset inflation or deliver higher returns.
Payout Comparison Between Participating & Non-Participating Life Plans
Pros & Cons of Participating vs. Non-Participating Life Insurance
Pros of Participating Life Insurance
- Long-Term Savings: Combine guaranteed benefits, where applicable, with potential bonus growth.
- Bonus Vesting: Vested bonuses may become guaranteed according to the policy terms.
- Flexible Structures: Available in savings, income, endowment, whole-life, and pension products.
Cons of Participating Life Insurance
- Uncertain Bonuses: Future bonuses depend on the insurer’s performance, interest rates, and bonus declarations.
- Unclear Returns: Actual returns are harder to estimate because future bonuses are not guaranteed.
- Delayed Benefits: A significant portion of the payout may arrive at maturity.
- Limited Transparency: Returns are less directly visible than NAV-based investment products.
- Exit Costs: Early surrender can reduce the value you receive, depending on policy terms.
Pros of Non-Participating Life Insurance
- Predictable Benefits: Contractual benefits are defined upfront and may be guaranteed under the policy terms.
- No Bonus Uncertainty: Benefits do not depend on future bonus declarations or insurer surplus.
- Clearer Financial Planning: Helps plan for known future expenses and financial goals.
- Easier Return Comparison: Defined cash flows make it easier to calculate and compare returns.
- Goal-Based Savings: Can support retirement planning and other long-term goals through predictable payouts.
Cons of non-participating Life Insurance
- Inflation Risk: Fixed nominal payouts may lose purchasing power over time.
- Conservative Returns: Long-term guarantees may come with modest returns.
- Surrender Penalties: Early exit will result in a lower payout than expected.
- Limited Life Cover: Savings-oriented plans may not provide enough protection for dependents.
Note: When comparing participating vs non-participating insurance, the key difference lies in whether there is a bonus/profit payout.
Why Choose Ditto for Life Insurance?
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
If your priority is family protection, start by comparing the best term insurance plans that match your coverage needs, budget, and financial responsibilities. Keep life insurance focused on protection, not as your primary investment.
If you want long-term savings, compare guaranteed benefits, projected bonuses, surrender values, and annualized returns before choosing a traditional life insurance plan. Evaluate alternatives such as Fixed Deposits (FDs), Public Provident Fund (PPF), Floating Rate Savings Bonds (FRSBs), and debt mutual funds based on your goals, risk tolerance, liquidity needs, and tax treatment.
Note: Ditto currently offers advisory only in the pure term insurance plans segment and does not offer traditional participating or non-participating savings and investment-oriented life insurance products.
Frequently Asked Questions
Last updated on: