Term insurance for doctors is a pure protection plan that pays the nominee a lump sum if the policyholder passes away during the policy period.
Why It Matters for Doctors
Medical education and clinic loans can fall on your family.
Early-career and private-practice income can be uneven.
Infections and occupational accidents add to health risks.
Eligibility
Entry is available from age 18 to 60 or 65, depending on the plan, with cover up to age 85 to 100.
Income proof requires salary slips or 2 to 3 years of ITRs for private practice.
An occupation questionnaire assesses your specialty’s risks, and high-risk occupations can mean an extra premium.
Essential Riders to Add
Critical Illness: Pays a lump sum if you’re diagnosed with a covered illness, such as cancer or a heart attack, to help with treatment and lost income.
Waiver of Premium: Stops your future premiums if you’re diagnosed with a critical illness or disability, while your cover continues.
This is where term insurance for doctors helps. It offers an affordable way to protect your loved ones during this crucial phase, with substantial life cover at a relatively low annual premium.
In this guide, we break down why doctors need a term plan, which plans work well, sample premiums, how much cover to buy, and what insurers check.
Not sure how much cover your family needs? Book a free call or chat on WhatsApp with Ditto's IRDAI-certified advisors.
Why Is Term Insurance Important for Doctors?
01
Earning Starts Late
The MBBS degree alone takes around 5.5 years, including the internship, so you have fewer years to build savings. In the early years of your career, your income may also not be stable enough to cover your dependents and loans.
02
Loans Don't Stop
Many doctors start with medical education loans, clinic or hospital setup loans, and equipment EMIs. These loans don’t go away if something happens to you. Without a term plan, your family may have to repay them from their own savings.
03
Health Risks on the Job
Doctors are exposed to infections and workplace accidents.
The payout is also tax-free for your nominee under Section 10(10D) (now Section 11, read with Schedule II), regardless of which tax regime you follow. Premiums qualify for a deduction of up to ₹1.5 lakh a year under Section 80C (now Section 123), but only under the old tax regime.
Riders Doctors Should Consider
Start with acritical illness rider. It pays a lump sum if you're diagnosed with a listed illness such as cancer, a heart attack, or a stroke. Your base term cover pays only on death, so this rider protects you while you're alive and helps with income loss.
Next, addwaiver of premium. If a critical illness or disability prevents you from working, you no longer need to pay premiums, and your cover stays active until the end of the policy period.
Note: Premiums you pay for health-based riders like these also qualify for a tax deduction under Section 80D (now Section 126), but only under the old tax regime.
The critical illness rider covers up to 64 illnesses and provides temporary cash relief if an illness stops your practice. Limited pay (5 to 15 years, or till 60) suits early retirement.
Allows you to increase cover as life changes: marriage, children, or a home loan. Extend the term at maturity, subject to underwriting, if you plan to practice longer.
Allows you to increase cover by up to 100% when a home loan is disbursed. Limited pay (5 to 15 years, or till 60) lets you finish paying in your peak earning years.
Premiums are waived if an accident leaves you totally and permanently disabled, or in terminal illness. It's Ditto's first choice for NRI doctors working abroad.
Cover continuance lets you defer premiums for up to 12 months during a cash crunch while full cover stays active. Useful if practice income dips.
Talk to an expert today and find the right insurance for you.
Sample Premiums for Term Insurance for Doctors
The premiums shown are indicative and based on a non-smoker, healthy, self-employed, graduate doctor earning ₹10 lakh a year in Delhi (pincode: 110010), for ₹2 crore of cover until age 65, without first-year discounts.
Age and Gender
Axis Max Life Smart Term Plan Plus
HDFC Life Click 2 Protect Supreme Plus
ICICI Life iProtect Smart Plus
30, Male
₹20,656
₹22,637
₹19,283
30, Female
₹17,558
₹19,242
₹16,391
35, Male
₹26,154
₹28,006
₹26,030
35, Female
₹22,232
₹23,805
₹22,126
40, Male
₹34,380
₹34,086
₹34,228
40, Female
₹29,224
₹28,973
₹29,094
Note: If you're a salaried doctor, your first-year premium may be lower because of temporary discounts. Final premiums vary based on age, medical history, policy cover, rider options, duration, and lifestyle habits. Check your premium estimate on Ditto'sterm insurance premium calculator.
How Much Term Insurance Cover Do Doctors Need?
Ditto works out cover using the expense-based method. We calculate what your family would spend until the age you want the cover to last, account for rising costs, and add any loans they’d have to repay.
Consider a 35-year-old doctor with:
Monthly Household Expenses: ₹50,000, not counting EMIs and investments
Outstanding Clinic Loan: ₹10 lakh
Cover Until: Age 65
Inflation: Expenses rise by 5% a year
Based on this, the doctor would need about ₹2.2 crore of cover to maintain the family’s lifestyle. Insurers also set an upper limit on the cover they offer based on your income, age, occupation, and education.
Term Insurance for Doctors: Eligibility & Requirements
Age
Entry from age 18 to 60 or 65, depending on the plan, with cover lasting up to age 85 to 99 or 100.
Income
For graduates, the minimum is ₹2.5 lakh to ₹3 lakh a year if salaried, and ₹4 lakh to ₹5 lakh if self-employed. Beyond the minimum, insurers want to understand your financial profile for underwriting: income consistency, likelihood of continuation, and overall stability. Many doctors face issues here, especially early in their careers.
Documents
PAN, address proof, a photo, and income proof, which depends on how you earn:
Salaried: Last 3 months' salary slips and 3 to 6 months' bank statements.
Private Practice: 2 to 3 years of ITRs with a CA-certified income computation. Insurers count only the income under business or profession, not gross receipts, capital gains, F&O, or interest income. Our guide onterm insurance for the self-employed explains the ITR rules.
Resident Doctors Earning a Stipend: Without proper payslips, standard plans are hard to get. Insurers want 3 to 6 months of steady stipend income and letters, or you can try non-standard income plans like Bajaj Life iSecure II or ICICI Life iProtect Super.
Medicals
Video medicals or physical tests, depending on your age and cover. The insurer organizes these and bears the costs.
Note: If you file your ITR under presumptive taxation, the income you declare may be lower than your clinic’s gross receipts. Insurers base your cover on that declared income and other financial proof, so check how they calculate eligible income before assuming your clinic’s revenue will support a large cover.
Occupation Questionnaire and Underwriting
Expect an occupation questionnaire, likeHDFC Life’s, about your field of medicine and risks such as infectious diseases or surgery. Based on your answers, theunderwriting team may add an extra premium loading or limit your term or cover amount. So be upfront about your specialty, smoking habits, and medical history, as hiding something can put your family’s claim at risk.
Why Choose Ditto for Term Insurance?
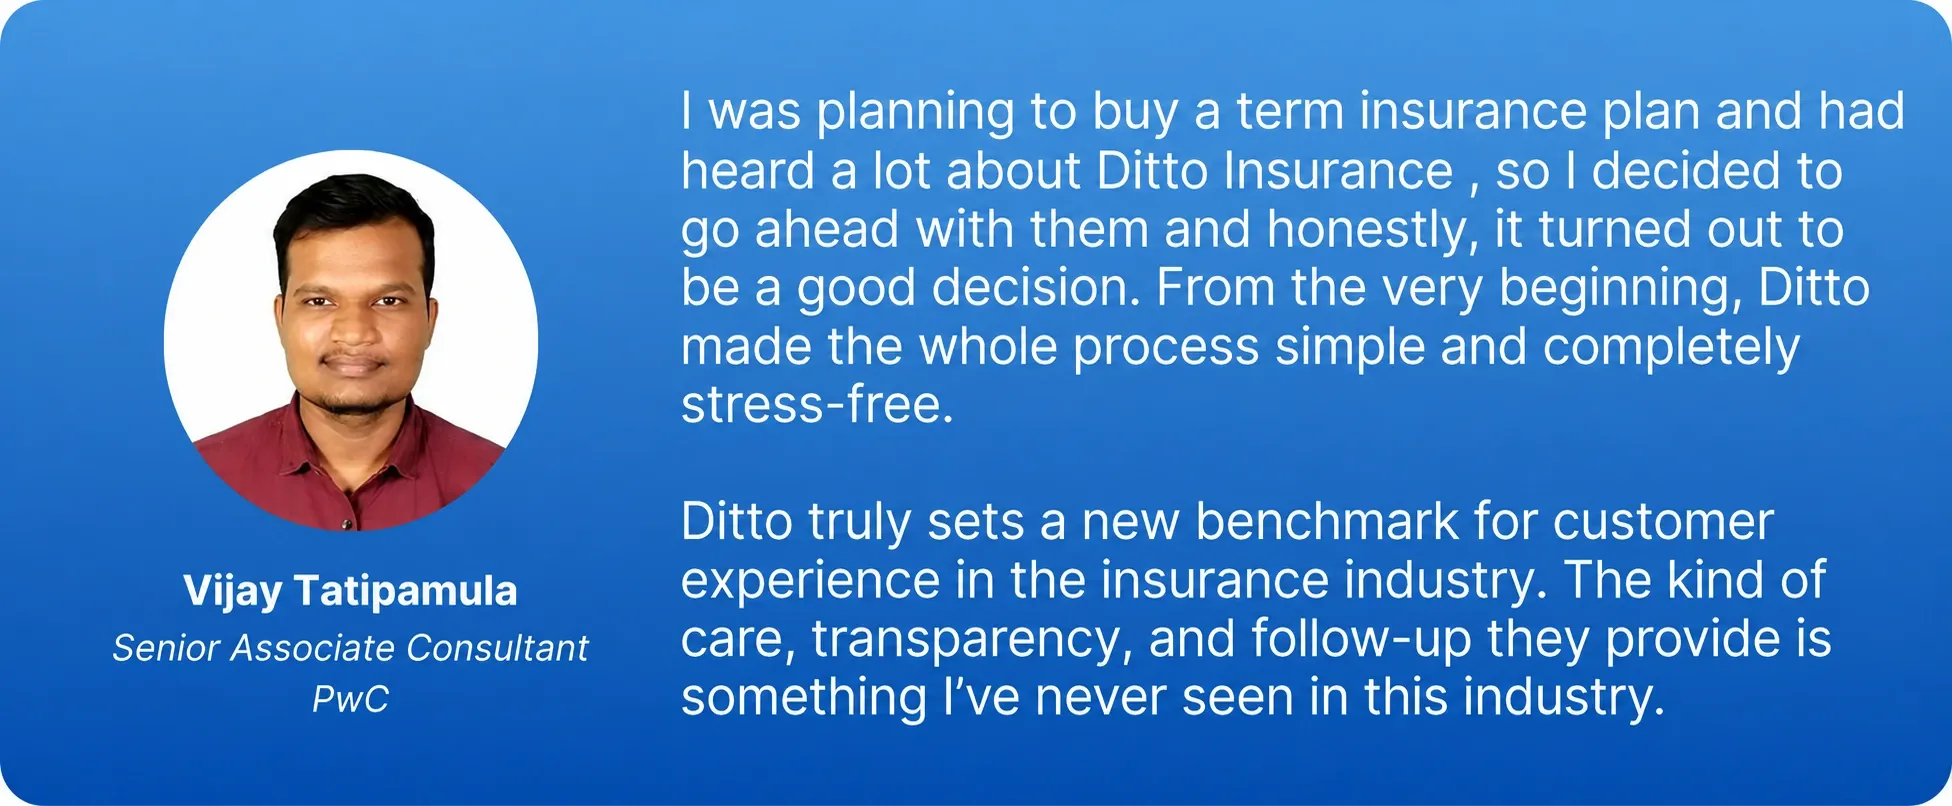
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Vijay below love us:
100% Free Consultation
No Spam. No Sales Pressure.
Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
Backed by Zerodha
Dedicated Claim Support Team
Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Don’t wait for your practice to settle before buying a term plan. The earlier you buy, the more cover you lock in for less. If your income is still growing, start with the cover you qualify for today and add more as your practice grows. As a next step, list your loans and monthly expenses, then compare plans on cover, riders, and premiums, and consult a Ditto advisor for free before you apply.
Frequently Asked Questions
Is term insurance enough protection for a doctor in private practice in India?
Not on its own. A term plan pays out only on the policyholder’s death, but private practice brings other risks too. Hospital bills need health insurance, and a patient’s negligence claim needs professional indemnity cover. There’s also the risk of a serious illness that keeps you away from your clinic for months, with no salary coming in. A critical illness rider and waiver of premium can help with that. So think of term insurance as the foundation, and build the rest of your insurance for doctors around it.
Does professional indemnity insurance replace term insurance for doctors?
No, because they protect different people. Professional indemnity insurance protects you and your practice. If a patient claims you were negligent, say over an incorrect diagnosis or a surgical error, it pays your legal defense costs and any damages. But it pays nothing if the policyholder dies. That’s the job of life insurance for doctors, like a term plan, which pays the nominee a lump sum. One protects your career and savings, while the other protects your family’s future. Most practicing doctors need both.
Can a junior resident doctor with a stipend get a high-value term plan?
It’s possible, but harder than for a salaried or established doctor. Residents rarely get a proper payslip, so insurers often don't issue standard term plans based on a stipend alone. Insurers usually want 3 to 6 months of consistent stipend income and stipend letters as proof. Even then, the cover you’re offered depends on your income. If a standard plan doesn’t work out, try non-standard income plans like Bajaj Life iSecure II or ICICI Life iProtect Super, and add cover as your income grows.
Do insurers charge extra for term insurance if a doctor works with radiation or infectious patients?
They can, depending on the underwriting process. Insurers usually ask doctors to fill out an occupation questionnaire covering your field of medicine and the risks you face, such as exposure to infectious diseases or radiation, or the demands of surgery. Based on your answers, the underwriter may add a loading charge or restrict your policy term, riders offered, or cover amount. There’s no fixed loading, so it’s decided on a case-by-case basis. The key is honest disclosure. Misrepresenting your specialty or work setting can complicate claims later.
Is a limited pay term plan better for doctors who plan to retire early?
It can be, if you can comfortably afford a higher premium now. With limited pay, you finish paying within a set period, such as 10 or 15 years or until age 60, but your cover runs for the full term. The trade-off is cost, as each yearly premium is much higher than on regular pay. So Ditto suggests regular pay for most people. But if you plan to retire early, finishing payments during your peak earning years can bring peace of mind.
Can NRI doctors working abroad buy term insurance in India?
Yes. If you’re an NRI aged 18 to 60, you can buy from major Indian insurers. Bajaj Life eTouch II is Ditto’s first pick for NRIs, with cover up to ₹20 crore, and it requires graduates to have an annual income of at least ₹10 lakh. The process usually starts with a video medical, though physical tests may follow based on your age and cover. If you’re visiting India anyway, doing medicals then is often simpler and cost-effective. Keep your passport, overseas address proof, and FATCA declaration ready.
Is a return of premium plan a good option for doctors who want their money back?
Usually not, once you look at the numbers. A return of premium plan costs about 60% to 100% more than a pure term plan. And if you survive the term, all you get back is the premiums you paid, minus rider premiums, with no interest, profit, or capital gain. A better approach is to buy a pure term plan and invest the difference in the Public Provident Fund (PPF), National Pension System (NPS), mutual funds, or even fixed deposits (FDs). That way, the extra money keeps working for you instead of sitting with the insurer earning nothing.
Can doctors claim tax benefits on term insurance premiums?
Yes, if you file under the old tax regime. Your premiums qualify for a deduction of up to ₹1.5 lakh a year under Section 80C (now Section 123), a limit you share with other investments like PPF and ELSS. The new tax regime doesn’t allow this deduction, though it has a higher tax exemption limit. Either way, the death benefit your nominee receives is fully tax-free under Section 10(10D) (now Section 11, read with Schedule II). Any returns your family later earns by investing that payout are taxed normally.
What happens if a doctor misses a term insurance premium payment?
You don’t lose cover right away because every policy includes a grace period. It’s 15 days for monthly payments and 30 days for quarterly, half-yearly, or annual payments, and your cover stays active throughout. If you still haven’t paid by the end of it, the policy lapses and your family loses protection. You can revive it within 5 years of the lapse by paying the missed premiums with interest and any penalty charges, and clearing medical underwriting if the insurer asks. With busy clinic days, setting up auto-debit is the easiest way to avoid this.
Will Term Insurance Cover a Doctor Who Can No Longer Practice Medicine?
Not necessarily. A regular term plan pays only on the policyholder’s death, so it doesn’t cover income lost to a disability. Disability riders help, but they usually pay only for total and permanent disability, meaning you can’t work at all. For example, a surgeon who develops a hand tremor may be unable to operate but could still work as a consultant or teacher, so the claim may not qualify. Before you buy, check how the rider defines disability, as losing your specialty alone may not trigger a payout.