

Overview
According to the Labour Bureau, Surat’s Consumer Price Index for Industrial Workers stood at 145.7 in July 2026.
As everyday expenses rise, your family’s financial needs can also increase. So, how much term insurance do you need in Surat to protect your family’s lifestyle, future goals, and outstanding liabilities?
This guide explains term insurance in Surat, including how much coverage you need, what affects premiums, and key factors to consider before buying a policy.
What Is Term Insurance in Surat?
Term insurance in Surat is a pure life insurance plan that protects your family financially if the policyholder passes away during the policy term. You pay a regular premium for a fixed amount of life cover.
Note: Rising property prices and education costs can increase your family’s future financial needs in Surat. NHB RESIDEX reports 5.4% year-on-year (base year FY 2024-25) housing appreciation, and engineering fees are also rising.
According to The Times of India (TOI), the annual B.E. fee at Sarvajanik College in Surat increased from ₹1.29 lakh to ₹1.36 lakh. With rising costs, term insurance can help cover major expenses and long-term goals if you are no longer around to fund them.
Talk to an expert
today and
find
the right
insurance for you.
Best Term Insurance Plans in Surat
- Axis Max Life Smart Term Plan Plus: Axis Max Life Smart Term Plan Plus offers an optional critical illness rider that covers up to 64 illnesses for up to 30 years. It also comes with an accelerated terminal illness benefit of up to ₹1 crore, allowing eligible policyholders to receive part of the death benefit early after a qualifying diagnosis.
- HDFC Life Click 2 Protect Supreme Plus: This plan offers a Life Stage Benefit that can increase your life cover after milestones such as marriage or childbirth without requiring a fresh policy application. With HDFC Life Click 2 Protect Supreme Plus, you can also opt for a critical illness rider that covers up to 60 illnesses for up to 15 years.
- ICICI Life iProtect Smart Plus: This plan offers a Premium Break option that allows eligible policyholders to defer premiums for up to 12 months after meeting the specified payment conditions. ICICI Life iProtect Smart Plus also provides an instant partial payout of up to ₹3 lakh for eligible high sum assured policies.
- Bajaj Life eTouch II: The plan offers a terminal illness benefit of up to ₹2 crore for eligible policyholders. Bajaj Life eTouch II also includes a waiver of premium option for certain covered events, including accidental disability, subject to the policy’s terms, conditions, and exclusions.
- Aditya Birla Sun Life Super Term Plan: This plan offers an optional accelerated critical illness benefit that covers 42 illnesses and can pay up to 50% of the sum assured, subject to applicable limits. Aditya Birla Sun Life Super Term Plan also offers an in-built terminal illness benefit of up to ₹1 crore for eligible policyholders.
Note: The listed term plans are evaluated using Ditto’s detailed policy rating framework, which considers policy features, insurer strength, and long-term value.
How Much Term Insurance Cover Do You Need in Surat?
Your ideal sum assured depends on your income, household expenses, financial goals, outstanding liabilities, and existing assets. Consider how much your family would need to maintain their lifestyle and meet key financial commitments without your income.
For example, if your family currently spends ₹50,000 a month and you have a ₹10 lakh outstanding loan, the required cover can be around ₹2.7 crore. Assuming 5% inflation, your monthly household expenses could rise to approximately ₹2.9 lakh by 2061 to maintain a similar lifestyle.
Use the Ditto cover calculator to estimate your required sum assured. It factors in your age, policy term, monthly expenses, outstanding loans, financial goals, and existing life insurance cover to provide a rough estimate.
Term Insurance Sample Premium Comparison in Surat
Note: The annual premiums shown are illustrative figures for non-smoking male applicants in Surat (pincode 395003), with ₹2 crore coverage until age 65. These figures exclude first-year discounts and may vary based on underwriting, health profile, and insurer-specific terms. Use Ditto’s term premium calculator for a rough estimate.
Factors Affecting Term Insurance Premiums in Surat
- Age: Your age when you buy the policy affects the premium. Buying term insurance earlier can help you secure lower premiums for the policy term. Delaying the purchase may increase premiums as age-related mortality risk rises. Term insurance in your 20s costs less than term insurance in your 30s because of age.
- Tobacco and Smoking: Tobacco users generally pay higher premiums (60% to 100%, sometimes even more) because smoking and tobacco use increase the insurer’s assessed mortality risk. The difference can be significant compared with similar coverage for non-smoking applicants, depending on the insurer’s underwriting rules.
- Health and Medical History: Your health history can influence the premium and underwriting outcome. Conditions such as diabetes, hypertension, previous surgeries, or ongoing medication may lead to standard rates, premium loading, additional medical tests, postponement, or rejection.
- Gender: Insurers may price term insurance differently for men and women based on their actuarial assessment of mortality risk. Some insurers may offer women lower premiums for comparable coverage, although pricing varies by insurer and policy.
- Occupation: Your occupation can affect premiums if your work involves higher physical or environmental risks. Jobs involving mines, hazardous chemicals, heights, or heavy machinery may require additional underwriting and could result in premium loading or specific terms.
- Sum Assured: A higher sum assured generally means a higher premium because the insurer takes on greater financial liability. However, premiums may not rise proportionately. Some insurers offer high sum assured discounts, reducing the effective cost of more extensive coverage.
- Policy Term: A longer policy term generally costs more because the insurer provides protection for a longer period. However, choosing an excessively long term may not be necessary. Your coverage period should broadly match your income replacement needs and financial dependencies.
- Cover Structure: Level, increasing, and other cover structures can have different premiums. Increasing cover may help address rising financial responsibilities, but it is not free inflation protection. The higher potential benefit usually comes with an additional premium.
- Riders: Optional riders such as critical illness and waiver of premium can increase your overall premium. They may provide additional protection for specific events, but they should come after securing an adequate base sum assured for your family’s financial needs.
Did You Know?
How to Choose the Right Term Insurance Plan in Surat?
Choose the Right Coverage Amount
As a broad rule, insurers may offer term cover of around 20–30 times your annual income, subject to age, occupation, education, existing insurance, and financial underwriting. Treat this as an eligibility range, not your target. At Ditto, we recommend an expense-based approach that reflects your family’s actual financial needs.
Choose the Right Policy Tenure
Choose a policy term that lasts until your family is no longer financially dependent on your income. For most salaried individuals, coverage until 60–70 may work. Consider a longer tenure if you have young dependents, long-term liabilities, expect to work longer, or support family members beyond retirement.
Compare Insurers and Features
Do not choose a term plan based only on the lowest premium. Compare insurers on features such as zero-cost exit, rider options, claim servicing, and long-term track record. Don’t focus only on CSR. Instead, look at three-year averages for metrics such as amount settlement ratio and complaint volume to assess consistency.
Choose Riders Carefully
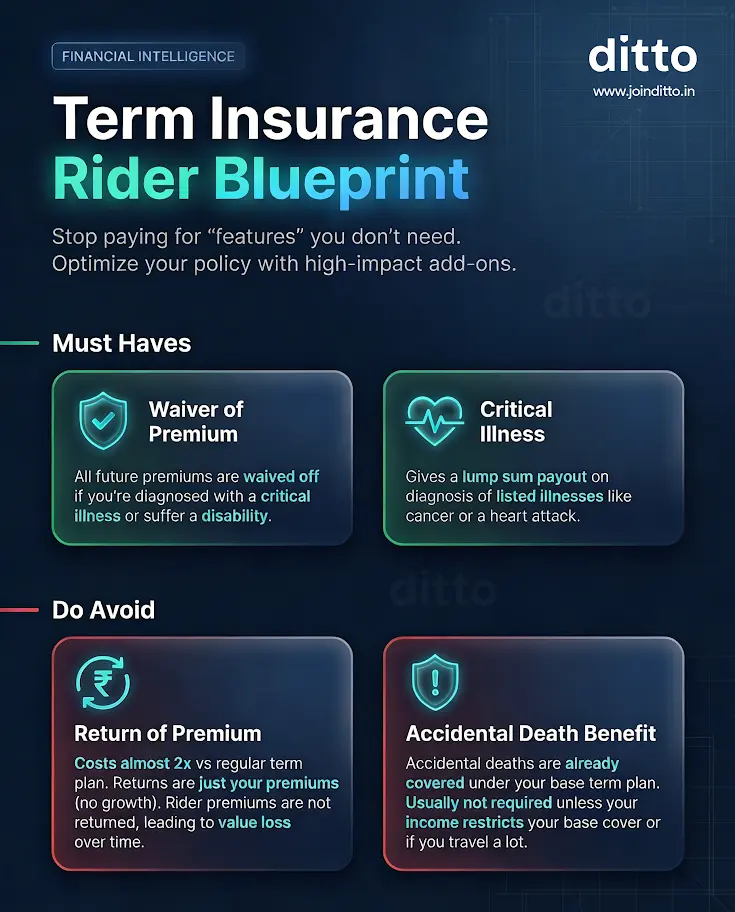
Riders can strengthen your protection, but they also increase premiums and have separate exclusions, definitions, and conditions. Add them only when they address a genuine financial risk. At Ditto, we recommend considering waiver of premium and critical illness riders based on your individual protection needs and policy terms.
Note: Not all riders are worth adding to your base term plan. Return of premium can cost almost 2 times a regular term plan, returns premiums without growth, and does not refund rider premiums. The accidental death benefit may be unnecessary because accidental death is already covered by the base term plan, though it can help where base cover is restricted, or travel is frequent.
Why Choose Ditto for Term Insurance?
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Choosing term insurance in Surat is not about finding the cheapest policy. Focus on adequate coverage, suitable tenure, relevant riders, insurer consistency, and features that match your family’s financial needs.
Compare the best term insurance plans across premiums, benefits, claim-related metrics, exclusions, and policy features. A well-researched choice can provide meaningful financial protection without paying for features you do not need.
Frequently Asked Questions
Last updated on: