

Overview
Are you confused between HDFC Life vs. Kotak Life?
HDFC Life features in our list of the best term insurance companies and is listed on the stock exchange. Kotak Life, on the other hand, is unlisted but has its legacy.
So, which insurer fits your needs better?
This guide compares Kotak Life Insurance vs. HDFC Life Insurance across premiums, features, riders, claim settlement, financial strength, and customer service.
Kotak Life Insurance vs. HDFC Life Insurance: Insurer Comparison
- Established: Kotak Life was established in 2001, while HDFC Life was established in 2000.
- IRDAI Registration: Kotak Life holds registration number 107, while HDFC Life holds registration number 101.
- Promoter: Kotak Life is a 100% subsidiary of Kotak Mahindra Bank, while HDFC Bank Limited is HDFC Life’s primary promoter.
- Network: Kotak Life operates with 382 branches, compared with 715 offices for HDFC Life.
- Agent Network: Kotak Life has 1,81,362 agents, while HDFC Life has 2,71,668 agents.
Talk to an expert
today and
find
the right
insurance for you.
Kotak Life Insurance vs. HDFC Life Insurance: Performance Metrics
Note: The figures in the table have been compiled from Kotak Life public disclosures, HDFC Life’s public disclosures, and IRDAI annual reports. You can explore Ditto Data Lab for more insurer metrics.
Kotak Life Insurance vs. HDFC Life Insurance: Plan Options and Sample Premiums
Plan Options
- Kotak Signature Term Plan: The Kotak Signature Term Plan offers a Special Exit Value that allows you to exit before maturity and receive a refund of eligible premiums, subject to policy terms. This feature is unavailable for policy terms below 40 years. It also offers an Insta Payout of ₹2 lakh within two working days after claim intimation, if the life assured dies after three consecutive policy years.
- Kotak e-Term Plan: Kotak e-Term Plan offers a Special Exit Benefit that refunds total premiums paid, including applicable underwriting extra premiums, subject to policy terms. It also provides a free medical check-up every five years from the fifth policy year and a Step-Up Option to increase coverage after milestones such as marriage. The feature is available only under the regular pay option and cannot be purchased through the online channel.
- HDFC Life Click 2 Protect Supreme Plus: Along with features like Special Exit Value and Instant Payout on Claim Intimation, Click 2 Protect Supreme Plus offers a terminal illness benefit of up to ₹2 crore before age 80 after confirmation by specialists. It also provides a Premium Break benefit after five policy years, allowing a one-year premium deferment while keeping the full cover active, subject to advance written notice.
- HDFC Life Click 2 Protect Elite Pro: With its enhanced features, Click 2 Protect Elite Pro is closer to feature-rich options such as Click 2 Protect Supreme Plus. It offers a Life Stage benefit that lets you increase your sum assured after key milestones, with a 50% increase for marriage or a home loan and 25% for each child, subject to limits.
Riders Offered
- Kotak Life: The insurer offers two key riders. The Kotak Permanent Disability Benefit Rider pays 120% of the rider sum assured over five years upon total and permanent disability. The Kotak Critical Illness Plus Benefit Rider covers 37 critical illnesses and provides a lump-sum payout upon diagnosis, subject to policy terms.
- HDFC Life: The insurer offers a critical illness rider covering 60 critical illnesses for up to 15 years, with coverage of up to ₹1.5 crore over the base cover. Click 2 Protect Supreme Plus also offers a waiver of premium rider that covers 60 critical illnesses and specified disabilities throughout the premium payment term.
Note: When evaluating riders for your term plan, we recommend choosing only those that address a genuine financial risk like waiver of premium and critical illness. Avoid adding riders solely because they are available, as they can increase your premium without providing meaningful additional protection.
Sample Premiums
This premium illustration assumes a healthy, salaried, non-smoking male from Delhi (PIN 110010) seeking ₹2 crore term cover until age 65. First-year discounts are excluded. Actual premiums may vary based on underwriting, policy choices, and other factors.
Note: Kotak Life offers relatively competitive premiums. However, its term plans may offer fewer advanced features than some competitors, which could matter to buyers seeking greater flexibility and more comprehensive benefits. You can use the Ditto term premium calculator for rough estimates of Click 2 Protect Supreme Plus.
Pros & Cons of Kotak Life Insurance
Pros of Kotak Life
- Strong Financial Metrics: Kotak Life has a healthy solvency ratio, indicating financial stability.
- Competitive Pricing: Kotak Life offers competitive premiums, and its complaint volume remains below the industry median.
Cons of Kotak Life
Limited Rider Ecosystem
Kotak Life offers fewer rider options than HDFC Life, which can limit flexibility for buyers seeking additional protection alongside their base term cover.
Higher Complaint Volume
Kotak Life records a higher complaint volume than HDFC Life in this comparison, which may indicate a relatively weaker customer experience on this metric.
Fewer Advanced Features
Kotak Life’s term plans lack some features available with HDFC Life, such as premium break and broader policy customization options.
Pros & Cons of HDFC Life Insurance
Pros of HDFC Life
- Higher Business Volume: HDFC Life reports a significantly higher annual business of around 3.6 times compared with Kotak Life’s ₹9,018.48 crore, reflecting its larger business scale.
- Higher Claim Settlement Ratio: HDFC Life has a higher CSR than Kotak Life, indicating stronger claim settlement performance.
- Broader Feature and Rider Ecosystem: HDFC Life offers a wider range of policy features and rider options, giving buyers more flexibility to customize their term insurance cover.
Cons of HDFC Life
- Lower Solvency Ratio: HDFC Life has a lower solvency ratio than Kotak Life, although it remains well above the IRDAI-mandated minimum of 1.5x.
- Higher Premiums: HDFC Life’s premiums can be higher than Kotak Life. However, the difference may reflect its wider feature set, rider options, and claim settlement performance.
Why Choose Ditto for Term Insurance?
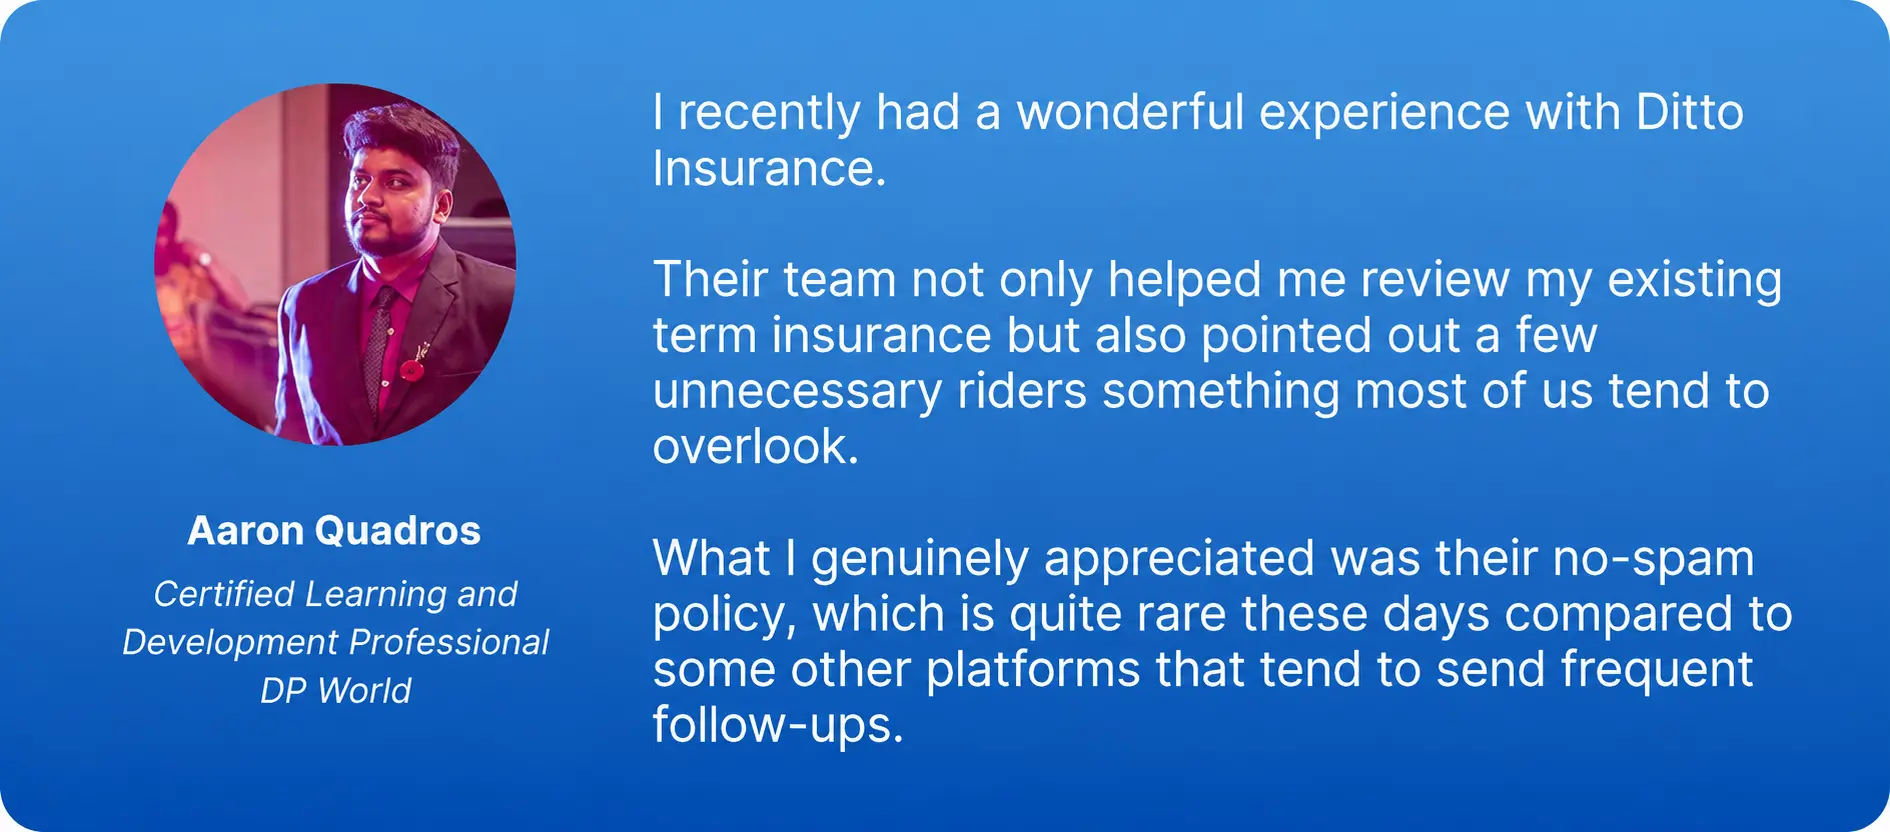
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Both HDFC Life and Kotak Life are credible insurers, but HDFC Life has an edge in claim settlement, features, rider options, and complaint metrics.
Choose:
- HDFC Life: If you prioritize stronger claim settlement performance, a broader feature set, more rider options, and a lower complaint ratio.
- Kotak Life: If you prioritize competitive premiums on a suitable plan and strong financial metrics.
At Ditto, HDFC Life Click 2 Protect Supreme Plus is our top pick and features among the best term insurance plans.
Frequently Asked Questions
Last updated on: