Term insurance is a pure form of life insurance that provides financial protection for a chosen period. If the life assured passes away during the policy term and the policy is active, the insurer pays the sum assured to the nominee.
How It Works
Choose Cover and Term: Select the sum assured and how long the cover lasts.
Underwriting: The insurer evaluates your age, income, health, habits, and job to finalize your premium and cover.
Pay Premiums: Pay monthly, quarterly, half-yearly, or yearly.
Claim: The nominee gets a lump sum, monthly income, or both.
Outliving the Term: The plan ends with no payout.
Key Features
Affordable: High cover at a low premium.
Optional Riders: Offers options like critical illness and waiver of premium for added protection.
Tax Benefits: Premiums qualify under Section 80C (now Section 123) in the old regime. The payout is tax-free under Section 10(10D) (now Section 11, Schedule II).
Term insurance is the simplest form of life cover, yet many buyers aren’t sure what they’re paying for or what their family would receive. That confusion can lead to too little cover, missed disclosures, and rejected claims. However, once you understand how term insurance works, choosing the right plan becomes much easier.
In this guide, we break down how term insurance pays out, who can buy a plan, the main types, and how premiums and claims work.
Term insurance is a life insurance contract that protects your family for a fixed duration, in exchange for a fixed premium. You can pay the premium monthly, quarterly, half-yearly, or yearly.
If the policyholder passes away during that period, the insurer pays the sum assured to the nominee. But if the policyholder outlives the policy period, the policy ends with no payout, unless you’ve opted for a return of premium plan, because term insurance is pure protection, not an investment.
Let’s understand how term insurance works with an example. At age 30, the policyholder buys ₹1 crore of cover till age 65 on HDFC Life Click 2 Protect Supreme Plus for about ₹12,093 a year:
If they pass away at 50, their family receives ₹1 crore, tax-free under Section 10(10D) (now Section 11, Schedule II).
If they live past 65, the policy ends. They have paid about ₹4.23 lakh in premiums for 35 years of protection.
Note: You can pay premiums for the full term (regular pay), for fewer years (limited pay), or just once (single pay). Under the old tax regime, premiums also qualify for a deduction of up to ₹1.5 lakh under Section 80C (now Section 123).
Available Payout Options
Lump Sum: The nominee gets the full sum assured at once. At Ditto, we recommend this option, as it gives the family full control over the money and lets the family use it how they want, for example, to clear any pending loans, invest the amount, etc.
Monthly Income: The payout comes in monthly installments, usually for 10, 20, or 30 years, to replace a regular salary.
Lump Sum Plus Monthly Income: Part of the payout comes at once, and the rest as monthly income installments.
Eligibility Criteria for Term Insurance
01
Age
Most plans allow entry from age 18 to 60 or 65, with cover usually lasting up to 85, and up to 99 or 100 (whole life) on some plans.
02
Income
Salaried graduates usually need an income of at least ₹2.5 lakh to ₹3 lakh a year, and self-employed graduates ₹4 lakh to ₹5 lakh (depending on your overall profile and the plan you're applying for). You'll need income proof such as recent payslips, bank statements, or Income Tax Returns (ITRs).
03
Education
Graduates qualify with all insurers. But if you've studied only up to Class 10 or 12, insurers may ask for a higher income, such as ₹10 lakh for Class 10 with HDFC Life.
04
Health
Most applicants undergo a physical medical test or a telemedical consultation, depending on age, cover, health history, and the insurer’s assessment.
05
Cover Amount
Most plans start at a minimum cover of ₹25 lakh to ₹50 lakh. The maximum depends on your eligibility, the plan, the insurer’s underwriting, and any life cover you already hold.
06
Policy Term
You choose how many years the cover lasts, within the plan’s maturity age. At Ditto, we recommend coverage to last until 60 to 70 years of age, as that is when you no longer have financial dependants and have already planned for retirement.
07
Occupation
High-risk jobs, such as mining or offshore work, may require an occupation questionnaire and can lead to a loading (higher premium) or a lower cover.
08
Residency
Resident Indians and Non-Resident Indians (NRIs) can apply, while Overseas Citizens of India (OCIs) can apply for select plans. Some insurers also don’t issue policies in certain restricted pincodes.
The sum assured rises by a fixed percentage each year or as defined, usually to keep up with inflation or growing responsibilities, generally at a higher premium.
Refunds your eligible premiums, minus any stated deductions, if you outlive the policy period. It costs about 60% to 100%, or sometimes even more, than a pure term plan.
Not recommended. Invest the difference instead in Public Provident Fund (PPF), National Pension System (NPS), mutual funds, or fixed deposits (FDs).
Talk to an expert today and find the right insurance for you.
How Are Term Insurance Premiums Calculated?
Age: The younger you are, the lower the premium, and it stays fixed for the whole period.
Gender: Women usually pay about 5% to 20% less than men because they have a higher life expectancy.
Smoking: Smokers can pay 60% to 100% more than non-smokers, due to lower life expectancy.
Health: Existing health conditions like diabetes or high blood pressure can lead to a loading charge (an extra premium).
Cover Amount and Policy Term: The more cover you buy and the longer it lasts, the higher your premium. But doubling your cover doesn’t double the premium, as insurers charge less per lakh on higher cover amounts.
Occupation and Location: Risky jobs can attract higher premiums, and some plans, such as HDFC Life Click 2 Protect Supreme Plus, are priced by pincode.
Riders: Optional add-ons increase your total premium outflow, so choose them carefully. At Ditto, we usually recommend a Critical Illness (CI) rider, which pays a lump sum if you’re diagnosed with a covered illness, and a Waiver of Premium (WOP) rider, which stops future premium payments in case of diagnosis of a critical illness or disability (as applicable), so your policy stays active.
Term Insurance Claim Process: A Step-by-Step Guide
1) Inform the Insurer: The nominee should inform the insurer of the death as soon as possible through its helpline, email, website, branch, or authorized distribution channel. Keep the policy number and basic death details ready.
2) Collect Documents: These include the death certificate, claim form, claimant’s ID and address proof, PAN or Form 60, and bank account details. For a death due to illness, the insurer may ask for medical records. For an accidental or unnatural death, it may also need the FIR, post-mortem report, or police investigation report.
3) Submit the Claim: Send the documents to the insurer, or to the authorized intermediary you bought the policy through. Keep the claim acknowledgment or reference number for tracking.
4) Verification: The insurer reviews the claim, policy details, and supporting documents. Insurers usually check natural deaths quickly, while accidental deaths and deaths in the first three years may need a detailed investigation.
5) Settlement: As per IRDAI rules, insurers must settle a claim within 15 days of receiving it, or within 45 days if an investigation is needed. The death benefit is paid to the eligible nominee.
If you bought your policy through Ditto, ourclaim support team helps your family through each step.
Why Choose Ditto for Term Insurance?
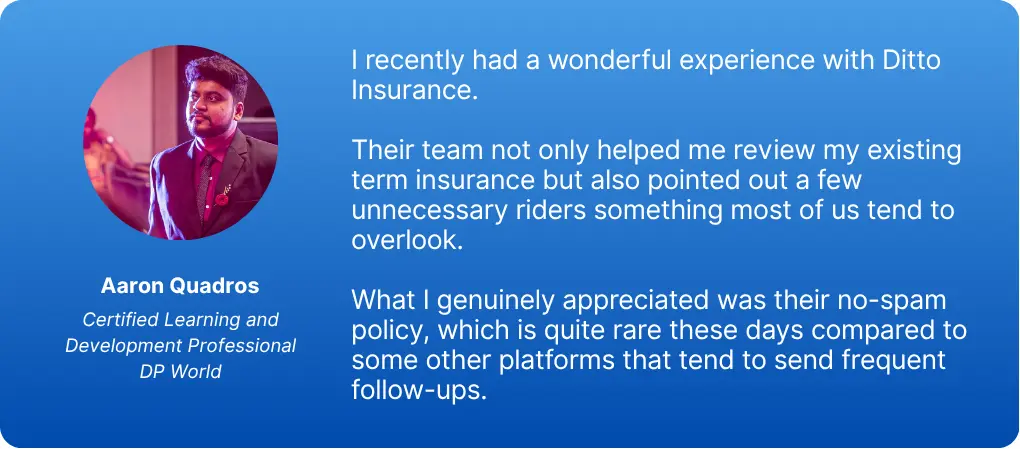
At Ditto, we’ve assisted over 12,00,000 people with choosing the right insurance policy. Why customers like Aaron below love us:
100% Free Consultation
No Spam. No Sales Pressure.
Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
Backed by Zerodha
Dedicated Claim Support Team
Compare Plans and Premiums with a Trusted Insurance Advisor
You can book a FREE consultation. Slots are running out, so make sure you book a call or chat on WhatsApp now!
Conclusion
If anyone depends on your income, whether a spouse, children, or parents, term insurance is one of the simplest ways to protect them. It gives your family a large payout for a small, fixed premium, and it can help them clear loans and keep up their way of life if something happens to you. But a policy only protects them if the details are right.
Too little cover leaves a shortfall, a short term can end before your children are independent, and a hidden illness or an outdated nominee can hold up the claim.
So before you buy, work out your family’s expenses and loans on Ditto’s cover calculator. Add riders like Critical Illness and Waiver of Premium only if you need the extra protection, and compare the insurer’s claim settlement ratio, complaint volume, and solvency along with the plan’s features. Then disclose honestly, and keep your nominee details up to date.
Frequently Asked Questions
What happens to my premiums if I survive the term insurance policy?
On a pure term plan, you don't get anything back if you outlive the policy term. The premiums you pay are for the protection your family had during those years, much like a health or car insurance premium. That’s how term life insurance works, and it’s what keeps the premium affordable. If you want your premiums back, a return of premium plan refunds them, minus rider premiums and without interest, but it costs about 60% to 100% or more. For most people, buying a pure term plan and investing the difference works out better over the long run.
Is a medical test mandatory for term insurance?
Not always, but most applicants go through one. Depending on your age, cover amount, and health history, the insurer may ask for a tele-medical call, a home visit, or a full physical medical test at a diagnostic center. Older applicants and those seeking higher cover usually need more detailed tests, such as blood sugar, kidney and liver function tests, and an ECG. The insurer usually arranges and pays for these tests. A medical test can also help, as the insurer then knows your health from the start.
What happens if I do not disclose a pre-existing medical condition when buying term insurance?
Your family’s claim could be rejected. Under Section 45 of the Insurance Act, an insurer can question a policy over a misstatement or non-disclosure within the first three years. If it finds that you hid a condition, such as diabetes or high blood pressure, it can reject the claim. After three years, you can’t question a policy on any ground except fraud. Disclosing a condition may raise your premium through a loading, but it keeps the policy valid when your family needs it most.
Can I buy two term insurance policies from different companies?
Yes. You can hold term plans from more than one insurer, and many people do so to increase cover as their income and responsibilities grow, or to split it across insurers. However, your total cover across all policies must stay within what you’re eligible for based on your income and profile. So disclose every existing life policy when you apply, since insurers count your total cover. If a claim arises, each insurer pays its own sum assured independently, as long as the policy is valid. Make sure your nominee knows about every policy.
Does term insurance cover death by suicide?
Yes, after the first 12 months, subject to the policy terms. If the life assured dies by suicide within 12 months of the risk start date or a revival, the full death benefit isn’t payable. However, under IRDAI rules for non-linked life insurance, the nominee gets at least the higher of 80% of the total premiums paid or the available surrender value, provided the policy is in force. Some insurers pay more. Check your policy’s suicide clause, especially if it has been revived or the cover has been increased.
What happens if I miss a term insurance premium payment?
You get a grace period to pay it: 15 days for monthly premiums and 30 days for other modes. Your cover continues during this time, but if a claim arises, the unpaid premium is deducted from the payout. If you don’t pay within the grace period, the policy lapses and your family loses the cover. You can usually revive a lapsed policy within five years by paying the overdue premiums, any late fees and interest, and completing medical checks if the insurer asks for them.
Can I change my nominee after buying term insurance?
Yes. You can change your nominee any time while the policy is active, as allowed under Section 39 of the Insurance Act, 1938. Most insurers let you do this online or by submitting a nomination change form with the new nominee’s details. You may want to update it after marriage, the birth of a child, or the death of a nominee. Make sure the nominee’s name and details match their government ID exactly, so your family doesn’t face delays when making a claim.
Can a term insurance claim be rejected, and what are the common reasons?
Yes. A claim may be rejected if the policy has lapsed, the death falls under an exclusion, or the insurer finds valid grounds such as fraud or a material misstatement within the period allowed under Section 45. Suicide in the first 12 months limits the payout rather than ruling it out. To avoid problems, disclose everything accurately, keep the policy active, and make sure your nominee knows the policy details. If a claim is rejected, ask the insurer for its written reasons, and challenge an unfair decision through its grievance process or the Insurance Ombudsman.