

Overview
ABSLI Poorna Suraksha Kawach (UIN: 109N138V04) is a term insurance plan that offers multiple coverage options, including increasing life cover, premium waivers, and premium refund features.
However, these options can affect the premium and overall suitability.
This Aditya Birla term insurance review covers the plan’s key benefits and limitations. It will help you assess whether Poorna Suraksha Kawach fits your protection needs and budget.
Eligibility Criteria for ABSLI Poorna Suraksha Kawach
Talk to an expert
today and
find
the right
insurance for you.
Plan Options
Under each of the listed options, if the life insured dies during the policy term, the nominee receives the sum assured applicable on the date of death.
Option 1: Level Cover
This option provides straightforward life insurance protection. If the life insured dies during the policy term, the nominee receives the sum assured as a lump sum, provided all premiums are paid.
It suits buyers who want a fixed level of life cover without premium refund features or changes to the sum assured over time.
Option 2: Return of Premium (ROP)
This option provides life cover throughout the policy term. If the life insured dies during this period, the nominee receives the sum assured as a lump sum, provided all premiums are paid.
If the life insured survives until the end of the policy term, the insurer refunds 100% of the base premiums paid. This feature comes at a much higher premium than basic term cover.
Option 3: Early Return of Premium (EROP)
EROP provides life cover during the policy term and lets you choose a retirement age when you first buy the policy. If the life insured dies during the term, the nominee receives the sum assured as a lump sum, subject to premium payment conditions.
If the life insured survives until the policy anniversary after the selected retirement age, the insurer pays back 100% of the base premiums paid. The chosen retirement age must be at least five years beyond the end of the premium payment term and below the maturity age. Life cover continues as usual post the retirement refund till the maturity age.
Option 4: Level Cover plus Waiver of Premium on CI/TPD
This option provides level life cover and an added safety net against 14 Critical Illnesses (CI) or Total and Permanent Disability (TPD). If the life insured dies during the policy term, the nominee receives the sum assured as a lump sum, provided all premiums are paid.
If the life insured is diagnosed with a specified critical illness or TPD during the premium payment term, future premiums are waived, and the policy continues. The life insured must be aged 65 or younger at the time of diagnosis.
Option 5: Increasing Cover
This option increases your life cover over time to help address changing financial responsibilities. If the life insured dies during the policy term, the nominee receives the sum assured applicable on the date of death, subject to policy conditions.
When you buy the policy, you can choose an annual increase of 5% or 10% of the original sum assured, calculated on a simple interest basis. You cannot change the selected escalation rate during the policy term.
Option 6: Sum Assured Reduction
This option reduces your life cover after a selected retirement age. You choose the retirement age and reduction factor when you buy the policy. The retirement age must be at least 10 years after the life insured’s age at policy inception and below the maturity age. You can't change either choice during the policy term.
Ditto’s Take: Choose between level cover and level cover with a premium waiver option based on your needs. Before deciding on the policy amount, you can use the Ditto cover calculator to estimate how much coverage your family may need.
Return of premium (ROP) and increasing cover options cost more. On the other hand, decreasing cover options may leave your family underinsured as financial responsibilities grow, so assess your long-term needs before choosing.
Key Features and Riders of ABSLI Poorna Suraksha Kawach
- Death Benefit: If the life insured dies during the policy term, the nominee receives the sum assured on death as a lump sum, as per the chosen variant.
- Survival Benefit (Plan Option 3): If the life insured survives until the policy anniversary after the selected retirement age, the insurer pays a survival benefit equal to the base premiums paid.
- Maturity Benefit (Plan Option 2): If the life insured survives until the end of the policy term, the insurer returns the base premiums.
- Terminal Illness Benefit: If the life insured receives a terminal illness diagnosis during the policy term before age 81, the insurer pays 50% of the applicable sum assured on death, up to ₹2 crore. Future premiums are waived. If the life insured later dies during the policy term, the death benefit reduces by the amount already paid.
- Accelerated Critical Illness (ACI) Benefit Option: If the life insured is diagnosed with any of the specified 42 critical illnesses for the first time during the ACI cover period, the insurer pays the ACI sum assured, subject to policy conditions. The cover ranges from ₹5 lakh to 50% of the base sum assured, capped at ₹50 lakh, in ₹5 lakh increments.
- One-Time Exit Value (OTEV): The policyholder can opt for a One-Time Exit Value equal to the base premiums paid, provided the policy is active and all due premiums are paid. No extra premium applies. This option is available after policy year 30, except during the final five policy years, and cannot be selected under Plan Options 2 or 3.
Note: The survival and maturity benefit amount excludes underwriting extra premiums, modal premium loadings, rider premiums, applicable taxes, and any extra premium charged for the ACI benefit.
Riders Offered
Accidental Death and Disability Rider
Pays 100% of the rider sum assured as a lump sum for accidental death or disability, subject to the rider’s terms and conditions.
Critical Illness Rider
Pays a lump sum if the life insured survives for 30 days after diagnosis of any of the four specified major critical illnesses.
Surgical Care Rider
Pays a lump sum if the life insured undergoes medically necessary surgery in India that requires hospitalization for at least 24 hours.
Hospital Care Rider
Provides a fixed daily cash benefit for eligible hospitalization lasting at least 24 hours for medically necessary treatment of an illness or injury, subject to the rider’s terms and conditions.
Accidental Death Benefit Rider Plus
Pays an additional lump sum equal to 100% of the rider sum assured for accidental death. It also refunds eligible rider premiums paid from the accident date until death, with interest.
Waiver of Premium Rider
Waives future premiums for the base policy and attached riders if the life insured is diagnosed with a specified critical illness or disability, subject to policy conditions.
Note: Riders are not available under Plan Option 6. For other eligible options, you can choose either the accidental death and disability rider or the accidental death benefit rider plus, but not both. Also, you can't combine the ACI option with the separate critical illness rider.
Adding every rider to your policy can increase costs without always providing meaningful value. At Ditto, we primarily recommend Waiver of Premium (WOP) and Critical Illness (CI) riders, as they can help maintain life cover and ease the financial burden of a serious illness or disability.
Sample Premiums by Age and Sum Assured
The sample illustrations are based on a non-smoking male residing in Delhi (pincode: 110010) opting for ₹1 crore sum assured with life cover until age 80. The figures for Poorna Suraksha Kawach are derived from the official brochure. You can also use the Ditto premium calculator for rough premium estimates of the rest of the 3 plans.
Note: The premiums shown are illustrative and may vary based on age, health, smoking status, underwriting assessment, and insurer terms.
Key Insights
- Choose a Suitable Coverage Period: Because premium data is limited, we used brochure illustrations for cover until age 80. At Ditto, we recommend cover until age 60–70, unless you have specific needs that require longer protection. By then, most financial liabilities and dependents’ needs may have reduced.
- Buying Early Locks in Low Premiums: Poorna Suraksha Kawach is slightly more expensive than some competing plans at younger ages. Buying term insurance in your 20s usually costs less than buying term insurance in your 30s, helping you lock in a lower premium.
- Compare Features Beyond Premiums: In the mid-40s, Poorna Suraksha Kawach has lower premiums than the three competing plans in this illustration. However, it lacks certain useful features, such as an instant claim payout option and health management services, which also matter when choosing a policy. Plans like Smart Term Plan Plus offer critical illness protection for up to 64 illnesses, while iProtect Smart Plus and Click 2 Protect Supreme Plus cover up to 60 illnesses each.
ABSLI: Performance Metrics
Note: The figures above reflect the insurer’s overall performance. They are sourced from Aditya Birla Sun Life’s public disclosures and IRDAI annual reports. For more insurer performance insights, visit the Ditto Data Lab.
Key Insight: The Aditya Birla Sun Life Insurance claim settlement ratio is lower than those of Axis Max Life and HDFC Life. For FY 2024–26, Axis Max Life recorded a CSR of 99.71%, while HDFC Life reported 99.66%.
Pros and Cons of ABSLI Poorna Suraksha Kawach
Pros of Poorna Suraksha Kawach
- One-Time Exit Value: OTEV lets eligible policyholders recover premiums paid without choosing an expensive return-of-premium option upfront.
- Increasing Life Cover: Option 5 raises the sum assured over time, helping policyholders address growing financial responsibilities without applying for additional life insurance. However, this option increases your premiums.
Note: We do not recommend Return of Premium (ROP) or increasing cover options. We also advise against exiting a term plan early, as the need for financial protection may be greatest during those years.
Cons of Poorna Suraksha Kawach
- Complex Plan Structure: Six plan options, multiple riders, and additional benefits make the policy harder to understand. Buyers must review the conditions carefully before choosing an option.
- Limitations of the ACI Benefit: The optional ACI benefit reduces the death cover, is capped at ₹50 lakh, and has a 90-day waiting period. If you choose limited pay, the ACI cover period is also restricted to the premium payment term.
- Limited Death Payout Flexibility: The standard death benefit is paid as a lump sum, which may not suit families that prefer regular income through installments.
- High Cost of Premium Refund Options: ROP options can cost 60% to 100% more than basic term cover. We do not recommend ROPs as only base premiums are returned with no interest earned.
- Potentially Lower Cover After Retirement: Option 6 reduces the sum assured after the selected retirement age. This could leave policyholders underinsured if their financial responsibilities remain high.
Why Choose Ditto for Term Insurance?
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
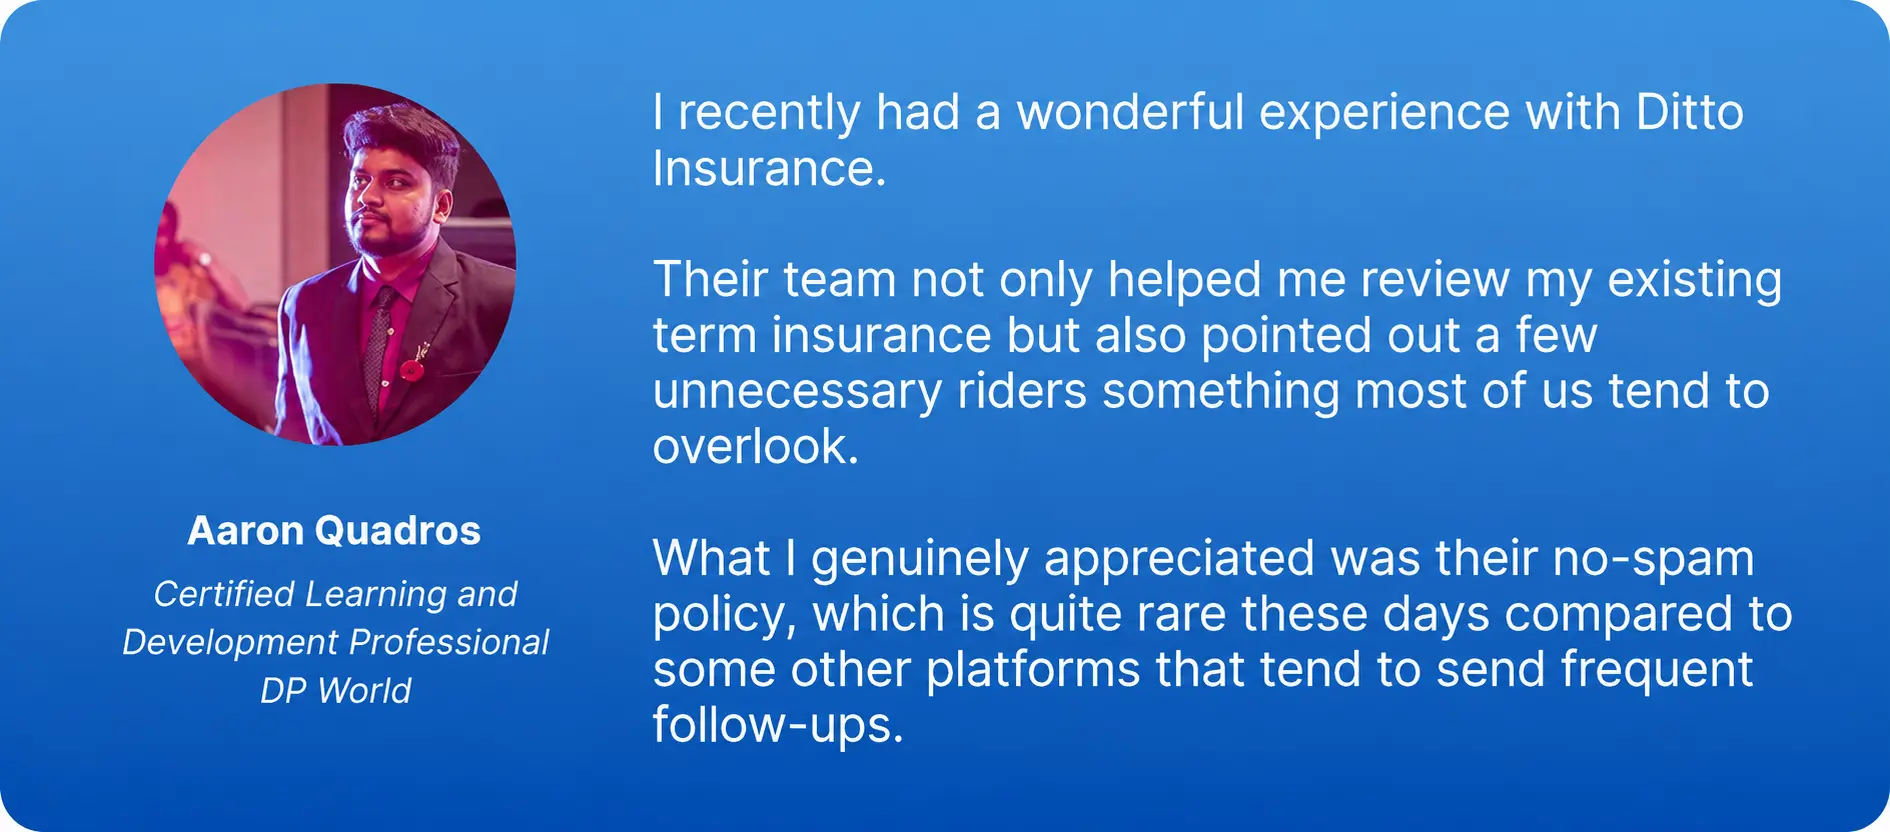
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Poorna Suraksha Kawach offers useful flexibility through retirement benefits, increasing cover, and premium waivers. However, its complex options and potentially higher premiums make it less suitable for buyers who want straightforward, affordable life protection.
ABSLI Poorna Suraksha Kawach is an older Aditya Birla term insurance plan. It is worth comparing with the insurer’s current flagship offerings like Super Term Plan, alongside other best term insurance plans before deciding.
Frequently Asked Questions
Last updated on: