

Overview
A term plan should offer clear protection without adding unnecessary complexity or cost. The ABSLI Life Shield Plan (UIN: 109N109V06) offers several cover structures and payout choices, but each option comes with different conditions.
Aditya Birla Sun Life Insurance offers this non-linked, non-participating individual term insurance plan with level, increasing, decreasing, and return of premium options. Here is a closer look at its features, benefits, limitations, and suitability.
ABSLI Life Shield Plan Options
1) Option 1: Level Term Assurance
Your chosen sum assured remains the same throughout the policy term. This option provides a fixed level of life cover without any increase or decrease during the policy period.
2) Option 2: Level Term Assurance with Waiver of Premium
This option offers the same fixed life cover as Option 1. However, if you are diagnosed with any of the 14 specified critical illnesses or Total and Permanent Disability (TPD), all future premiums are waived, and the policy continues.
3) Option 3: Increasing Term Assurance
You can increase your sum assured by 5% or 10% of the original sum assured each year. The increase follows a simple-rate calculation and helps your life cover grow over the policy term.
4) Option 4: Increasing Term Assurance with Waiver of Premium
This option combines increasing life cover with a premium waiver benefit. If you are diagnosed with a specified critical illness or TPD, all future premiums are waived, and the policy continues until the end of the term.
5) Option 5: Decreasing Term Assurance
This option is designed for people with loans or mortgages. The sum assured decreases according to a predefined schedule during the policy term, helping your life cover match your outstanding loan obligations.
6) Option 6: Decreasing Term Assurance with Waiver of Premium
This option offers decreasing life cover along with a premium waiver benefit. If you are diagnosed with a specified critical illness or TPD, the insurer waives all future premiums, while the policy continues until maturity.
7) Option 7: Return of Premium
Your chosen sum assured remains constant throughout the policy term. If you survive until the maturity date, the insurer returns the eligible base premiums paid, excluding applicable deductions as specified in the policy.
8) Option 8: Return of Premium with Waiver of Premium
This option combines the return of premium benefit with a premium waiver feature. If you are diagnosed with a specified critical illness or TPD, the insurer waives all future premiums, and the policy continues until the end of the term.
Talk to an expert
today and
find
the right
insurance for you.
Eligibility Criteria for ABSLI Life Shield Plan
Key Features and Riders of ABSLI Life Shield Plan
1) Death Benefit
If the life insured dies during the policy term, the nominee receives the applicable death benefit.
2) Death Payout Options
The policy offers three ways to receive the death benefit:
- Lump Sum: The entire eligible death benefit is paid at once.
- Lump Sum + Fixed Annual Income: 58% is paid upfront, while the remaining amount is paid in annual installments over 10 or 15 years.
- Lump Sum + Increasing Annual Income: 58% is paid upfront, and the remaining amount is paid annually, with payouts increasing by 5% on a simple basis.
3) Terminal Illness Benefit
If the life insured is diagnosed with a terminal illness during the policy term, 50% of the applicable sum assured on death is paid immediately, up to ₹2.5 crore. The insurer also waives all future premiums.
Note: If the insured later dies during the term, the death benefit is reduced by the amount already paid.
4) Waiver of Premium on Total and Permanent Disability
If the life insured suffers from a qualifying TPD during the policy term, all future premiums are waived. The death benefit remains unaffected. This feature is available only under Plan Options 2, 4, 6, and 8.
5) Waiver of Premium on Critical Illness
If the life insured is diagnosed with any of the 14 specified critical illnesses during the policy term, all future premiums are waived. The death benefit remains unchanged. This feature is available only under Plan Options 2, 4, 6, and 8.
6) Joint Life Protection
Joint Life Protection covers the primary insured and their spouse under one policy. The spouse receives life cover equal to 50% of the primary insured's applicable sum assured. It is available for cover of at least ₹50 lakh under Plan Options 1, 2, 3, and 4. You must select it at policy inception.
If the primary insured dies first, the spouse receives the primary insured's death benefit, and their own cover continues without further premiums. If the spouse dies first, the primary insured receives the spouse's death benefit and retains their own cover, subject to revised premiums.
7) Enhanced Life Stage Protection
This feature lets you increase your cover after important life events, such as marriage or childbirth. It is available under Plan Options 1 and 2 for eligible regular pay policies, provided the insured is aged 50 or below when exercising the option.
- Marriage: Increase cover by 50%, up to ₹50 lakh.
- Birth of First Child: Increase cover by 25%, up to ₹25 lakh.
- Birth of Second Child: Increase cover by 25%, up to ₹25 lakh.
8) Maturity Benefit
Most plan options do not offer a maturity benefit. However, if you select Return of Premium Plan Option 7 or 8, you receive the base premiums (underwriting extra premiums and rider premiums are excluded) paid at the end of the policy term. The policy terminates after this payout.
Note: The Waiver of Premium benefit is available under Plan Options 2, 4, 6, and 8. ABSLI waives future premiums if the life insured experiences the first qualifying critical illness or total and permanent disability, provided the policy remains in force, and the insured has not attained age 65.
Available Riders
Accidental Death and Disability Rider
Critical Illness Rider
Surgical Care Rider
Hospital Care Rider
Accidental Death Benefit Rider Plus
Sample Premiums by Age and Sum Insured
The following illustration shows sample annual premiums from the official brochure for a healthy, non-smoking individual aged 35, with an initial sum assured of ₹50 lakh, a 20-year policy term, and regular annual premium payments.
Key Insights
- We recommend Level Term Assurance and Level Term Assurance with Waiver of Premium as it provides a fixed, high sum assured at an affordable premium throughout the policy term.
- We do not recommend decreasing term options because dependencies and liabilities can be unpredictable. Consider increasing cover only if it suits your specific needs.
- Since the insurer does not actively market this plan, we have used a ₹50 lakh sum assured for the premium illustration. However, at Ditto, we believe a person's life is worth crores. You can use the Ditto cover calculator to estimate your coverage needs.
- At Ditto, we recommend riders such as critical illness to strengthen your term insurance coverage against specific financial risks.
ABSLI: Performance Metrics
Note: The figures are sourced from Aditya Birla Sun Life’s public disclosures and IRDAI annual reports. For more data on life insurers' track record, visit the Ditto Data Lab.
The ABSLI claim settlement ratio is slightly below the industry average and lower than those of peers such as HDFC Life and Axis Max Life for the same period. For the 3-year average FY 2024–26, Axis Max Life recorded a CSR of 99.71%, while HDFC Life reported 99.66%.
Pros and Cons of ABSLI Life Shield Plan
Pros of ABSLI Life Shield Plan
- Eight Plan Options: Offers level, increasing, and decreasing cover, with additional waiver of premium variants to suit different protection needs.
- Built-In Terminal Illness Benefit: Includes an accelerated terminal illness benefit that allows eligible policyholders to access part of their death benefit after a qualifying diagnosis.
- Flexible Cover and Payouts: Offers increasing cover at 5% or 10% simple rates, life-stage enhancements, and multiple death benefit payout choices.
Cons of ABSLI Life Shield Plan
- Return of Premium Variants Are Expensive: While ROP options generally cost 60%–100% more than pure term cover, ABSLI’s own illustrations show premiums exceeding 200% of comparable level-term options. You receive only eligible premiums back on survival, without any investment returns. We do not recommend paying this extra cost for a refund feature.
- Separate Policies Are Preferable for Spouses: Joint life cover limits the spouse's protection to 50% of the primary policyholder's cover. Separate term policies give each spouse independent coverage and greater flexibility.
- Increasing Cover Is Not Compounded: The annual increase is calculated on the original sum assured, so it does not compound.
- Several Benefits Have Conditions: Life-stage enhancements and waiver benefits apply only under specified eligibility rules. The eight options can also make comparisons and selection more complex.
- Limited Rider Availability: Riders are not available with the Joint Life Protection option or Decreasing Term Assurance (Plan Options 5 and 6).
Why Choose Ditto for Life Insurance?
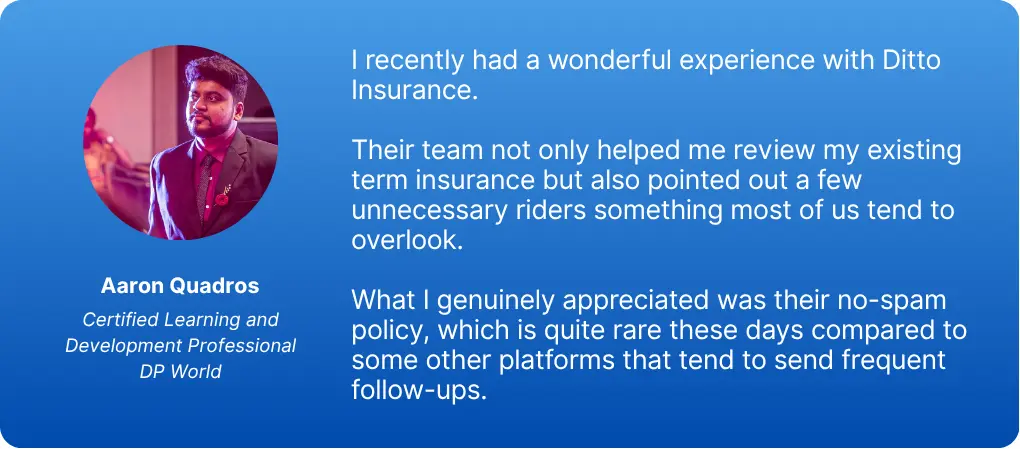
At Ditto, we’ve assisted over 12,00,000 people with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
You can book a FREE consultation. Slots are running out, so make sure you book a call or chat on WhatsApp now!
Conclusion
The insurer does not actively market the ABSLI Life Shield Plan. It also lacks some features available in newer products, such as a premium break option and an instant claim payout facility. Compare it with the best term insurance plans before deciding.
If you prefer Aditya Birla Sun Life Insurance, consider its current flagship product, Super Term Plan. It offers a more updated feature set, like an early exit value and health management services.
Frequently Asked Questions
Last updated on: