Term Insurance

Aviva Life Shield Premium Plan: Features & Premiums

Subhashish Banerjee

Written by Subhashish Banerjee

Insurance Writer

Gaurav Bhat

Reviewed by Gaurav Bhat

IRDAI-Certified Expert at Ditto

SP0738578124

Certified
Aviva Life Shield Premium Plan: Features & Premiums

Overview

Aviva Life Shield Premium Plan is a non-linked, non-participating term insurance product.

Key Features and Options

  • Sum Assured Options: Choose between flat (level), increasing, or decreasing life cover.
  • Base Cover Options: Protect-Lump Sum pays a lump sum to the nominee on the policyholder's death. It also provides 50% of the sum assured, up to ₹1 crore, upon diagnosis of a qualifying terminal illness. Protect-Income pays the death benefit to the nominee as a structured monthly income. Protect 50:50 combines a lump sum payout with a regular monthly income for 10 years.
  • Claim Payout Options: Choose to receive the death benefit as a lump sum, monthly income, or a combination.
  • Add-On Cover Options: Accidental death benefit and waiver of premium.

Eligibility Criteria

  • Entry Age: 18 years to 65 years.
  • Maximum Maturity Age: Up to 80 years.
  • Policy Term: Up to 62 years, depending on the entry age.

Aviva Life Shield Premium (UIN:122N136V01) is a non-linked, non-participating, pure-risk term plan from Aviva Life Insurance. It offers three sum assured structures and three death benefit payout options to suit different protection needs.

This guide covers the Aviva Life Shield Premium Plan's features, eligibility, death benefit payouts, and limitations to help you assess whether it suits your protection needs.

Eligibility Criteria for Aviva Life Shield Premium Plan

FeatureCriteria
Premium Payment Term (PPT)Single pay, limited pay (5 years, 10 years, or 60 years minus entry age), and regular pay
Minimum Entry Age18 years
Maximum Entry AgeUp to 65 years, depending on PPT
Minimum Sum Assured₹25 lakh offline and ₹50 lakh online
Maximum Sum Assured₹50 crore, subject to underwriting
Minimum Policy TermGenerally 10 years for flat (level)/decreasing cover and 26 years for increasing cover. However, under the 5 pay and 10 pay PPT options, the minimum policy terms are 10 years and 15 years, respectively.
Maximum Policy Term62 years
Maximum Maturity Age80 years
Premium FrequencyYearly, half-yearly, or monthly

Talk to an expert
today and find
the right
insurance for you.
Ditto Advisor

Key Features and Riders of Aviva Life Shield Premium Plan

    • Death Benefit: If the life insured passes away during the policy term, the insurer pays the sum assured in force on the date of death to the nominee, subject to the policy terms and conditions.
    • Flat Sum Assured: The life cover remains unchanged throughout the policy term. For example, if you buy a ₹1 crore flat term plan for 30 years, your nominee remains eligible for ₹1 crore throughout the term.
    • Increasing Sum Assured: The sum assured increases by 10% after every fifth policy anniversary, subject to a maximum increase of 50% over the original cover. This helps you increase your life cover as your financial responsibilities grow.
    • Decreasing Sum Assured: The sum assured reduces uniformly on every policy anniversary. Each year's reduction equals the original sum assured divided by the policy term, so the cover gradually decreases until the policy ends.
    • Protect-Lump Sum: This option provides life cover with an accelerated terminal illness benefit. If the insured is diagnosed with a terminal illness, 50% of the sum assured, up to ₹1 crore, is paid in advance, and all future premiums are waived. The remaining sum assured is paid to the nominee on death during the policy term. This benefit is available only with the Flat Sum Assured option.
    • Protect-Income: If the life insured dies during the policy term, the nominee receives 1% of the sum assured every month for 10 years, totaling 120 installments. The first installment is paid after the claim is approved. The remaining 119 installments are paid on subsequent monthly anniversaries of the insured's death.
    • Protect 50:50: This option combines a lump sum payout with a regular monthly income for 10 years. On the insured's death during the policy term, the nominee receives 50% of the sum assured as a lump sum. The remaining 50% is paid as monthly income, with each installment equal to 1% of that amount. For ₹1 crore of cover, this means ₹50 lakh upfront and ₹50,000 monthly for 120 months, totaling ₹1.10 crore in nominal payouts.

Riders Offered

    • Accidental Death Benefit: This add-on provides extra cover of up to ₹50 lakh per insured person, subject to the insurer's aggregate accident-cover limit. The accident must directly cause death within 180 days. This option is not available with decreasing sum assured.
    • Waiver of Premium for Accidental Total Permanent Disability: This add-on waives future premiums if the insured suffers a qualifying accidental total and permanent disability. It follows specific disability definitions and does not cover every loss of earning capacity. Cover ends at age 75 and is capped at ₹1 crore. The policy continues without further premium payments, subject to a maximum waiver cover of ₹1 crore per life.

Ditto’s Key Insights

    • Sum Assured Option: We do not recommend the decreasing sum assured option because your family's financial needs will most likely grow over time. You can choose adequate level cover or an increasing cover option (though increasing cover will cost more) based on your current liabilities and future responsibilities.
    • Rider Options: Along with Waiver of Premium (WOP), we recommend considering a Critical Illness (CI) rider for added financial support after a covered diagnosis. However, Aviva Life Shield Premium does not offer a critical illness rider.

Sample Premiums by Age and Sum Assured

The illustration is based on a healthy, salaried, non-smoking male residing in Delhi (pincode: 110010), seeking ₹2 crore in level term cover until age 65. First-year discounts are excluded. Premiums for Aviva Life are calculated using the official calculator. 

AgeAviva Life Shield Premium PlanHDFC Life Click 2 Protect Supreme PlusAxis Max Life Smart Term Plan PlusICICI Life iProtect Smart Plus
25₹17,228₹17,747₹17,222₹16,111
30₹26,162₹22,637₹20,656₹19,283
35₹33,650₹28,006₹26,154₹26,030
40₹44,018₹34,086₹34,380₹34,229

Note: Actual premiums may vary based on your personal details and the insurer's underwriting assessment. Use the Ditto premium calculator to get rough estimates for flagship plans from HDFC Life, Axis Max Life, and ICICI Life.

Based on these illustrations, Aviva Life Shield Premium costs more than several competing term plans, particularly for buyers aged 30 and above. Moreover, it lacks useful features such as premium breaks, which does not justify the higher premium.

Aviva Life: Performance Metrics

Metric (Average FY 2024-26)Aviva LifeIndustry Average
Claim Settlement Ratio99.08%99.00% (Mean)
Amount Settlement Ratio (Average FY 2023-25)98.82%94.83% (Mean)
Annual Business Volume (In Crore)₹331.13₹3,778.58 (Median)
Volume of Complaints (Per 10,000 Claims)82.8813.10 (Median)
Solvency Ratio1.88x2.00x (Median)
Annual Death Claims Paid (In Crore)₹106.14₹237.24 (Median) 

Note: The data is for the insurer as a whole and is not limited to Aviva term insurance products. Figures are sourced from Aviva Life public disclosures and IRDAI annual reports. Explore the Ditto Data Lab for more life insurer metrics. 

Aviva Life Insurance claim settlement ratio is above the industry mean but lower than established insurers like HDFC Life and Axis Max Life. For FY 2024-2026, the two insurers reported an average CSR of 99.66% and 99.71%, respectively.

Pros and Cons of Aviva Life Shield Premium Plan

Pros of Aviva Life Shield Premium Plan

    • Flexible Sum Assured: Choose flat, increasing, or decreasing cover based on your financial responsibilities and protection needs.
    • Multiple Payout Options: Select from three death benefit structures to suit your nominee's financial needs.
    • Built-In Terminal Illness Benefit: Get an accelerated payout for qualifying terminal illness under the eligible flat lump sum option.
Background Image

Cons of Aviva Life Shield Premium Plan

01

Limited Cover Increase in Increasing Cover Option

Cover increases only once every five years and is capped at 150% of the original sum assured.

02

Restricted Payout Choices

Monthly income and combination payouts are available only with the flat sum assured.

03

No Disability Income

The accidental disability benefit waives eligible future premiums but does not provide a separate income payout.

04

Limited Modern-Day Features

Besides the terminal illness benefit, the plan lacks features like health management benefits and life stage benefits. 

Why Choose Ditto for Term Insurance?

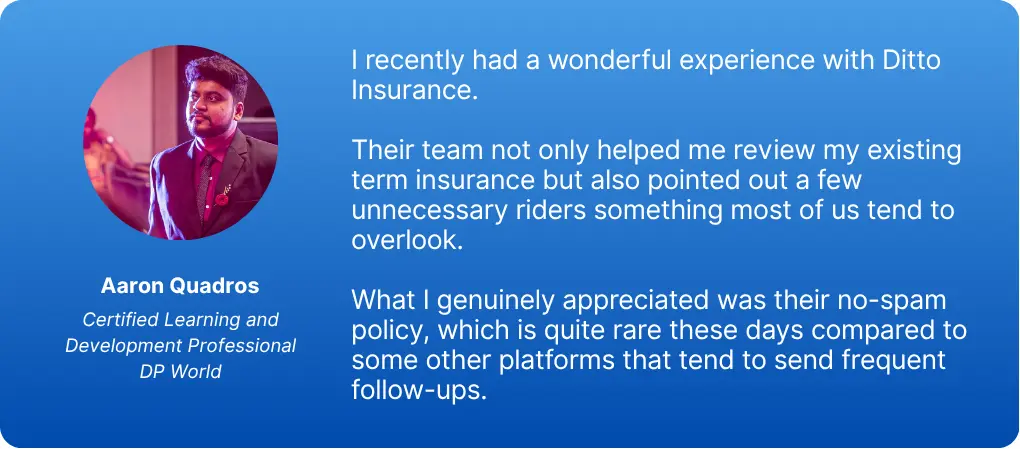
At Ditto, we’ve assisted over 12,00,000 people with choosing the right insurance policy. Why customers like Aaron below love us:
Aaron Quadros LinkedIn Testimonial
    • 100% Free Consultation
    • No Spam. No Sales Pressure.
    • Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
    • Backed by Zerodha
    • Dedicated Claim Support Team
    • Compare Plans and Premiums with a Trusted Insurance Advisor

You can book a FREE consultation. Slots are running out, so make sure you book a call or chat on WhatsApp now!

Conclusion

Aviva Life Shield Premium offers a reasonably basic traditional term insurance structure. However, it lacks modern features such as instant claim payouts and useful riders. 

From an insurer front, its annual business volume falls below our ₹5,000 crore benchmark, and the three-year average numbers indicate significant customer complaints. If you want broader policy features and stronger insurer credentials, explore the best term insurance plans.

Disclaimer: Aviva Life Shield Premium appears to be a legacy plan, and the insurer is not actively advertising the plan on its official website. Its fresh purchase status is unclear. Contact Aviva Life Insurance directly to confirm whether new applications are still accepted.

Frequently Asked Questions

Does the Aviva Life Shield Premium Plan offer a maturity benefit?

No. Aviva Life Shield Premium is a pure term insurance plan that does not offer any maturity benefit. If you survive the policy term, the policy ends without a payout. However, eligible single pay and limited pay policyholders may access the plan's early exit feature (surrender value), subject to the policy terms and conditions.

Can I get any money back if I surrender the Aviva Life Shield Premium Plan early?

The plan does not offer a conventional surrender value. However, eligible single pay and limited pay policyholders can receive an early-exit value after paying all premiums due. Aviva calculates this payout using a specified formula. Once paid, the policy terminates, and life cover ends. Regular pay policies are not eligible for this benefit.

What happens if I miss a premium payment under the Aviva Life Shield Premium Plan?

If you miss a premium payment, your policy continues through the applicable grace period (15 days for monthly premiums and 30 days for yearly or half-yearly premiums). If you do not pay within this period, the policy may lapse or lose benefits, depending on your premium payment option and policy terms. Check your policy document for revival conditions and applicable timelines.

Which premium payment option should I choose under the Aviva Life Shield Premium Plan: single, limited, or regular pay?

At Ditto, we generally recommend limited pay if your budget allows for higher annual premiums while you are young. It lets you finish premium payments within a shorter period, reducing the risk of policy lapse if your income drops later. It also frees up cash flow during retirement and may lower your total premium outgo compared to regular pay (ignoring time value of money). However, choose a payment term that suits your budget.

Does the Aviva Life Shield Premium Plan cover accidental death and permanent disability?

Yes. The base plan covers eligible death claims, including accidental death. You can also opt for an Accidental Death Benefit of up to ₹50 lakh for additional protection. The Waiver of Premium add-on waives future premiums if the insured suffers a qualifying accidental total and permanent disability. The disability must meet specified limb or vision-loss criteria and last at least 180 days. This add-on does not provide a separate disability payout.

Can I buy Aviva Life Shield Premium alongside another term insurance policy?

Yes. You can hold multiple term insurance policies from different insurers, subject to each insurer's underwriting assessment and financial eligibility checks. Disclose your existing life insurance cover accurately when applying for a new one. The insurer will assess your income, financial eligibility, and total proposed cover before deciding whether to issue the policy.

Can I change the nominee in my Aviva Life Shield Premium policy?

Yes. You can generally change the nominee at any time during the policy term by submitting a nomination change request to Aviva Life Insurance. You may need to provide the new nominee's details and complete the insurer's verification process. Check your policy documents or contact customer support for the required procedure.

Does Aviva Life Shield Premium offer a high sum assured rebate for cover of ₹50 lakh or more?

Yes. Aviva's official brochure offers high sum assured rebates on applicable tabular premium rates. These rebates start at ₹51 lakh for single pay and limited pay policies and ₹75 lakh for regular pay policies. The rebate amount depends on the selected cover and payment option. Check your premium illustration to confirm the applicable discount.

How can I make an Aviva Life Insurance policy payment online?

You can make your premium payment through Aviva Life Insurance's official website. Visit the payment section and select the online payment option. Enter your policy number and date of birth to retrieve your policy details. Verify the premium amount and complete the Aviva Life Insurance policy payment using an available payment method.

Last updated on: