

Overview
Is ₹75 lakh enough to protect your family if your income suddenly stops tomorrow? The answer depends on several factors, including your outstanding liabilities, household expenses, future financial goals, and existing savings.
That is why choosing the right term insurance cover is not just about picking a round number.
In this guide, we explain ₹75 lakh term insurance, including its eligibility criteria, premiums, available plans, and whether this cover is enough for your family's long-term financial needs.
Is ₹75 Lakh Term Insurance Enough Cover for Your Family?
A ₹75 lakh term plan may be a good starting point for younger earners with modest liabilities. It can also complement existing term insurance when your total protection need has increased, as long as the combined cover is financially justified.
However, ₹75 lakh may fall short for higher-income earners or families with large liabilities and long-term financial responsibilities. At Ditto, we recommend at least ₹1 crore term insurance based on individual profiles, as it can strike a balance between adequate life protection and affordable premiums.
Note: No single number suits everyone. Instead, calculate it yourself by considering your income, liabilities, future goals, inflation, and existing assets. You can also use the Ditto cover calculator tool to estimate the life cover your family may actually need.
What Is ₹75 Lakh Term Insurance?
A ₹75 lakh term insurance plan provides financial protection if the life assured dies during the policy term. The death benefit can help your family repay outstanding loans, replace lost income, and manage regular household expenses.
Talk to an expert
today and
find
the right
insurance for you.
₹75 Lakh Term Insurance Sample Premiums by Age and Term
Note: This illustration assumes a salaried male non-smoker in Delhi (pincode: 110010) seeking ₹75 lakh term cover until age 65, without first-year discounts. Premiums are indicative and vary based on age, policy term, riders, discounts, and underwriting. You can use Ditto’s term insurance calculator for rough estimates.
Eligibility and Income Proof Needed for ₹75 Lakh Cover
Term insurance eligibility for ₹75 lakh term insurance depends on factors such as:
Age
Most insurers allow term insurance purchases from age 18, with maximum entry ages often between 60 and 65. Coverage may continue until age 75, 85, or beyond, depending on the plan and variant. Check the insurer’s specific age limits before applying.
Existing Life Insurance Policies
If you already hold life insurance, the insurer will assess your total existing coverage before approving a new policy. This helps evaluate whether the proposed sum assured is reasonable for your income, financial responsibilities, and overall insurance needs.
Occupation
Your occupation can influence underwriting and premium rates. Stable, lower-risk roles may face standard assessments, while hazardous or high-risk professions, such as mining, aviation, or offshore work, may require additional disclosures, medical checks, or modified terms.
Education
Educational qualifications are not legally required to buy term insurance in India. However, insurers consider education when assessing eligibility for certain plans. Standard flagship plans may prefer graduates, while 10th- or 12th-pass applicants may face higher minimum income requirements.
Health
Your medical history, current health, and lifestyle influence underwriting. Conditions such as diabetes, hypertension, or obesity may lead to additional tests or premium loading.
Income
Annual income is a key factor in determining your eligibility and maximum sum assured. Insurers do not follow one universal income multiple. Insurers can use an income multiple, often around 20x to 35x annual income, which depends on factors like age and occupation.
Financial Profile
Insurers assess income stability, employment type, business continuity, and industry risk. Applicants with irregular income, inconsistent earnings, or limited financial documentation may face additional scrutiny or qualify for a lower coverage amount, depending on the insurer’s underwriting guidelines.
Insurers assess these factors together to determine whether the requested sum assured is financially justified.
For example, a 25-year-old graduate earning ₹5 lakh annually may qualify for a ₹75 lakh term cover with established insurers. However, someone earning ₹4 lakh or less may be limited to around ₹50 lakh.
That said, insurer-specific criteria can vary significantly. For example, Bajaj Life eTouch II may offer coverage of up to ₹75 lakh even for applicants earning around ₹3 lakh annually, subject to underwriting and eligibility conditions.
Income Proof
For income proof, salaried applicants need salary slips, Form 16, bank statements, or employer documents. Self-employed applicants may need Income Tax Returns (ITRs), financial statements, bank records, or other documents accepted by the insurer.
Some newer plans offering term insurance for self-employed individuals, such as Bajaj iSecure II and ICICI iProtect Super, may consider applicants without standard income documents such as ITRs.
Note: Eligibility and coverage depend on the insurer's underwriting criteria and the financial information provided.
Did You Know?
Best Term Plans Offering ₹75 Lakh Sum Assured
The plans discussed below are evaluated using Ditto’s detailed policy rating framework, which considers coverage, features, insurer strength, and long-term value rather than premium alone.
- Axis Max Life Smart Term Plan Plus: Offers a critical illness rider covering up to 64 illnesses for up to 30 years, along with accelerated terminal illness cover of up to ₹1 crore. Smart Term Plan Plus also includes a Special Exit Value, which can return eligible base premiums from the 25th policy year, subject to conditions.
- HDFC Life Click 2 Protect Supreme Plus: Provides up to ₹1.5 crore when diagnosed with one of the 60 critical illnesses, plus a disability waiver of premium option, along with Life Stage benefits that allow eligible policyholders to increase their cover after events such as marriage or childbirth. Click 2 Protect Supreme Plus also offers Smart Exit after 25 policy years, subject to a minimum 31-year policy term and other conditions.
- ICICI Prudential iProtect Smart Plus: Its Life Stage benefit allows eligible policyholders to increase their sum assured after events such as marriage, childbirth, adoption, or an eligible home loan. The additional cover can range from 25% to 100% of the original sum assured. iProtect Smart Plus also offers a Smart Exit option after 25 policy years, subject to eligibility.
- Bajaj Life eTouch II: Includes an accelerated terminal illness benefit of up to ₹2 crore. With Bajaj eTouch II, eligible nominees can also receive an instant payout of ₹2 lakh from the base sum assured within three working days of claim registration and submission of the required documents, subject to policy conditions.
- Aditya Birla Sun Life Super Term Plan: Offers accelerated terminal illness cover of up to ₹1 crore. Super Term Plan also provides an instant payout after three completed policy years, with ₹1 lakh for ₹50 lakh to ₹1 crore cover and ₹2 lakh above ₹1 crore, subject to conditions.
Riders Worth Adding to a ₹75 Lakh Term Insurance Policy
- Critical Illness (CI) Rider: This rider pays a lump sum if you are diagnosed with a specified critical illness, such as cancer or a major heart condition. It can help sole earners or those without sufficient emergency savings and health insurance cover treatment-related expenses.
- Waiver of Premium (WOP) Rider: This rider waives your future premiums if you suffer a covered critical illness or disability. It can help keep your term policy active when your income is affected. Premiums vary by age, policy terms, and insurer, so compare the actual cost before adding it.
Other Term Riders Offered
- Accidental Death Benefit (ADB) Rider: This rider provides an additional payout if death occurs due to a covered accident. It may be useful for people in high-risk occupations or who travel frequently. However, base term cover remains the primary protection and should not be reduced just to add ADB.
- Total Permanent Disability Rider: This rider provides a lump sum payout after a qualifying accident causes total and permanent disability. It can provide financial support when you can't continue working and may help manage household expenses, loans, and other long-term financial commitments.
Note: When evaluating riders in term insurance, at Ditto, we recommend waiver of premium and critical illness because they can protect you financially when a serious illness or disability affects your income and ability to pay future premiums.
₹75 Lakh vs. ₹1 Crore Term Insurance: Which Should You Choose?
The premium difference between ₹75 lakh and ₹1 crore term insurance can sometimes be modest, depending on your age, health, smoking status, insurer, and policy term. So, compare both quotes before deciding.
For example, a 25-year-old non-smoker male buying HDFC Life Click 2 Protect Supreme Plus till age 65 pays ₹8,532 for ₹75 lakh cover and ₹10,327 for ₹1 crore. The cover increases 1.33x, while the premium rises only 1.21x. The ₹1 crore policy offers a lower cost per ₹1 lakh of coverage. While the total premium is higher, the additional ₹25 lakh of coverage costs only ₹1,795 more annually.
Choose the higher cover only when your actual financial protection needs justify it, and the additional premium fits comfortably within your budget. The best term insurance plan is the one that gives your family maximum financial safety at a price you can easily afford.
Why Choose Ditto for Term Insurance?
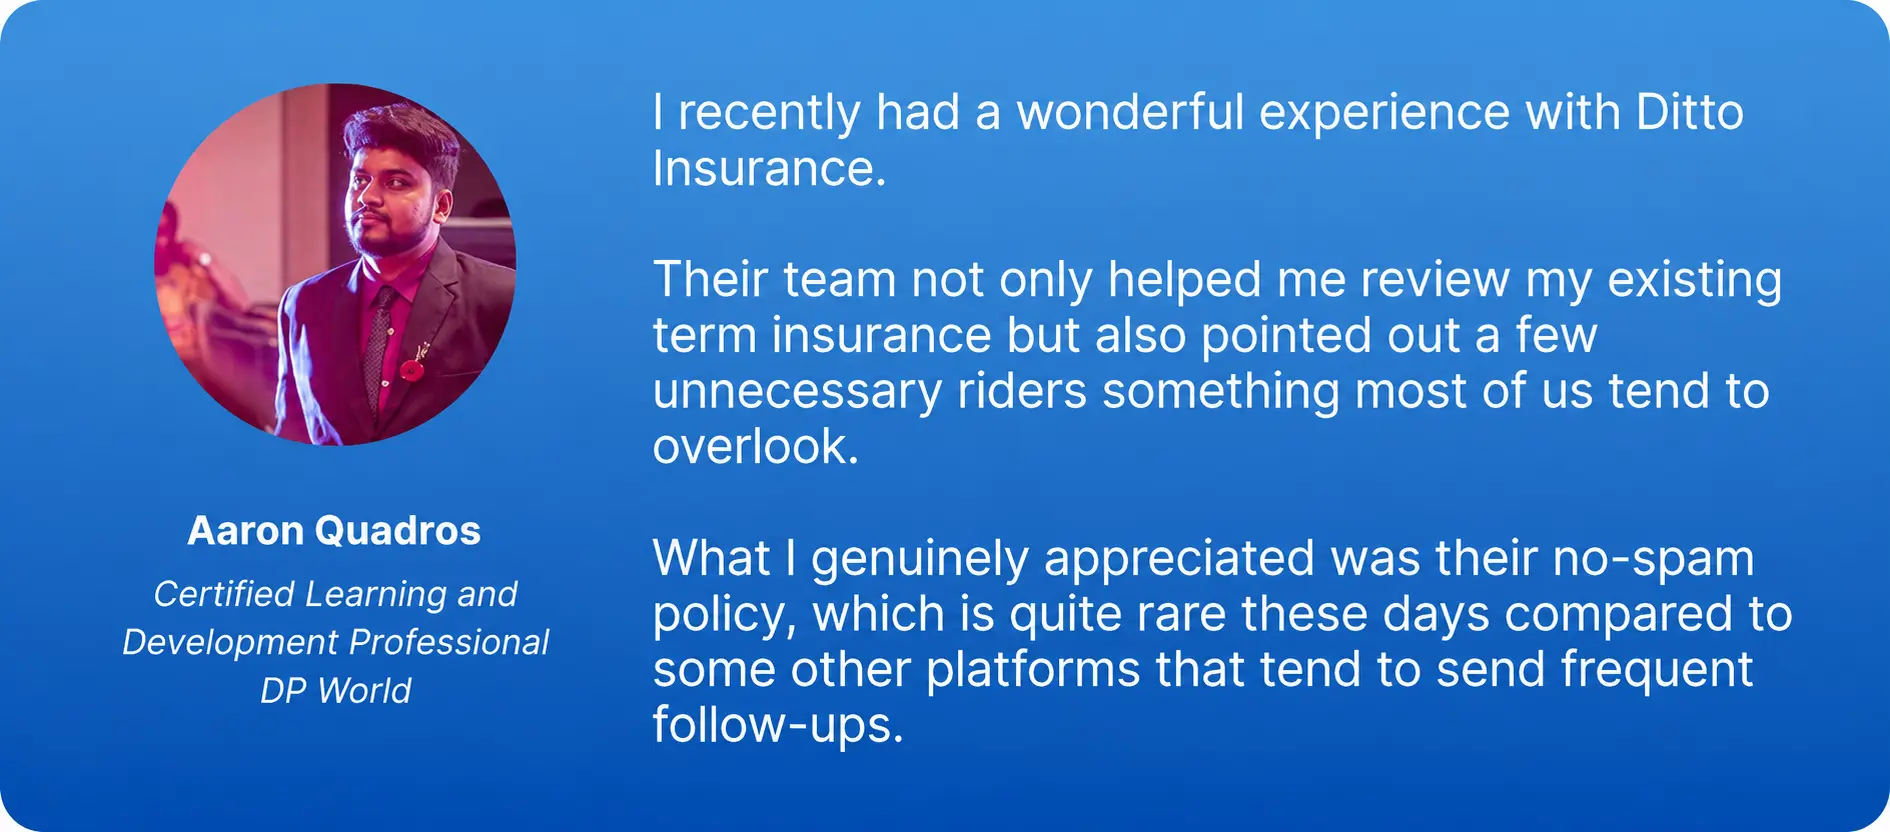
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
₹75 lakh term insurance can provide meaningful financial protection for your family, but the right cover depends on your income, liabilities, and future goals. Compare premiums, policy features, claim servicing, and insurer stability before choosing any term plan.
Don’t underinsure today hoping to increase your cover later. Start with cover that reflects your current financial responsibilities. Compare the best term insurance plans based on actual financial needs, not cover denominations alone.
Frequently Asked Questions
Last updated on: