Life Insurance

Term Insurance for Parents

Gargi Thakur

Written by Gargi Thakur

Editor

Gaurav Bhat

Reviewed by Gaurav Bhat

IRDAI-Certified Expert at Ditto

SP0738578124

Certified
Term Insurance for Parents

Overview

Term insurance for parents provides a lump-sum death benefit to nominees if the insured parent passes away during the policy term. It’s meant for parents who still earn and have dependents.

Benefits

  • Income: Replaces the parent’s earnings for daily expenses.
  • Child Education: Keeps funds available for a child’s studies.
  • Debt Protection: Helps the family repay any pending home or personal loans.

Eligibility

  • Age: Entry up to 60 or 65, depending on the plan, with cover up to age 85 or 99/100 (whole life). 
  • Income: Active income from a salary, business, or profession. Pension and Fixed Deposit (FD) interest usually don’t count. 
  • Health: Must pass the insurer’s medical tests and disclose all existing conditions. 

Top Plans

HDFC Life, Bajaj Life, and Aditya Birla Sun Life (entry up to 65). Axis Max Life and ICICI Life (entry up to 60).

Many parents in their 50s and 60s still earn an income, support their families, or have outstanding loans. If something happens to them, their dependents could face financial difficulties. This is where term insurance for parents in India can help, provided they meet the insurer's eligibility requirements.

In this guide, we'll discuss whether you can buy term insurance for your parents, the best available plans, eligibility criteria, sample premiums, how much coverage they may need, and common mistakes to avoid.

Can You Take Term Insurance for Your Parents?

Yes, if there's a clear financial reason. A term insurance plan replaces the income of the person it covers, so the insurer checks your parent's age, health, and income, not yours. 

Term cover makes sense for a parent who:

    • Still earns, and a spouse or child depends on that income.
    • Has a home or business loan the family must repay in their absence.
    • Is the only earner, which makes term insurance for single parents the strongest case.

Most parents over 60 don’t need a fresh term insurance plan. Once their income stops and loans are repaid, there’s little left for term cover to protect. If they're retired, debt-free, and have no dependents, senior citizen health insurance, an emergency fund, and income options like the Senior Citizens Savings Scheme (SCSS) or Fixed Deposits (FDs) work better.
Background Image

Eligibility Criteria and Age Limit

01

Age

Entry up to age 60 or 65, depending on the plan, with cover up to age 85, with some plans going up to age 99/100 (whole life).

02

Income

Active income from a salary, business, or profession. Pension income and FD interest are usually not accepted, so fully retired parents rarely qualify.

03

Minimum Income

This varies by plan, age, education, and occupation, as explained in our guide to income criteria for term insurance. For example, HDFC Life Click 2 Protect Supreme Plus requires ₹5 Lakh per annum for a salaried graduate over age 50.

Note: Eligibility is not the same as approval. After medical tests and underwriting, the insurer may add a premium loading (extra charge), reduce the cover/tenure offered, or reject the application if they feel the risks are higher.

Best Term Plans for Parents

PlanMax Entry AgeSum AssuredKey Features
Axis Max Life Smart Term Plan Plus60₹25 lakh to no limitTerminal illness payout of up to ₹1 crore, advance payout of up to ₹2 lakh at claim, and a Critical Illness (CI) rider for 64 illnesses (not available above age 55). 
HDFC Life Click 2 Protect Supreme Plus65₹50 lakh to no limitOption to pay the death benefit as lifetime income to parents aged 50+, a Waiver of Premium (WOP) rider for 60 illnesses and disabilities, and a one-year Premium Break. 
ICICI Life iProtect Smart Plus60₹50 lakh to no limitPartial payout of up to ₹3 lakh at claim, a one-year Premium Break, a CI rider for 60 illnesses, and a WOP rider for 15 CIs and accidental disability. 
Bajaj Life eTouch II65₹50 lakh to no limitTerminal illness payout of up to ₹2 crore, built-in WOP on accidental disability or terminal illness, a CI rider for 60 illnesses, and a parental care rider. 
Aditya Birla Sun Life Super Term Plan65₹25 lakh to no limitBuilt-in terminal illness benefit, CI cover for 42 illnesses (up to 50% of cover, capped at ₹50 lakh), a one-year premium deferral and an increasing cover option. 

For more plans that suit older buyers, read our guide to the best term insurance plans for senior citizens.

Sample Premium Illustration

The annual premiums shown below are for healthy, salaried, non-smoking profiles in Delhi (pincode: 110010) for a ₹2 crore cover, excluding first-year discounts. Actual premiums may vary based on medical history, discounts, and insurer underwriting. 

ProfileHDFC Life Click 2 Protect Supreme PlusAxis Max Life Smart Term Plan PlusICICI Life iProtect Smart PlusBajaj Life eTouch II
55, Male (covered till 70)₹1,07,870₹1,21,938₹1,09,406₹1,07,943
55, Female (covered till 70)₹91,689₹1,03,648₹92,995₹86,401
60, Male (covered till 75)₹1,58,909₹1,91,654₹1,60,361₹1,55,029
60, Female (covered till 75)₹1,35,072₹1,62,906₹1,36,307₹1,23,897
65, Male (covered till 80)₹2,84,585NA (max entry age 60)NA (max entry age 60)₹2,45,384
65, Female (covered till 80)₹2,41,897NA (max entry age 60)NA (max entry age 60)₹1,79,084

Key Takeaway: At 60, a woman pays ₹1,23,897 a year for Bajaj Life eTouch II, about 20% less than a man of the same age. Age makes an even bigger difference. As seen above, with HDFC Life, a man who buys at 60 pays ₹1,58,909 a year. If he waits until 65, he pays ₹2,84,585 a year, about 79% more for the same cover tenure.

You can check what your parents would pay with Ditto’s term insurance premium calculator.

Talk to an expert
today and find
the right
insurance for you.
Ditto Advisor

How Much Term Insurance Coverage Do Parents Need?

At Ditto, we use the expense and liability replacement method. We project the family's living expenses for as long as they depend on the parent's income, adjust for inflation, add loans and goals like a child's education, then subtract existing life cover.

For parents, start with the retirement corpus, then add what it can't cover.

Say a 62-year-old's spouse depends on their income. Here's how the cover adds up:

    • Living Expenses: ₹35,000 a month for 10 years is about ₹42 lakh, before inflation.
    • Add the Home Loan: ₹18 lakh, which the family would have to repay.
    • Subtract Savings: ₹12 lakh already set aside.
    • Cover Needed: ₹42 lakh + ₹18 lakh − ₹12 lakh = ₹48 lakh.

So, a ₹50 lakh plan fits better than a round ₹1 crore.

Note: We usually don't subtract savings, but it can make sense for seniors with a retirement corpus. Use Ditto's cover calculator for a rough estimate along with inflation adjustment.

Term Insurance for New Parents

If you’re a new parent aged 30 to 40, your own term cover matters if you’re trying to secure your children’s future. Since your child may depend on your income for 20 years or more, you can work out your cover the same way, with a few changes:

    • Include Your Child’s Goals: Add your child’s education and other big goals, like higher studies abroad, to your family’s living expenses and loans.
    • Pick the Right Policy Term: Choose cover that lasts at least until your youngest child is financially independent. At Ditto, we usually suggest cover until age 65 to 70.
    • Cover Both Parents: If you both earn, each of you needs a separate plan, sized to your own income and responsibilities.
    • Buy Early: A 35-year-old healthy, non-smoking, salaried male pays ₹26,154 a year for ₹2 crore cover with Axis Max Life Smart Term Plan Plus.

What Factors Affect Term Insurance Premiums for Parents?

    • Age: The older the parent, the higher the risk, so premiums rise sharply.
    • Health: Conditions like diabetes or high blood pressure can add a loading (extra premium) of around 25%–100%, sometimes even higher.
    • Smoking and Tobacco Use: Term insurance for senior citizen smokers is around 60% to 100% more. HDFC Life and Axis Max Life check tobacco use over the past two years, and Bajaj Life and ICICI Life over the past year.
    • Gender: Women pay about 15% less, depending on the insurer and entry age.
    • Policy Term: The longer the cover runs, the higher the premium.
    • Riders: Add-ons raise the premium, and their cover may end earlier than the base plan. At Ditto, we recommend CI and WOP riders. Rider options also shrink with age.

Documents Required to Buy Term Insurance Plans for Parents

Identity and Age Proof

Aadhaar card, PAN card, or passport.

Address Proof

Aadhaar card, passport, or a utility bill.

Income Proof

Income tax returns, computation of income, Form 16, salary slips, or bank statements.

Medical Records

Reports for any existing condition, along with insurer-ordered medicals.

Common Mistakes to Avoid When Buying Term Insurance for Your Parents

    • Hiding Pre-Existing Diseases: Declare every condition and medicine, even if controlled. Within the first three years of the policy, the insurer can reject a claim for non-disclosure under Section 45 of the Insurance Act. After 3 policy years, a claim can still be questioned in cases of proven fraud. 
    • Comparing Only Premiums: Beyond premiums, compare the insurer’s performance across key operational metrics, the plan’s entry age, and riders available at your parents' age.
    • Buying for Inheritance: Term insurance is built for protection, not wealth transfer. If your parent has no dependents or loans, spend on health cover instead.
    • Choosing ROP Plans: A Return-of-Premium (ROP) plan costs about 60% to 100% more than pure term insurance. It refunds only eligible premiums (as per the plan's terms and conditions), without interest. Moreover, by the time you get your money back, it has already lost its value due to inflation. At Ditto, we recommend opting for pure term insurance, with the premium difference invested in options like the Public Provident Fund (PPF) or FDs.
    • Ignoring Your Cover: If your parents depend on your income, buy term cover for yourself first. A 35-year-old man pays ₹26,154 a year for ₹2 crore cover with Axis Max Life Smart Term Plan Plus, about 86% less than a 60-year-old.

Why Choose Ditto for Term Insurance?

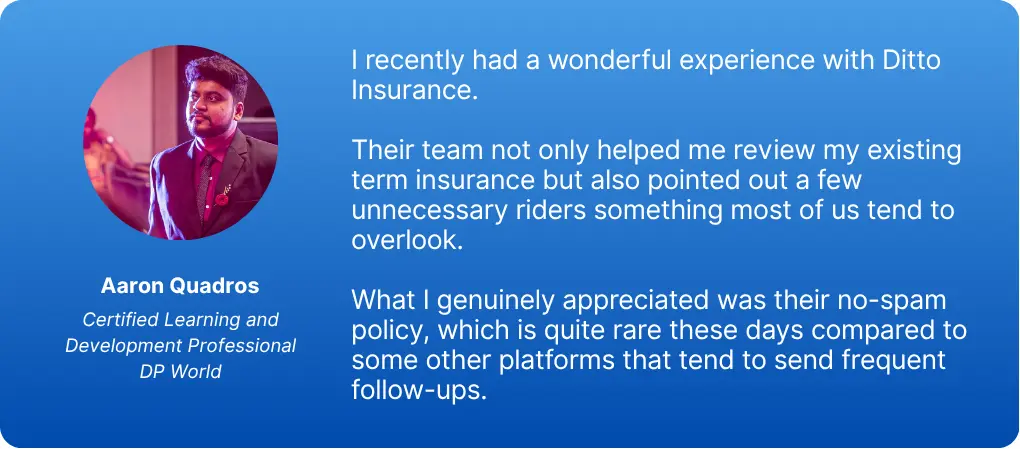
At Ditto, we’ve assisted over 12,00,000 people with choosing the right insurance policy:
Aaron Quadros LinkedIn Testimonial
    • 100% Free Consultation
    • No Spam. No Sales Pressure.
    • Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
    • Backed by Zerodha
    • Dedicated Claim Support Team
    • Compare Plans and Premiums with a Trusted Insurance Advisor

You can book a FREE consultation. Slots are running out, so make sure you book a call or chat on WhatsApp now!

Conclusion

Term life insurance for parents should be considered only when a parent still earns income someone depends on, or a loan needs repaying. For retired, debt-free parents, health insurance and savings do more. If your parent qualifies, disclose every health detail and match the cover to the family’s real need.

If your parents depend on you, the better step is often to secure adequate term cover for yourself and name them as your nominees. It costs far less at your age, and it protects them if something happens to you.

Check your parents’ age, income, and medical history against the criteria above.

Frequently Asked Questions

Is term insurance worth buying for parents who have no financial dependents?

Usually not. Term insurance pays the nominee only if the insured person dies during the policy term. If your parents are retired, debt-free, and no one relies on their income, the family loses no income when they pass away. At 60, a man pays over ₹1.5 lakh a year for ₹2 crore of cover, so the premiums rarely make sense here. A good health insurance policy, an emergency fund, and safe savings options like FDs usually protect retired parents better. Read more in our guide on life insurance for senior citizens.

Can I claim a tax deduction on the term insurance premiums paid for my parents?

No. Under the old tax regime, Section 80C (Section 123 under the Income-tax Act, 2025) allows a deduction of up to ₹1.5 lakh a year for premiums paid on your life, your spouse's life, or your children's lives. Parents aren’t included, so you can’t claim it even if you pay their premiums. If your parent pays the premium and files under the old regime, they can claim it. The death benefit is tax-free under Section 10(10D) (now Section 11, read with Schedule II, of the Income-tax Act, 2025) in both regimes.

Can I buy term insurance for mother if she is a homemaker?

Yes, through a homemaker (housewife) profile, since she has no income of her own. Her cover is based on her husband’s income or existing life cover. For example, HDFC Life Click 2 Protect Supreme Plus offers up to ₹1 crore if she’s a graduate aged up to 60 and her husband earns at least ₹5 lakh a year. Medical tests are mandatory. Read more on term insurance for housewives.

Is a return-of-premium term plan a good option for parents above 55 years of age?

Generally, no. Return of Premium plans cost about 60% to 100% more than pure term plans, sometimes even more. At 55 and above, base premiums are already high, so this extra cost hurts more. At maturity, the plan refunds only eligible base premiums, as per the plan’s terms and conditions, without any interest. A pure term plan works better, with the savings placed in options like FDs, PPF, or the National Pension System (NPS), depending on your parent’s goals.

How much term insurance coverage does a single parent need?

A single parent needs enough cover to keep the household running without their income. At Ditto, we add up the family’s living expenses until the youngest child becomes financially independent, adjust for inflation, and add outstanding loans and goals like the child’s education. We then subtract any existing life cover. For a single parent, choose a policy term that lasts at least until the youngest child can support themselves. A Ditto advisor can help you work out the exact amount.

Can I pay the premiums for my parents’ term insurance policy?

Yes. You can pay the premiums, but the policy is usually issued with your parent as the proposer and life insured, and the insurer checks their age, health, and income, not yours. At Ditto, we advise paying from your parent’s own bank account where possible. It keeps things simple and avoids unnecessary scrutiny of the source of funds. Pay on time to keep the policy active. You get a 15-day grace period for monthly premiums and 30 days for annual and other modes. You also can’t claim a tax deduction for premiums you pay for your parents.

Can I buy term insurance for my parents if they have a history of diabetes or hypertension?

Often, yes, if the condition is well controlled. Insurers usually ask for extra tests, such as HbA1c, liver and kidney function tests, an ECG, or cardiac tests like a TMT or 2D Echo. Depending on the results, they may add a loading of around 25% to 100% (sometimes higher) or reduce the cover or tenure. Severe or poorly controlled cases may be postponed or declined. Always disclose the full history, since hiding it can lead to claim rejection later.

What is the maximum age to buy term insurance for parents?

Most insurers allow a fresh term insurance plan for parents up to age 60 or 65. Among Ditto’s top-rated plans, HDFC Life Click 2 Protect Supreme Plus, Bajaj Life eTouch II and Aditya Birla Sun Life Super Term Plan accept entry up to 65. Axis Max Life Smart Term Plan Plus and ICICI Life iProtect Smart Plus stop at 60. Coverage can usually run up to age 85, with some extending it to 99 or 100 years. Your parent will also need active income and must pass the insurer’s medical tests.

Can senior citizens above 65 get term insurance?

Fresh term insurance for senior citizens above 65 is rarely available. Most retail plans stop entry at 60 or 65. Some group term plans accept entry up to 79 or 80, but your parent can only join through an employer, association, or lender. If your parent is over 65, focus on health insurance, an emergency fund, and savings options like the Senior Citizens Savings Scheme or FDs. Read more in our guide on term insurance for senior citizens above 65.

Last updated on: