Health Insurance

What is Comprehensive Health Insurance?

Ann Tresa Jais

Written by Ann Tresa Jais

Insurance Writer

Gaurav Bhat

Reviewed by Gaurav Bhat

IRDAI-Certified Expert at Ditto

SP0738578124

Certified
What is Comprehensive Health Insurance?

Overview

Comprehensive health insurance provides financial protection against hospitalization and related medical expenses. Coverage varies across policies, including benefits, exclusions, and waiting periods.

What It Typically Covers

  • Inpatient and Daycare Care: Covers eligible hospitalization expenses and medical procedures that do not require overnight admission.
  • Pre- and Post-Hospitalization: Covers eligible medical expenses incurred before admission and after discharge, within specified periods.
  • Extended and Specialized Benefits: May include ambulance services, domiciliary care, organ donor expenses, mental healthcare, and AYUSH treatments.
  • Optional Add-Ons: Depending on the insurer, additional benefits may include maternity coverage, Outpatient Department (OPD) consultations, and wellness benefits.

Key Things to Check Before Buying

  • Waiting Periods: Check restrictions applicable to pre-existing diseases, specified illnesses, and maternity coverage.
  • Sub-Limits and Co-Pays: Review room rent restrictions, disease-specific limits, and mandatory cost-sharing requirements.
  • Network and Cashless Access: Verify nearby network hospitals, cashless treatment availability, and the insurer's claim settlement procedures before purchasing a policy.

Many people assume health insurance is limited to emergency hospitalization and unexpected medical situations. While this is partly true, modern health insurance has evolved significantly to match today’s rising healthcare needs and costs. 

These plans go beyond inpatient hospitalization and cover consultations, diagnostics, and advanced treatments. Such policies are also called comprehensive health insurance plans because they provide broad medical protection for individuals and families. 

What Does Comprehensive Health Insurance Cover? 

What’s CoveredWhat’s Not Covered
Inpatient hospitalization (room, ICU, surgery, nursing)Investigation or evaluation-only admissions
Pre- and post-hospitalization expensesRest cure, rehabilitation, or respite care
Daycare procedures (e.g., dialysis, chemotherapy)Obesity or weight control treatments, unless medically necessary
Outpatient (OPD) consultations (inbuilt or optional)Gender change or related treatments
Emergency ambulance (road/air in premium plans)Cosmetic or plastic surgery (unless medically required)
Organ donor expensesInjuries from hazardous/adventure sports done as a professional
Modern treatments (robotic surgery, stem cell therapy)Treatments due to breaching the law
AYUSH treatments (Ayurveda, Homeopathy, etc.)Unproven or experimental treatments
Domiciliary (home-based) treatmentSterility and infertility treatments
Preventive health check-ups (often annual)Maternity expenses (unless specifically covered)
Mental illness hospitalization, as covered under law and policy terms Wellness or rejuvenation therapies
Consumables like gloves, syringes, masks, and bandages (may be covered depending on the plan, either included by default or offered as an add-on benefit)Dietary supplements unless prescribed
Cashless treatment at network hospitalsSubstance abuse or alcohol-related treatments

Note: Coverage can differ slightly between policies, but the table above outlines the most common inclusions and exclusions found in comprehensive health insurance plans. 

Key Benefits of Comprehensive Health Insurance 

1. Medical Coverage Across All Treatment Stages

Comprehensive plans cover the entire spectrum of care, from OPD consultations, diagnostics, and preventive health check-ups to daycare procedures and advanced treatments. Some plans even cover maternity and newborn expenses. This reduces gaps across diagnosis, treatment, and recovery. You're protected not just during emergencies but across diagnosis, treatment, and recovery, with fewer gaps in modern healthcare needs. This wider scope gives you stronger financial protection and greater peace of mind.

2. Covers High Medical Costs

Comprehensive plans offer high sum insured options, often exceeding ₹1 crore, with some even providing unlimited coverage in health insurance. This matters especially when you require expensive or advanced treatments like robotic surgery or stem cell therapy. Major illnesses such as cancer or cardiac conditions can cost tens of lakhs today, and these costs will only increase over time. A high sum insured protects you from large, unexpected medical bills and ensures access to quality care without financial strain. 

3. Cashless Hospitalization

With access to extensive hospital networks, these plans enable real-time approvals and direct settlement of bills. This is important because, in critical moments, you can avoid the stress of arranging funds or handling reimbursements and fully focus on recovery. Note that cashless hospitalization is a feature, not a guarantee. Out-of-pocket costs may still arise, so it is wise to keep an emergency fund ready for reimbursements or non-payable expenses.  

4. Financial Protection and Long-Term Wealth Security

Serious medical treatments can quickly drain years of savings. Comprehensive health insurance helps cover these expenses, so your savings, investments, and long-term financial plans stay protected. It can also help you avoid cashing out investments, taking high-interest loans, or depending on crowdfunding campaigns or government support during medical emergencies. 

5. Tax Benefits Under Section 80D of the Income Tax Act

Premiums qualify for deductions under Section 126 of the Income-tax Act, 2025 (previously Section 80D), with separate limits for self, family, and parents, improving overall tax efficiency. Under the old tax regime, you can claim up to ₹25,000 for self, spouse, and children, and up to ₹25,000 for parents. This increases to ₹50,000 if the insured members are senior citizens (60+), allowing a maximum deduction of ₹1,00,000 per year. Each deduction bracket includes a ₹5,000 sub-limit for preventive health check-ups. 

Best Comprehensive Health Insurance Plans in India

InsurerInsurer MetricsKey FeaturesDitto’s Score of the Insurer (Out of 5) 
HDFC ERGO Optima Secure+CSR: 97.61%, ICR: 81.62%, Network hospitals: 16,000+2x cover from day one, Infinity Benefit adds 100% of base cover every year without a cap, built-in consumables cover, unlimited restoration, and 60/180 days pre- and post-hospitalization coverage. 4.6
Care SupremeCSR: 95.45%, ICR: 58.68%, Network hospitals: 11,400+Unlimited restoration of 100% base cover for any illness, 50% annual bonus up to 100%, 60 days before and 180 days after hospitalization, plus optional bonus enhancements and consumables cover. 4.5
Aditya Birla Activ One MAXCSR: 96.25%, ICR: 68.16%, Network hospitals: 16,500+Unlimited restoration from the second claim, 100% annual bonus up to 500% regardless of claims, and wellness rewards offering up to 100% renewal premium discount. 4.4
Niva Bupa ReAssure 3.0 BlackCSR: 92.92%, ICR: 58.10%, Network hospitals: 10,000+ReAssure Forever offers unlimited restoration after the first paid claim, Booster+ carries unused cover up to 10x, eligible expenses are covered 60 days before and 180 days after hospitalization. 4.1
SBI Super Health Platinum InfiniteCSR: 95.94%, ICR: 81.32%; Network hospitals: 18,000+Unlimited restoration up to 200% per claim, 3x cover for 37 listed illnesses, built-in OPD and consumables cover, and 50% annual bonus up to 100%, regardless of claims. 4.1

Note: CSR stands for claim settlement ratio, ICR denotes incurred claims ratio, and SI denotes sum insured. 

For a better comparison across more plans and insurers, refer to our guide on the best health insurance plans in India. 

Talk to an expert
today and find
the right
insurance for you.
Ditto Advisor

Premium Comparison of Comprehensive Health Insurance Plans

ProfilesHDFC ERGO Optima Secure+Care SupremeAditya Birla Activ One MAX
(Individual Plan): Age 25₹13,459₹16,294₹11,671
(Family Floater, 2A): Ages (31, 32)₹21,128₹23,153₹18,743
(Family Floater, 2A 1C): Ages (35, 34, 5)₹26,017₹29,257₹24,700
(Family Floater, 2A): Ages (60, 59)₹72,648₹71,257₹52,875

Note: These are indicative premiums for a Delhi resident (PIN code: 110001) with a ₹15 lakh sum insured and no pre-existing diseases. Actual premiums may vary based on factors such as age, city of residence, medical history, selected add-ons, and applicable discounts.

How to Choose the Right Comprehensive Policy

    • Adequate Sum Insured: Choose a minimum cover of ₹15–25 lakh to ensure sufficient financial protection against major medical events and black swan health emergencies. India's medical inflation runs at roughly 14% annually, and because of this, a cover that feels adequate today may fall short in five years. Higher coverage becomes especially important for large families, individuals with pre-existing conditions, and residents of metropolitan cities, where the cost of quality healthcare is significantly higher.
    • No Co-Payment Clause: Check if the plan has no co-payment requirement. A co-pay means you bear a fixed percentage of the claim amount. Plans with zero co-payment ensure the insurer covers the full eligible expenses and help reduce out-of-pocket costs, especially during large hospital bills or premium treatments. 
    • No Room Rent Restrictions: Look for plans without room rent caps. Limits on room category can trigger proportionate deductions across the entire bill. Choosing a plan with no cap gives you flexibility to select any room without reducing overall claim eligibility.
    • No Disease-Specific Sub-Limits: Ensure the plan does not impose caps on treatments like cataract surgery or joint replacement. Plans without sub-limits allow you to claim the full treatment cost up to the sum insured.
    • Restoration Benefit: A good comprehensive plan should restore your sum insured if it gets exhausted during the policy year. This feature ensures continued financial protection for future claims within the same year. Check whether the restoration benefit is triggered even on partial exhaustion, and if it applies multiple times for both related and unrelated illnesses.  
    • Cumulative or No Claim Bonus (NCB): Check how the plan rewards claim-free years. A good NCB feature increases your sum insured over time without increasing premiums. Ideally, you should choose plans that continue offering a high bonus even after claims, so your coverage keeps pace with rising medical costs.

Why Choose Ditto for Health Insurance?

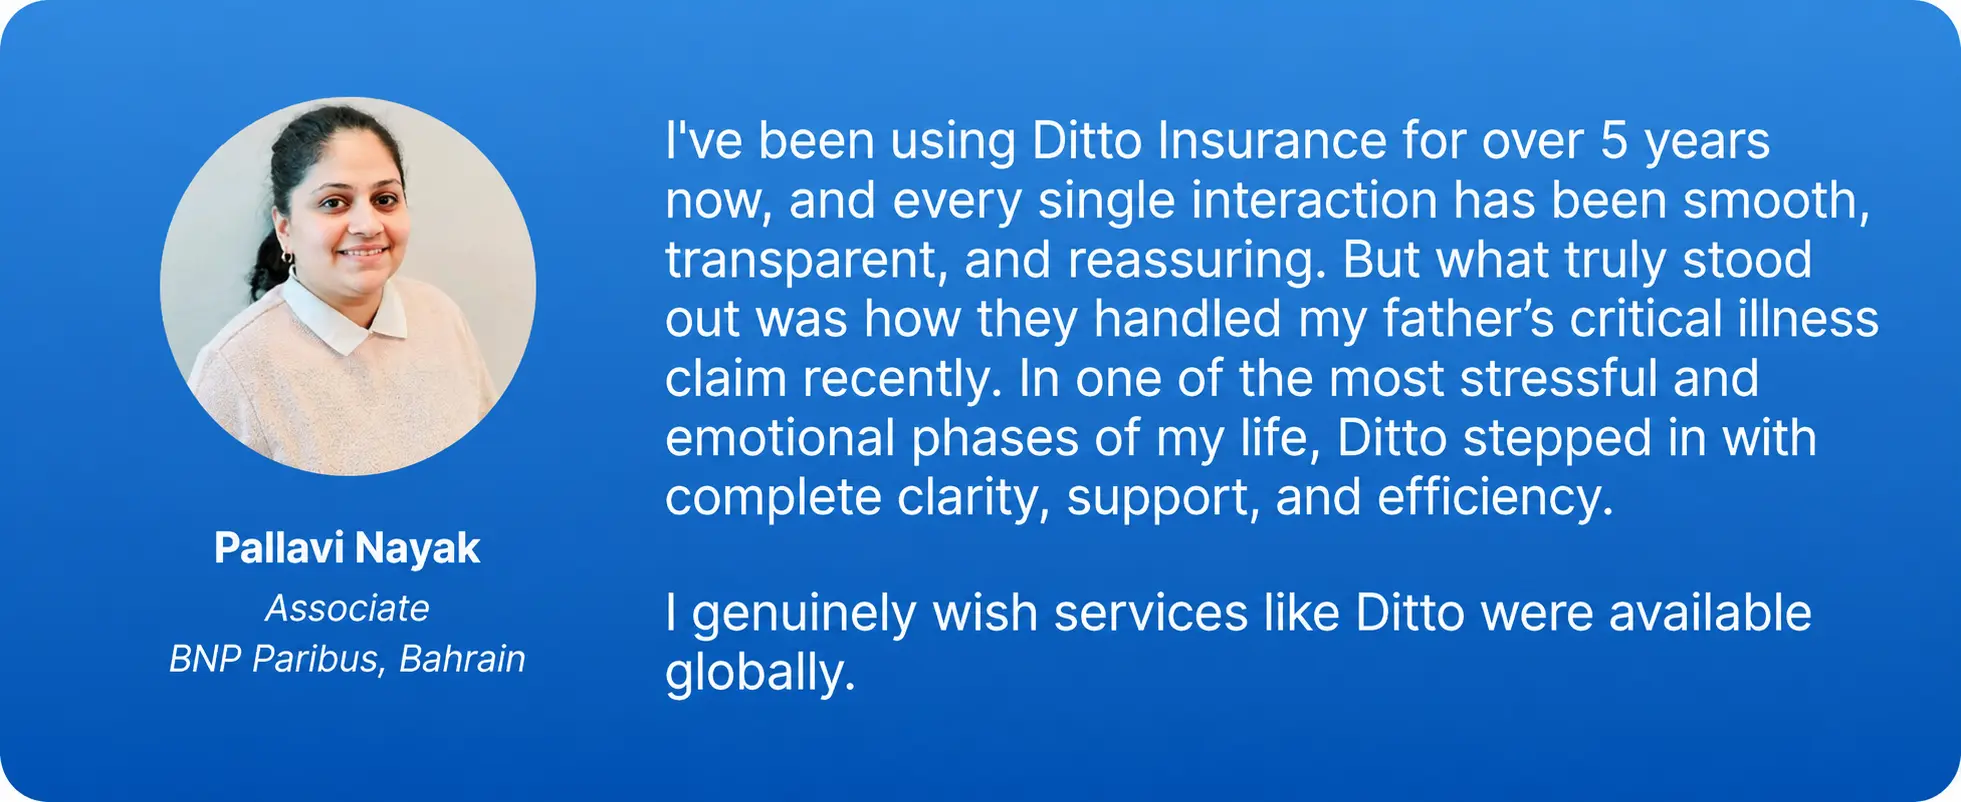
At Ditto, we’ve assisted over 12,00,000 customers choose the right insurance policy. Why customers like Pallavi love us:
Pallavi Nayak LinkedIn Customer Testimonial
    • 100% Free Consultation
    • No Spam. No Sales Pressure.
    • Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
    • Backed by Zerodha
    • Dedicated Claim Support Team
    • Compare Plans and Premiums with a Trusted Insurance Advisor

Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!

Conclusion

A strong comprehensive health insurance plan combines an adequate sum insured, broad modern coverage, and features that keep pace with rising medical costs. The best plans also avoid major restrictions such as co-payment clauses, room rent caps, and disease-wise sub-limits, while offering long-term value through restoration benefits and cumulative bonuses.

However, a health insurance plan’s value strongly depends on the insurer behind it. Factors such as claim settlement ratio, hospital network, complaint levels, and overall customer experience also play an equally important role in determining real-world reliability. If you are still unsure about the plan that best fits your needs, consider speaking with an IRDAI-certified advisor for personalized guidance.

Frequently Asked Questions

Is comprehensive health insurance a special type of plan?

No, comprehensive health insurance is not a formally defined category or a distinct type of policy. It is a term used to describe plans that offer broader and more flexible coverage compared to basic health insurance. These plans typically include features like no room rent limits, no co-payment, domiciliary treatment, restoration benefits, no claim bonus, and coverage across multiple stages of care. So, whether a plan is “comprehensive” depends on its features and structure rather than its name or classification.

Who should opt for a comprehensive health insurance plan?

Comprehensive health insurance is suitable for most individuals, but it is especially valuable for families, those with pre-existing conditions, and people living in metro cities where healthcare costs are higher. It is ideal for anyone seeking fewer restrictions, broader coverage, and stronger financial protection. These plans help reduce unexpected out-of-pocket expenses during treatment. If you are looking for long-term security and more flexibility in how you access healthcare, a comprehensive plan can provide both financial stability and greater peace of mind. 

How much sum insured should I opt for?

Choosing the right sum insured depends on your age, city, family size, and medical history. As a general rule, we recommend a cover of ₹15–25 lakh due to rising healthcare costs and medical inflation. For families or those living in metro cities, opting for a higher cover may be more suitable. It’s also important to consider future needs and choose a plan that allows your coverage to grow through bonuses or restoration benefits. This ensures your protection remains adequate over time. 

Does a comprehensive health insurance plan cover everything?

No, even comprehensive health insurance plans do not cover everything. While they include a wide range of medical expenses, there are still certain limitations. Most plans have waiting periods for pre-existing diseases and specific treatments. Some expenses, such as OPD consultations and non-payable items, may be excluded unless covered through add-ons. Not every plan includes pregnancy and newborn expenses, though plans like the Star Health Insurance Comprehensive plan do include maternity as a base benefit. It is important to read the policy terms carefully to understand what is included, what is excluded, and any conditions that may apply.

Which features matter most when choosing a comprehensive health insurance plan?

Focus on key non-negotiables such as no room rent limits, no co-payment, and no disease-wise sub-limits, as these directly impact claim payouts. Look for features like restoration benefits, consumables cover, and a strong no-claim bonus to enhance coverage over time. Beyond policy features, evaluate the insurer’s performance. Check claim settlement ratio vs incurred claims ratio, hospital network size, complaint levels, and overall customer experience. Together, these factors determine how reliable and useful the plan will be when you actually need it. 

What is consumables cover in comprehensive health insurance?

Consumables cover refers to coverage for disposable medical items used during treatment, such as gloves, masks, syringes, bandages, and PPE kits. These expenses are often excluded from standard health insurance policies, which can increase out-of-pocket costs during hospitalization by 5–15% of the total bill. Many comprehensive plans now include consumables cover either built-in or through add-ons. For instance, HDFC ERGO Optima Secure, Aditya Birla Activ One MAX, and SBI Super Health Platinum Infinite offer in-built consumables coverage, helping reduce non-payable expenses and making claims financially comprehensive.  

What are the mandatory waiting periods in comprehensive health insurance plans?

Most comprehensive plans carry three standard waiting periods. An initial waiting period of 30 days applies to all illnesses except accidents. A pre-existing disease (PED) waiting period covers conditions you had before buying the policy. IRDAI rules allow insurers to set this up to 36 months. A specific illness waiting period of up to 36 months applies to listed conditions like hernia, cataracts, and joint replacement. Some plans let you reduce the PED waiting period through a paid add-on. Besides that, maternity coverage usually comes with a waiting period ranging from 9 months to 4 years, depending on the insurer and plan. 

What affects the premium of a comprehensive health insurance plan?

Premiums are mainly based on the risk the insurer takes. Key personal factors include age, medical history, lifestyle habits like smoking, and occupation. Policy-related factors also play a major role; a higher sum insured means higher premiums (but not proportionately higher), while family floater plans usually cost more than individual plans. Your city of residence can impact pricing due to healthcare costs. Additionally, choosing add-ons such as maternity cover, OPD benefits, or critical illness riders will increase the overall premium. External factors such as medical inflation and insurer profitability also influence premiums.

What are the common exclusions in comprehensive health insurance?

Common exclusions in comprehensive health insurance include cosmetic or aesthetic procedures, infertility and fertility-related treatments, and injuries caused by self-harm. Treatments related to substance or alcohol abuse are also not covered. Other exclusions include refractive error correction below specified limits, experimental or unproven treatments, and non-medical expenses like vitamins or dietary supplements. Injuries from hazardous or adventure sports done as a professional are also excluded in many plans. Additionally, treatments arising from illegal activities or war-like situations are typically not covered. 

Last updated on: