For a family of 5, the recommended health insurance cover under a family floater plan would be ₹15 lakh to ₹25 lakh or more. But the right sum insured depends on the family's age, health needs, location, and budget.
Key Recommendations:
Top Plans: Compare HDFC ERGO Optima Secure+, Niva Bupa ReAssure 3.0 Black, Aditya Birla Activ One MAX, and SBI Super Health Platinum Infinite.
Policy Structure: A family floater can be cost-effective for a couple with dependent children. If you're covering senior parents, consider separate individual policies or a dedicated senior citizen floater to keep their premiums and claims separate.
Tax Benefits: Under Section 80D (now 126) of the old tax regime of the Income Tax Act, eligible policyholders can claim deductions of up to ₹25,000 (₹50,000 if senior) for self, spouse, and dependent children, with an additional ₹25,000 or ₹50,000 for parents, depending on their age, subject to applicable conditions.
Finding health insurance for family of 5 can be challenging because a household of 5 could mean a couple with three children or a family that also includes dependent parents. These combinations have different coverage needs, and not every insurer allows the same member combinations under one policy.
The right choice also depends on your required sum insured and budget. In this guide, we'll compare the best health insurance plans for a family of 5, their premiums, how much coverage you need, and the factors to consider before choosing a policy.
Not sure which health insurance plan is right for your family of 5? Book a free call or chat on WhatsApp with a Ditto advisor to find out.
Best Health Insurance Plans for Family of 5
When choosing a health insurance plan for a family of 5, first, check how many members the plan allows and which relatives you can include. Not all family floater plans accommodate 5 members or allow three children under a single policy.
Your family's composition can vary. For example, a 5-member household could include:
A Couple With Children: Self + spouse + 3 dependent children.
These are just two possible combinations. The right plan will depend on who you want to cover and the insurer's eligibility rules.
At Ditto, we shortlist the best health insurance plans using our insurer and policy rating framework, which evaluates coverage benefits, policy restrictions, insurer performance, hospital networks, and premium value. Here's how some of India's top health insurance plans accommodate these family structures:
HDFC ERGO Optima Secure and Optima Secure+ policies offer more family members than several other floater plans, allowing up to 4 adults + 6 children. They also offer 2x Secure Benefit, no room rent limits, and broad relationship eligibility, making them suitable for larger families.
Niva Bupa ReAssure 3.0 Black permits up to 2 adults + 4 children, with a maximum of 6 members (and provisions for up to 5 children). This makes it suitable for nuclear families with three children. Key features include unlimited automatic restoration of coverage and a premium lock feature until the first claim.
Aditya Birla Activ One MAX and Yuva allow up to 2 adults + 4 children. Activ One MAX offers a paid Chronic Care benefit for certain listed medical conditions, subject to the selected configuration. Activ Yuva has a standard 2-year Pre-Existing Disease (PED) waiting period, with an option to reduce it to 1 year.
Care Supreme allows up to 2 adults and 2 children under its family-floater structure. A couple with 3 dependent children therefore cannot cover all 5 members under this particular floater. They can instead compare a different 5-member family floater or split this into 2 floaters: 1 adult and 1 child, and 1 adult and 2 children.
SBI Super Health Platinum Infinite is designed to accommodate larger households. This plan permits 4 adults with no specified limit on the number of children. This makes it a good option for multi-generational families who want to cover extended family members under one policy.
For a more detailed comparison of these policies, their features, and other options, go through our guide to the best health insurance plans in India.
How Much Health Insurance Cover Does a Family of 5 Need?
At Ditto, we recommend a minimum health insurance cover of ₹15 lakh as a starting point. However, a family of 5 may need higher coverage because more members share the available sum insured, increasing the possibility of multiple hospitalizations in a policy year.
You should also account for medical inflation, which is estimated at around 12% to 14% annually in India. Medical inflation can make today's sum insured insufficient to cover rising hospitalization and treatment costs in the coming years.
For a family of 5, a cover of ₹20 lakh to ₹25 lakh can be a reasonable target, particularly if you prefer treatment at large private hospitals or have older family members. The actual requirement depends on your location, family members' ages, medical histories, and healthcare preferences.
Family Floater vs. Individual Health Insurance for a Family of 5
Family Floater Plans
In a traditional family floater plan, all 5 members share a single pooled sum insured (for example, ₹30 lakh). If one member incurs medical expenses worth ₹20 lakh, only ₹10 lakh remains for the other four members collectively for the rest of the policy year.
Family floaters are cost-effective and easier to manage for young nuclear families. However, a large claim by one member can reduce the coverage available to everyone else. Features such as automatic restoration can help restore the available coverage, making it possible to file subsequent eligible claims during the same policy year, subject to the policy's terms.
Multi-Individual Plans
If you want to cover 5 family members under one policy without making them share a common sum insured, consider a multi-individual plan. Unlike a family floater, this structure allocates a separate sum insured to each insured member (for example, ₹15 lakh per person).
Each family member receives a separate, dedicated sum insured.
A claim made by one member does not reduce the coverage available to other members.
It offers the convenience of having one policy document, a single proposer, and one premium payment without requiring all members to share the same sum insured.
Multi-individual plans may cost more than traditional family floaters but can be cheaper than purchasing 5 separate individual policies, depending on the insurer's pricing and available discounts.
Some plans offer broader relationship eligibility, allowing you to cover extended family members, such as siblings, grandparents, or in-laws, under one policy document.
Individual Policies for Senior Parents
If your family of 5 includes senior parents, consider keeping their health insurance separate from the policy covering the younger couple and children. Family floater premiums depend on the age of the eldest insured member. Including a senior parent can therefore increase the overall premium.
A practical approach is to buy a family floater for the couple and children, and purchase separate individual policies or a family floater for the parents. This can help you choose coverage better suited to your parents' medical needs.
Talk to an expert today and find the right insurance for you.
Sample Premiums by Age and Sum Insured
Family Floater Plan
Profiles for HDFC ERGO Optima Secure
₹15 Lakh Sum Insured
₹25 Lakh Sum Insured
(2 Adults, 3 Children): Ages (35, 34, 10, 7, 5)
₹34,409
₹37,405
(4 Adults, 1 Child): Ages (31, 29, 59, 55, 5)
₹79,818
₹89,014
Multi-Individual Plan
Profiles for HDFC ERGO Optima Secure
₹15 Lakh Sum Insured Each
(2 Adults, 3 Children): Ages (35, 34, 10, 7, 5)
₹51,571
(4 Adults, 1 Child): Ages (31, 29, 59, 55, 5)
₹1,09,402
The premiums are illustrative and calculated for residents living in Delhi (pincode: 110010) for a 1-year tenure with recommended add-ons. Your final premium will depend on the plan you choose, your age, medical history, location, cover amount, and discounts.
Note: The family floater provides ₹15 lakh of shared coverage to all 5 members, while the multi-individual option provides a separate ₹15 lakh sum insured to each member. These are different coverage structures, so you shouldn't interpret their premiums as prices for equivalent protection.
Factors to Consider When Choosing Health Insurance for a Family of 5
01
Member and Relationship Eligibility
Insurers set strict rules on who can be included in a floater plan. Always confirm whether the policy allows three dependent children or elderly parents before committing.
02
Room Rent Limits and Co-Payment
Ensure the policy has no room rent limits. Policies with room rent limits can apply proportionate deductions to doctor fees, ICU charges, and nursing costs if you choose a room above your eligible limit. If you're covering senior citizens, also check for mandatory co-payment clauses, as these require you to pay a specified percentage of each admissible claim out of pocket. Prefer plans without mandatory co-payment.
03
Restoration or Refill Benefits
Check when restoration applies, how often coverage is restored, and whether it covers the same illness. Check whether restoration applies to the same illness or only to subsequent, unrelated illnesses.
04
PED Waiting Periods
If any family member has conditions like diabetes, thyroid issues, or hypertension, look for plans offering shorter PED waiting periods or options to reduce them.
05
Network Hospital Access
Verify that major multi-specialty hospitals near your residence have cashless claim facilities with the insurer.
Why Choose Ditto for Health Insurance?
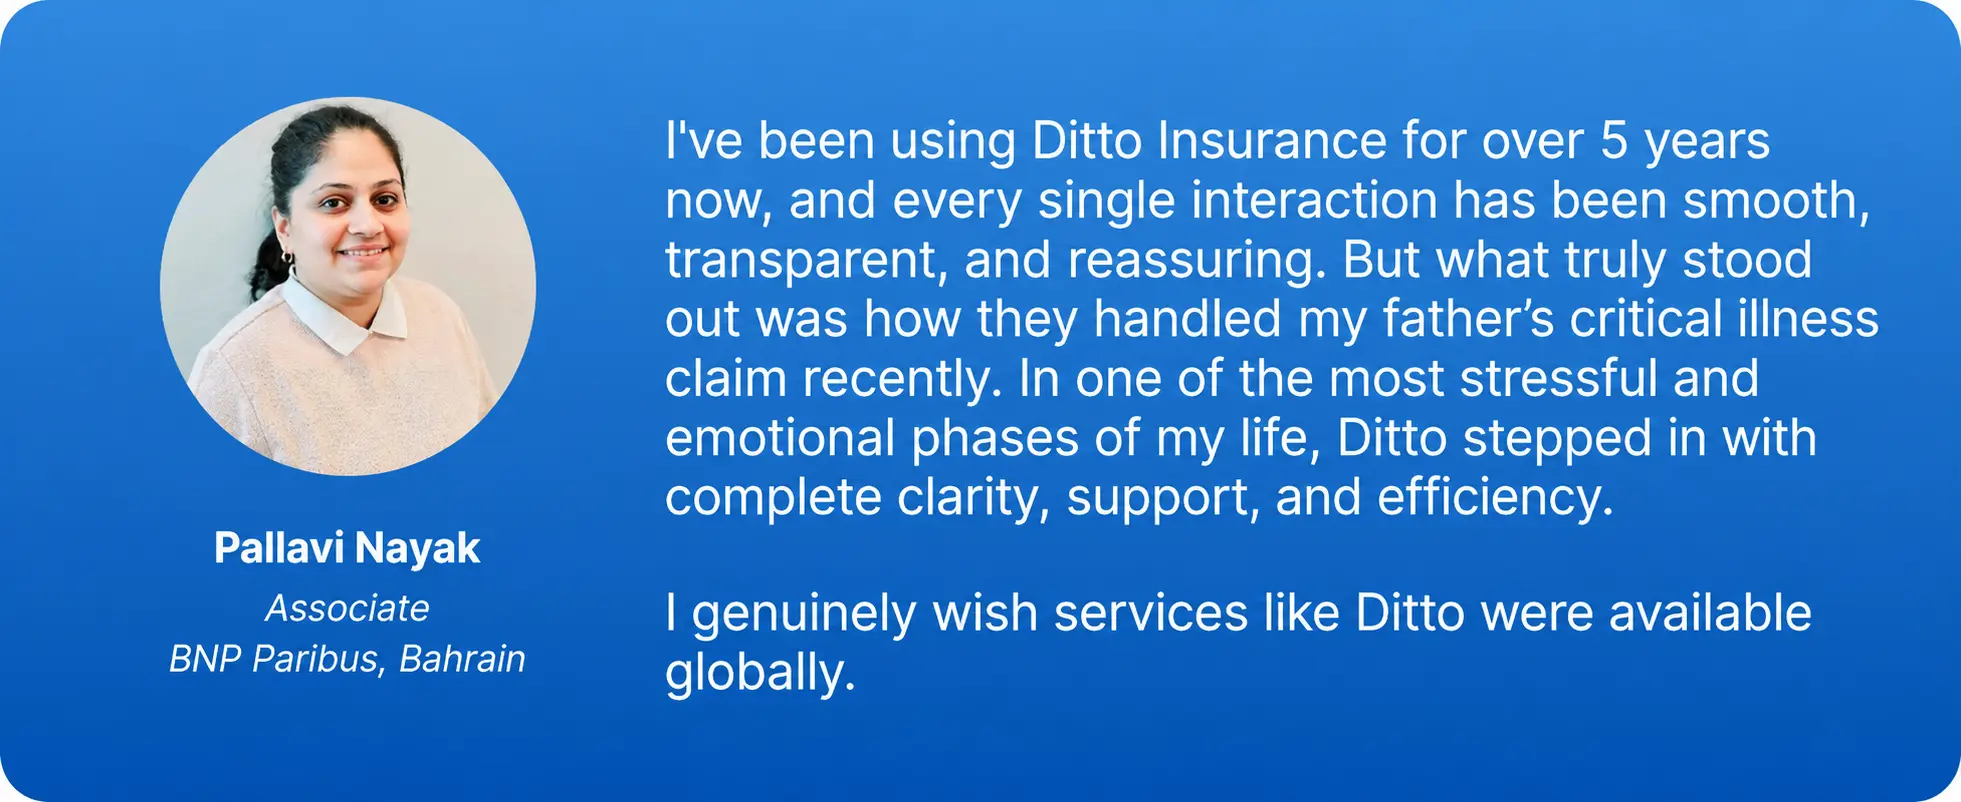
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Pallavi love us:
100% Free Consultation
No Spam. No Sales Pressure.
Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
Backed by Zerodha
Dedicated Claim Support Team
Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
The best health insurance arrangement for 5 people depends on who needs coverage. A shared floater can work well for two adults and three dependent children, while families including parents may benefit from separate coverage.
Start by listing each member's age and medical history, then compare eligible plans, premiums, room rent limits, copayments, and restoration benefits. Choose the combination that provides adequate protection without making premiums difficult to sustain.
Frequently Asked Questions
Can a family of 5 with parents aged 59 and 55 get health insurance under one policy?
Yes, a family of 5 may be covered under one policy through a family floater or multi-individual plan, provided the insurer accepts the required relationships and member combination. Plans such as HDFC ERGO Optima Secure+ and SBI Super Health offer broader eligibility for adult family members. However, including parents aged 59 and 55 in a shared floater can increase the premium because the eldest member's age is often a major pricing factor. Also, check the entry-age requirements before choosing a plan designed specifically for senior citizens.
Should a family of 5 with parents who have pre-existing conditions buy separate health insurance policies?
Yes, keeping parents with pre-existing conditions such as diabetes or hypertension on a separate policy is worth considering. Their treatment costs could consume a significant portion of a shared family floater's sum insured, leaving less coverage for other members. Additionally, their coverage may come with PED waiting periods, co-payments, or other restrictions. A separate individual policy or senior citizen floater can protect the younger family's coverage while letting you choose benefits that suit your parents, like outpatient and waiting period reduction riders.
What health insurance policy combination works best for a family of 5 with employer cover?
A combination of employer-provided health insurance and personal retail coverage can offer better financial protection. Corporate health insurance may provide useful benefits, including coverage for pre-existing conditions from day one, depending on the employer's policy. However, coverage limits and benefits can change when you change jobs. Consider maintaining a personal family floater or a suitable base policy with a super top-up. Comparing both options can help you find affordable health insurance for family of 5 without relying entirely on employer-provided cover.
Does adding a fifth member significantly increase a family floater’s premium in health insurance?
Not necessarily. Adding a fifth member who is a dependent child may increase the premium, but the impact is generally smaller than adding an older adult. The health insurance for family of 5 cost depends on the age of the eldest insured member, sum insured, location, and other pricing factors. Adding a senior parent can increase the premium considerably because the insurer considers their age and associated health risks.
If one member uses the entire sum insured, can the other four members still claim under a restoration benefit?
They may be able to, provided the policy's restoration benefit is activated, and the subsequent claim meets its conditions. Some plans restore the sum insured only after complete exhaustion, while others allow restoration after partial use. The rules may also differ on whether you can use the restored amount for the same illness or only unrelated illnesses. Check the restoration frequency, activation conditions, and usage restrictions before relying on it for a family of 5.
Does the eldest member’s age determine the premium for a family floater covering 5 people?
Yes. In a standard family floater, the insurer uses the eldest insured member's age to calculate the premium. For example, if a 30-year-old includes their 60-year-old parent in the same floater, the premium may be considerably higher than that for a policy covering only the younger family members. This is because older members generally have a higher likelihood of making health insurance claims. Keeping parents on a separate policy can help manage premiums for both groups.
Is it better to split a family of 5 into two family floater health insurance policies?
Yes. Splitting a family of 5 into two floaters can be useful if the family includes parents or members with different medical histories and healthcare needs. It can also help when a single policy's member limits or eligibility rules don't accommodate your family. For example, if you prefer Care Supreme, which allows a maximum of 2 adults and 2 children, you can instead compare a different 5-member family floater or split this into 2 floater policies: 1 adult and 1 child, and 1 adult and 2 children. As long as each policy permits the selected family members.
What is the best health insurance policy combination for a family of 5?
The best health insurance for family of 5 depends on its age profile, medical needs, and budget. You can choose one family floater or a multi-individual policy covering all five members, as long as the insurer allows the required family composition. Alternatively, consider one floater for the couple and children with separate policies for the parents, or split the family across two floaters. If your family includes older parents, separate coverage may be a better fit. Before deciding, compare premiums, waiting periods, underwriting restrictions, and continuity with existing policies.