

Overview
When you buy health insurance, you want a plan that supports you when medical expenses start piling up. A good insurer, a wide hospital network, and useful features can make a big difference during a claim.
HDFC ERGO is a well-known name in the health insurance space, offering multiple plans for individuals and families. But with different coverage options, benefits, and add-ons, choosing the right plan can be confusing.
In this guide, we break down HDFC ERGO health insurance plans, what each is designed for, and how they differ in coverage and pricing. We also explain how the claims process works, so you can make a clearer, more informed choice.
HDFC ERGO Health Insurance: Performance Metrics
Note: This information comes from IRDAI annual reports and HDFC ERGO Health Insurance public disclosures. To explore more such data, please refer to Ditto Data Lab.
HDFC ERGO Health Insurance Top Plans, Features & Coverage Compared
HDFC ERGO Optima Secure Plus
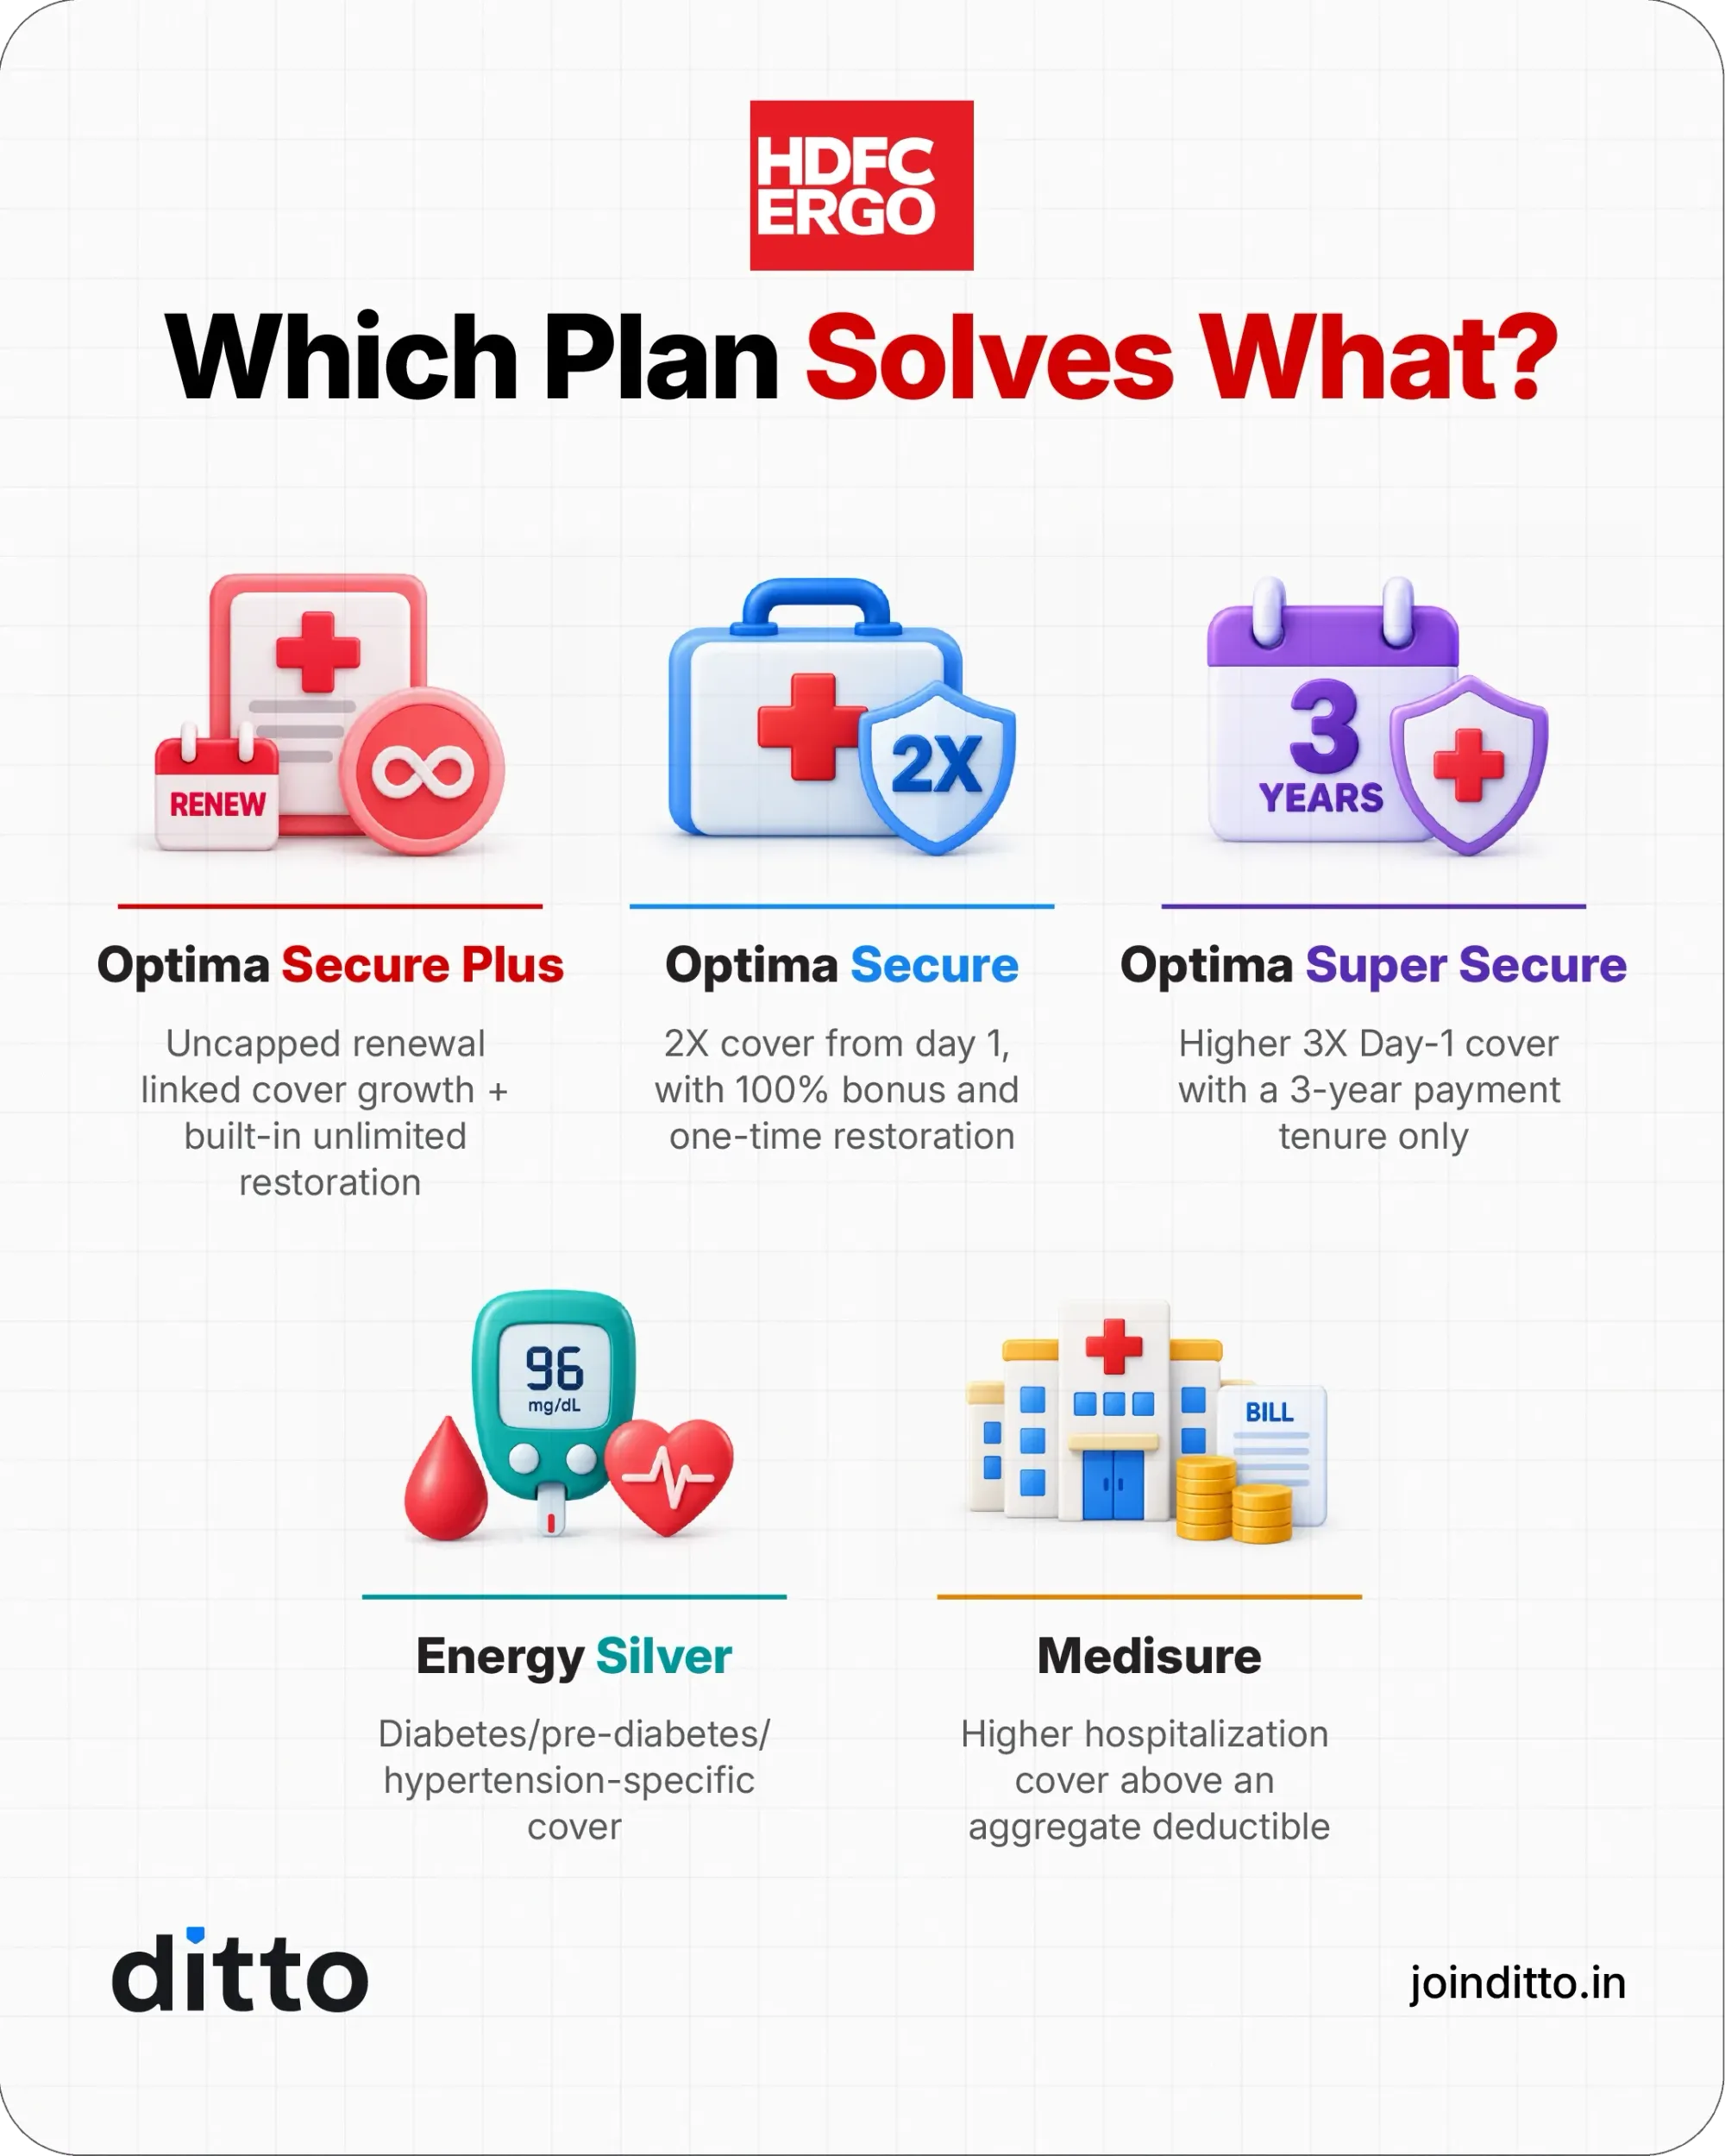
Optima Secure Plus is HDFC ERGO’s flagship plan and the key plan in its lineup. The focus here is long-term coverage growth without needing to upgrade later.
Key Features:
- Entry Age: 18 to 60 years (children: 91 days to 25 years)
- Sum Insured: ₹10 lakh to ₹2 crore
- Bonus: 100% of the base SI added every year, with no cap
- Pre- and Post-Hospitalization: 60/180 days
- 2x cover from day 1
- Unlimited restoration on partial exhaustion
- Covers consumables like gloves, PPE, and masks
HDFC ERGO Optima Secure
Optima Secure is the older version of the Plus variant and still a relevant option, especially for those above 60.
Key Features:
- Entry Age: 18 years, with no upper limit
- Sum Insured: ₹5 lakh to ₹2 crore
- 2x cover from day 1
- Bonus: 50% increase per year, capped at 100%
- Restoration: Once per year (unlimited option available as an add-on)
- Consumables covered
While HDFC ERGO markets Optima Secure as a 4x plan, that full benefit builds over time. You start with 2x cover from day one, and the rest comes in as bonus and restoration. Compared to Optima Secure Plus, coverage growth is capped, but it remains a practical option if you’re not eligible for the Plus variant.
HDFC ERGO Optima Super Secure
Optima Super Secure is positioned as a higher upfront coverage plan with a stronger starting multiplier.
Key Features:
- Entry Age: 18 years, with no upper limit
- Sum Insured: ₹10 lakh to ₹2 crore
- 3x cover from day 1
- Bonus: 50% increase per year, capped at 100%
- Restoration: Once per year (unlimited via add-on)
- Consumables covered
- Mandatory 3-year policy tenure
Our Recommendation: Instead of this plan, Optima Secure Plus over a 3-year tenure usually makes more sense. The uncapped growth (Infinite Benefit) in the Plus variant generally outweighs the 3x advantage here.
HDFC ERGO Energy Silver Plan
Energy Silver is designed for a very specific use case: individuals with diabetes and/or hypertension.
Key Features:
- Entry Age: 18 to 65 years (individual plan only)
- Sum Insured: ₹2 lakh to ₹50 lakh
- Bonus: 10% yearly increase, capped at 100%
- Restoration: Once per year
- Day 1 coverage for diabetes and hypertension (as per terms)
- Consumables not covered
Outside of this, it functions like a standard health plan.
Ditto’s Take (Energy Silver vs. Energy Gold):
The Gold variant mainly adds wellness perks and check-ups at a higher cost without improving core hospitalization cover. If your focus is hospitalization protection, compare the premium difference carefully before opting for Gold.
HDFC ERGO Medisure Super Top Up Plan
Medisure is not a standalone replacement for health insurance. It is meant to sit on top of an existing base policy and increase your total coverage at a lower cost.
Key Features:
- Entry Age: 18 to 65 years (children: 91 days to 23 years)
- Sum Insured: ₹5 lakh to ₹20 lakh
- Deductible: ₹4 lakh and ₹5 lakh
- No bonus or restoration benefits
It activates only after your total expenses cross a fixed deductible. It is the initial amount you pay before the super top-up starts covering expenses. This keeps premiums lower while still protecting you against large medical bills. It works best if you already have a base cover and want to extend it.
Overall, the coverage can feel limited compared to other super top-up plans on the market. The maximum SI goes up to ₹20 lakh, whereas competing plans like Care Supreme Enhance offer ₹1 crore, and ICICI Lombard Activate Booster offers up to ₹3 crore in super top-up options.
Other HDFC ERGO Health Insurance Plans
HDFC ERGO also offers plans for more specific needs.
- Optima Lite is a lower-cover option with room rent limits.
- Optima Senior is designed for older individuals and includes co-payments and disease-wise restrictions.
- Easy Health Standard is a basic hospitalization-focused plan without restoration benefits.
- Optima Restore focuses on coverage growth through restoration and multiplier features.
Ditto’s Take on HDFC ERGO Health Insurance Plans
HDFC ERGO Health Insurance Sample Premium Illustration
The premiums are illustrative and calculated for adults living in Delhi (pincode: 110010) for a 1-year tenure. Your final premium will depend on the plan you choose, your age, medical history, cover amount, and discounts.
HDFC ERGO Health Insurance Claim Process: Steps & Documents
Cashless Claims (Network Hospitals)
You can get treated without paying upfront for admissible expenses.
- Inform the Insurer (Or via the Hospital): Share your policy card and ID at the hospital TPA (Third-Party Administrator) desk. Inform at least 48 hours before planned admission, or within 24 hours in emergencies.
- Pre-Authorization: The hospital sends a request to the insurer, who reviews it once all details are submitted.
- Discharge: The insurer settles approved bills directly with the hospital. You only pay for non-covered items.
Reimbursement Claims
If you don’t use cashless, you can claim expenses after discharge.
- Inform the Insurer: 48 hours before planned treatment or within 24 hours of emergency admission. Pay out of pocket at discharge.
- Keep Documents: Itemized bills, receipts, discharge summary, prescriptions, and reports.
- Submit Claim: Fill out and submit the claim form with documents (usually within 30 days).
- Settlement: After review, the approved amount is credited to your bank account.
Note: If your policy is taken via Ditto, we provide end-to-end renewal and claims assistance.
Pros and Cons of HDFC ERGO Health Insurance
Pros:
- Strong Claims Track Record: HDFC ERGO reports an average claim settlement ratio of 97.61% (FY 2024-26). This points to consistent claim approvals over time.
- Wide Hospital Network: Access to 16,000+ cashless hospitals across India, covering both metros and smaller cities.
- No Major Restrictions: Plans like Optima Secure, Optima Secure Plus, and Optima Super Secure come without room rent limits, disease-wise sub-limits, or mandatory co-payments.
Cons:
- Higher Premiums: The wide range of features comes with comparatively higher premiums.
Why Choose Ditto for Health Insurance?
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Pallavi love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
HDFC ERGO remains one of the most reliable insurers in the Indian health insurance space, with a strong mix of product design and consistent claims experience. With Optima Secure Plus, it pushes this further by offering uncapped annual growth in total coverage.
That said, the right HDFC ERGO family health insurance plans depend on your needs. If you want a plan that scales well over time, Optima Secure Plus stands out. If you have complex existing conditions like diabetes or hypertension, Energy Silver is built specifically for that use case. And if you already have a base policy, a Medisure Super Top Up can help increase your overall cover at a lower cost.
The key is to match the plan to your situation rather than picking based on features alone. Before buying, compare the policy wording, waiting periods, exclusions, and premium quotes based on your healthcare needs. You can also speak to a Ditto advisor for help comparing plans.
Frequently Asked Questions
Last updated on: