Health Insurance

₹25 Lakh Health Insurance

Ann Tresa Jais

Written by Ann Tresa Jais

Insurance Writer

Ishita Jain

Reviewed by Ishita Jain

IRDAI-Certified Expert at Ditto

SP0738675913

Certified
₹25 Lakh Health Insurance

Overview

A ₹25 lakh health insurance policy can provide substantial financial protection against eligible medical expenses

Key Features & Benefits

  • Comprehensive Coverage: Covers hospitalization expenses, including surgeries, ICU charges, and other eligible medical treatments, subject to policy terms.
  • Pre- and Post-Hospitalization: Depending on the policy, medical expenses may be covered for up to 60 days before hospitalization and 180 days after discharge.
  • Cashless Treatment: Allows eligible medical bills to be settled directly with network hospitals, subject to claim approval.
  • No-Claim Bonus (NCB) / Restoration: An NCB can increase the available coverage, while restoration benefits replenish the sum insured under specified conditions.

Is ₹25 Lakh Enough?

  • For Families: A ₹25 lakh family floater offers shared coverage, meaning a major hospitalization claim could leave less coverage available for other family members.
  • Super Top-Up Option: A super top-up plan can provide additional financial protection once eligible medical expenses exceed the applicable deductible, subject to policy conditions.

A ₹25 lakh health insurance plan is a strong base cover for many buyers today. It can comfortably handle major surgeries, long intensive care unit (ICU) stays, or one serious illness in a private hospital. But that may not be the right fit for everyone. Your ideal cover depends on where you live, your age, and whether you are buying for yourself or your family.

In this article, we break down whether ₹25 lakh health insurance is enough, the best plans at this sum insured, and the premiums you can expect.

Is a ₹25 Lakh Health Insurance Enough for You in 2026?

For most working adults and families in India, ₹25 lakh is a genuinely strong base cover. It's the maximum cover we recommend to take for the following reasons: 
Background Image

01

Medical Inflation

Medical inflation in India leads to rising treatment costs every 2-3 years. A ₹10 lakh cover that feels adequate today may feel like ₹5 lakh in a few years. Choosing ₹25 lakh health insurance reduces the risk of your cover feeling inadequate a few years later.

02

Difficulty in Increasing Sum Insured

If you are diagnosed with a serious medical condition later, an insurer may reject your request to increase the sum insured. Waiting too long to upgrade your coverage can leave you underinsured at exactly the stage of life when your health risks and treatment costs are both higher.

03

Black Swan Analogy

While there’s little chance of ₹25 lakh health insurance getting exhausted, an unexpected health emergency could turn your life upside down. Examples of high-cost treatments include cancer care or a bone marrow transplant, which can create a major financial burden.

Let’s also take a look at the surgical costs in India that have increased to a great extent between 2016 and 2025:
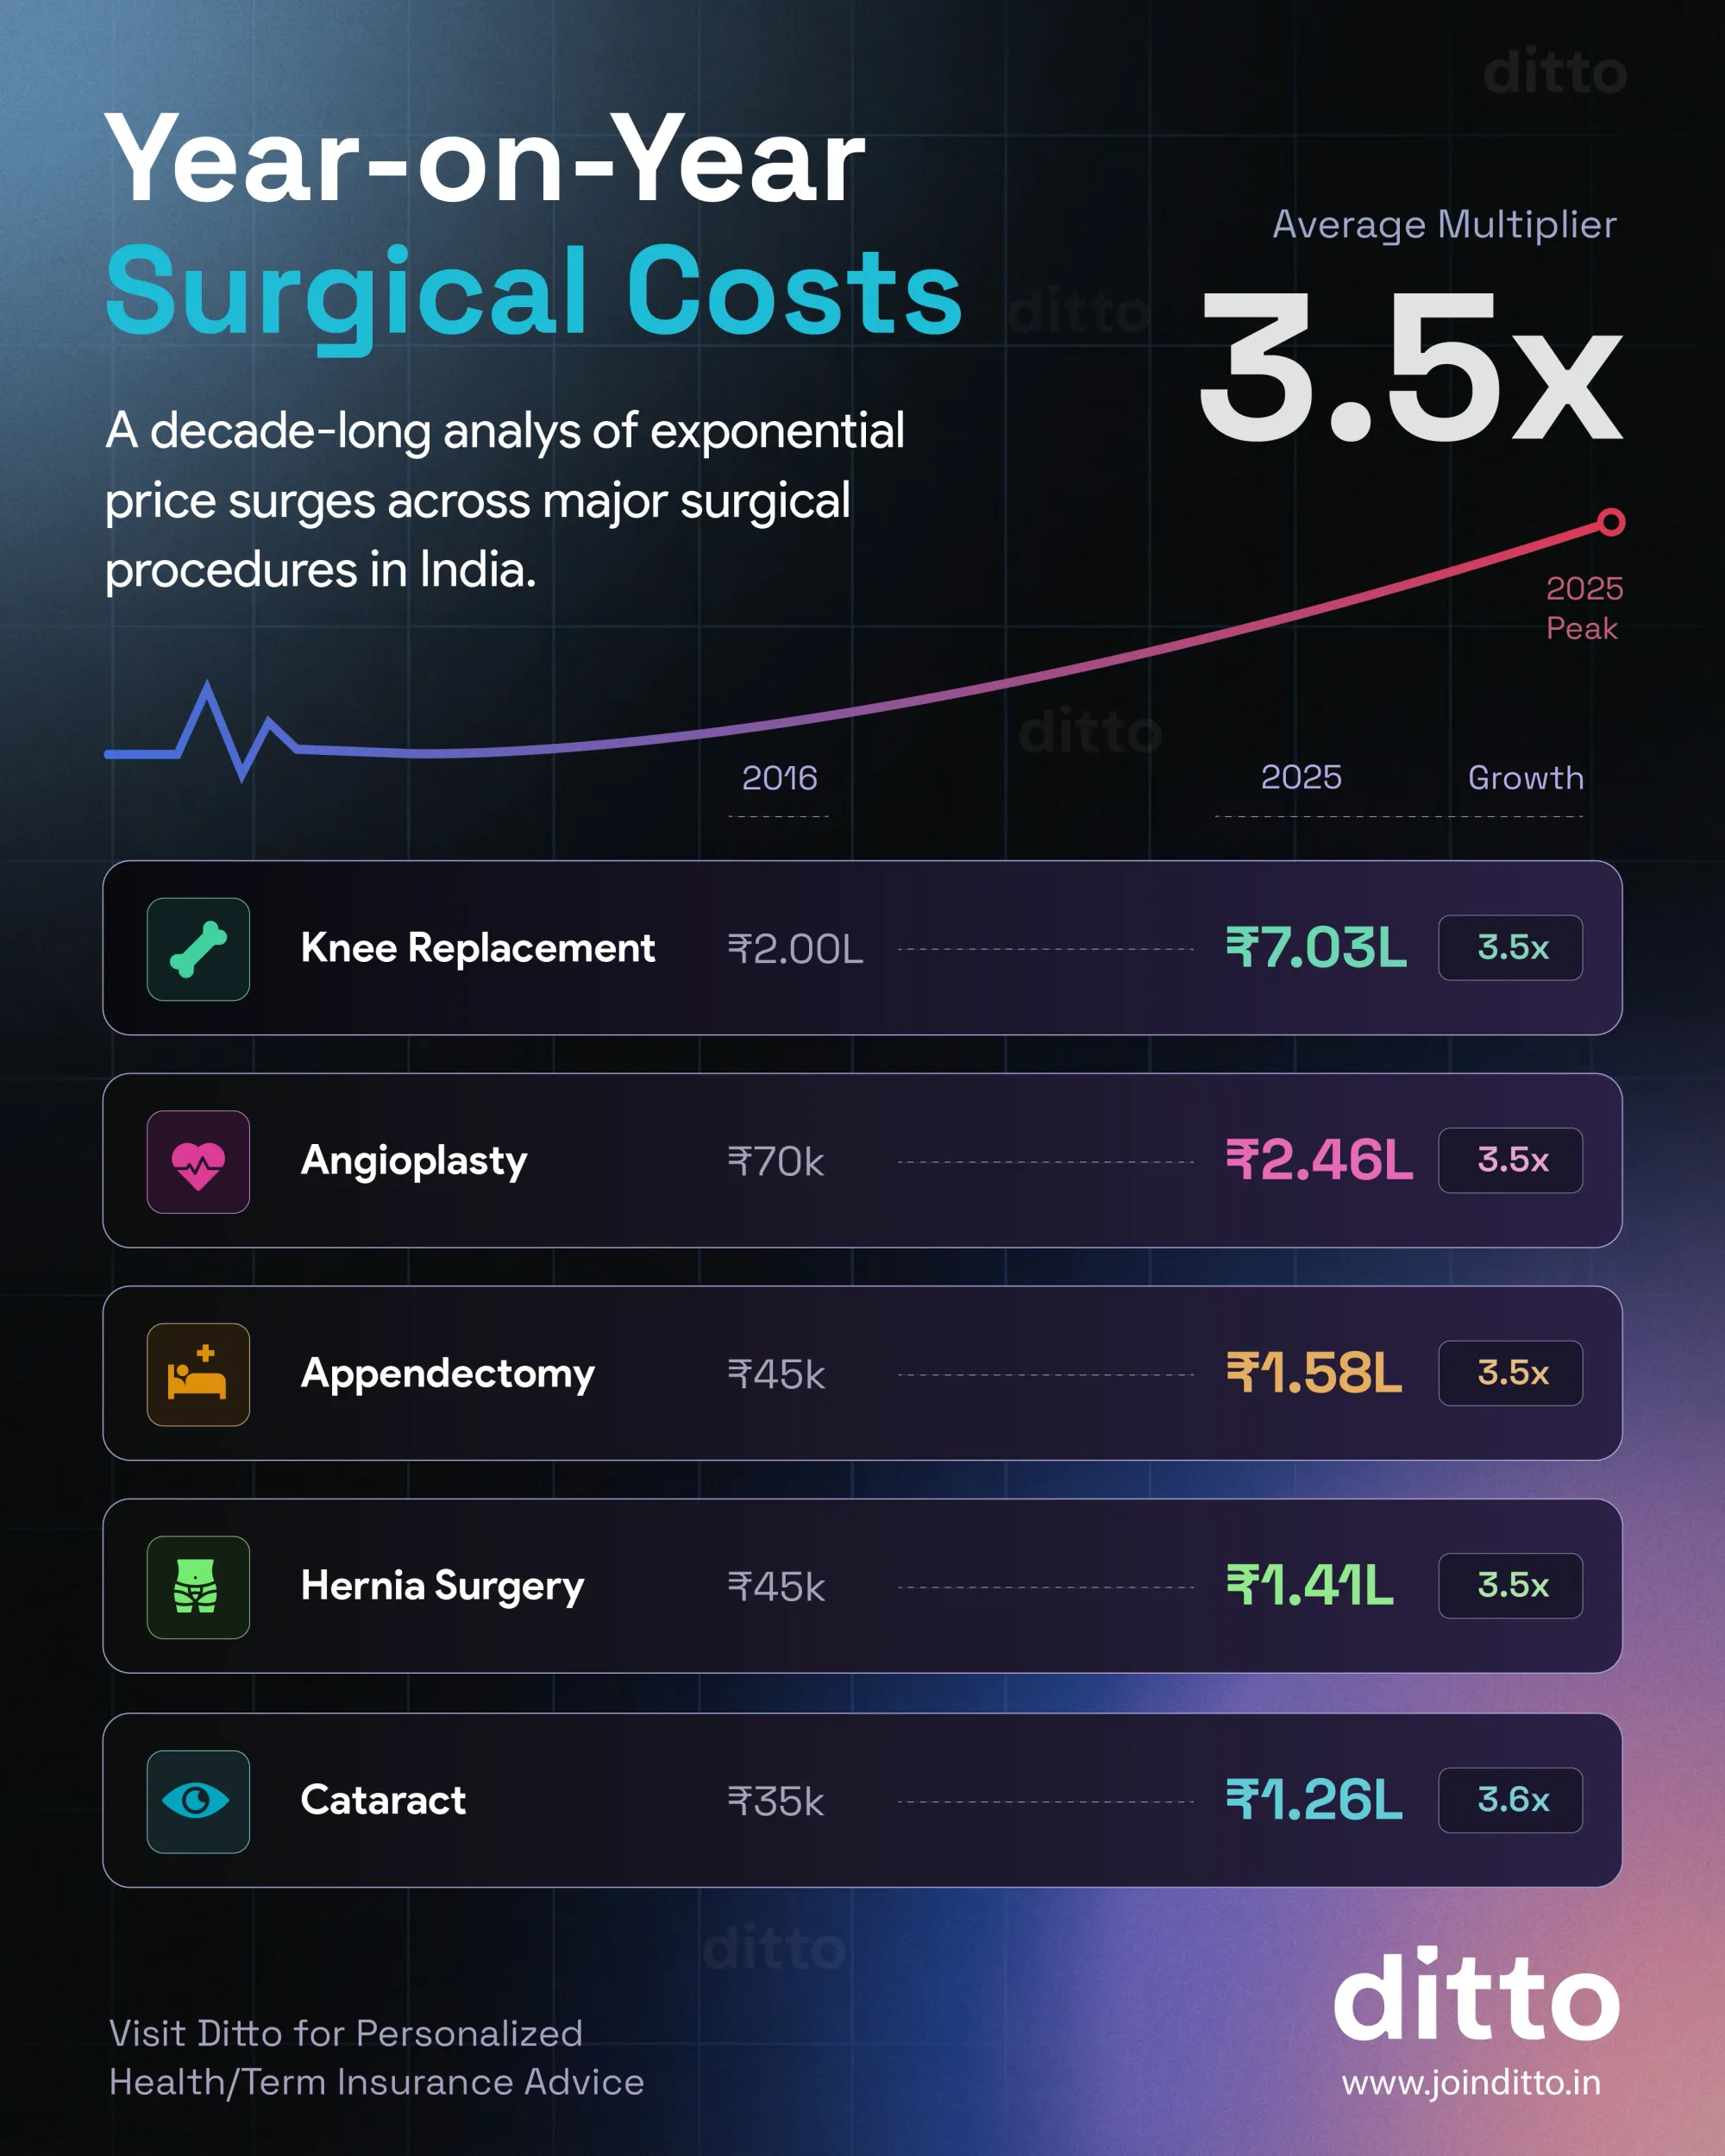
Surgical costs in India rose 3.5 times from 2016 to 2025, with knee replacement, angioplasty, and other procedures seeing cost hikes.

A ₹25 lakh health insurance plan also gives you a comfortable buffer over these real-world costs. 

Talk to an expert
today and find
the right
insurance for you.
Ditto Advisor

Best Health Insurance Plans With ₹25 Lakh Sum Insured

PlanInsurer MetricsKey FeaturesSum Insured
HDFC ERGO Optima Secure+CSR: 97.61%, ICR: 81.62%, Network hospitals: 16,000+2x cover from day one, Infinity Benefit adds 100% of base cover every year without a cap, built-in consumables cover, unlimited restoration, and 60/180 days pre- and post-hospitalization coverage. ₹5 lakh to ₹2 crore 
Care SupremeCSR: 95.45%, ICR: 58.68%, Network hospitals: 11,400+Unlimited restoration of 100% base cover for any illness, 50% annual bonus up to 100%, 60 days before and 180 days after hospitalization, plus optional bonus enhancements and consumables cover. ₹5 lakh to ₹1 crore 
Aditya Birla Activ One MAXCSR: 96.25%, ICR: 68.16%, Network hospitals: 16,500+Unlimited restoration from the second claim, 100% annual bonus up to 500% regardless of claims, and wellness rewards offering up to 100% renewal premium discount. ₹5 lakh to ₹2 crore 

Here, CSR stands for claim settlement ratio, ICR denotes incurred claims ratio, and SI implies the sum insured. 

Note: Niva Bupa ReAssure 3.0 Black is on Ditto’s list of the best health insurance plans in India, but we haven't included it here because it does not offer a ₹25 lakh sum insured option. Similarly, SBI Super Health Platinum Infinite starts at ₹50 lakh, so it doesn't qualify for this list either.

Premiums For ₹25 Lakh Sum Insured

A ₹25 lakh health insurance plan may sound expensive at first. However, there is very little difference in the premiums you pay for a cover amount of ₹10 lakh, ₹15 lakh, and ₹25 lakh.

To illustrate this, let’s compare the sample premiums of all three options for a tier 1 city (New Delhi: 110010). The plan considered for this calculation is Aditya Birla Activ One MAX.

Profiles₹10 Lakh₹15 Lakh₹25 Lakh
(Individual Plan): Age 25₹9,159₹11,671₹12,896
(Family Floater, 2A): Ages (31, 32)₹14,404₹18,743₹21,045
(Family Floater, 2A 1C): Ages (35, 34, 5)₹19,025₹24,700₹27,683
(Family Floater, 2A): Ages (60, 59)₹40,772₹52,875₹60,257

Here, ‘A’ refers to an adult, and ‘C’ denotes a child. 

Note: The premiums are indicative, and the final amount may vary based on your medical profile, age, or location.

Background Image

Common Mistakes to Avoid While Choosing a ₹25 Lakh Sum Insured

01

Treating ₹25 Lakh as Sufficient Forever

Rising medical costs each year mean your ₹25 lakh cover, which feels generous today, may not feel sufficient in 10–15 years. Look for plans with strong bonuses and restoration benefits that build effective coverage over time.

02

Ignoring the Sub-Limits

Some plans that appear affordable at ₹25 lakh may come with co-pays, room rent restrictions, or disease-wise sub-limits. Limitations related to room rent caps trigger a proportionate deduction from your entire claim, meaning you end up paying an amount out of pocket. Always check the fine print on sub-limits before buying health insurance plans.

03

Not Checking Primary Features

A comprehensive health insurance plan will always have primary features like coverage for pre- and post-hospitalization expenses, to name a few. If your ₹25 lakh health insurance plan does not include these standard features, you can consider switching to another insurer that provides the same features.

04

Adding Parents to a ₹25 Lakh Floater

When you add a 58-year-old parent to your floater, the premium is calculated based on their age. That significantly increases what you pay. Worse, a hospitalization for the parent can drain the shared sum insured quickly, leaving younger members under-covered for the rest of the year. Separate policies for parents always make more financial sense.

05

Ignoring Claim Experience

A lower premium does not always mean better value. Claims-related issues make up a large share of customer grievances, so you should also look at the insurer’s service track record, network strength, and claim support experience.

Why Choose Ditto for Health Insurance?
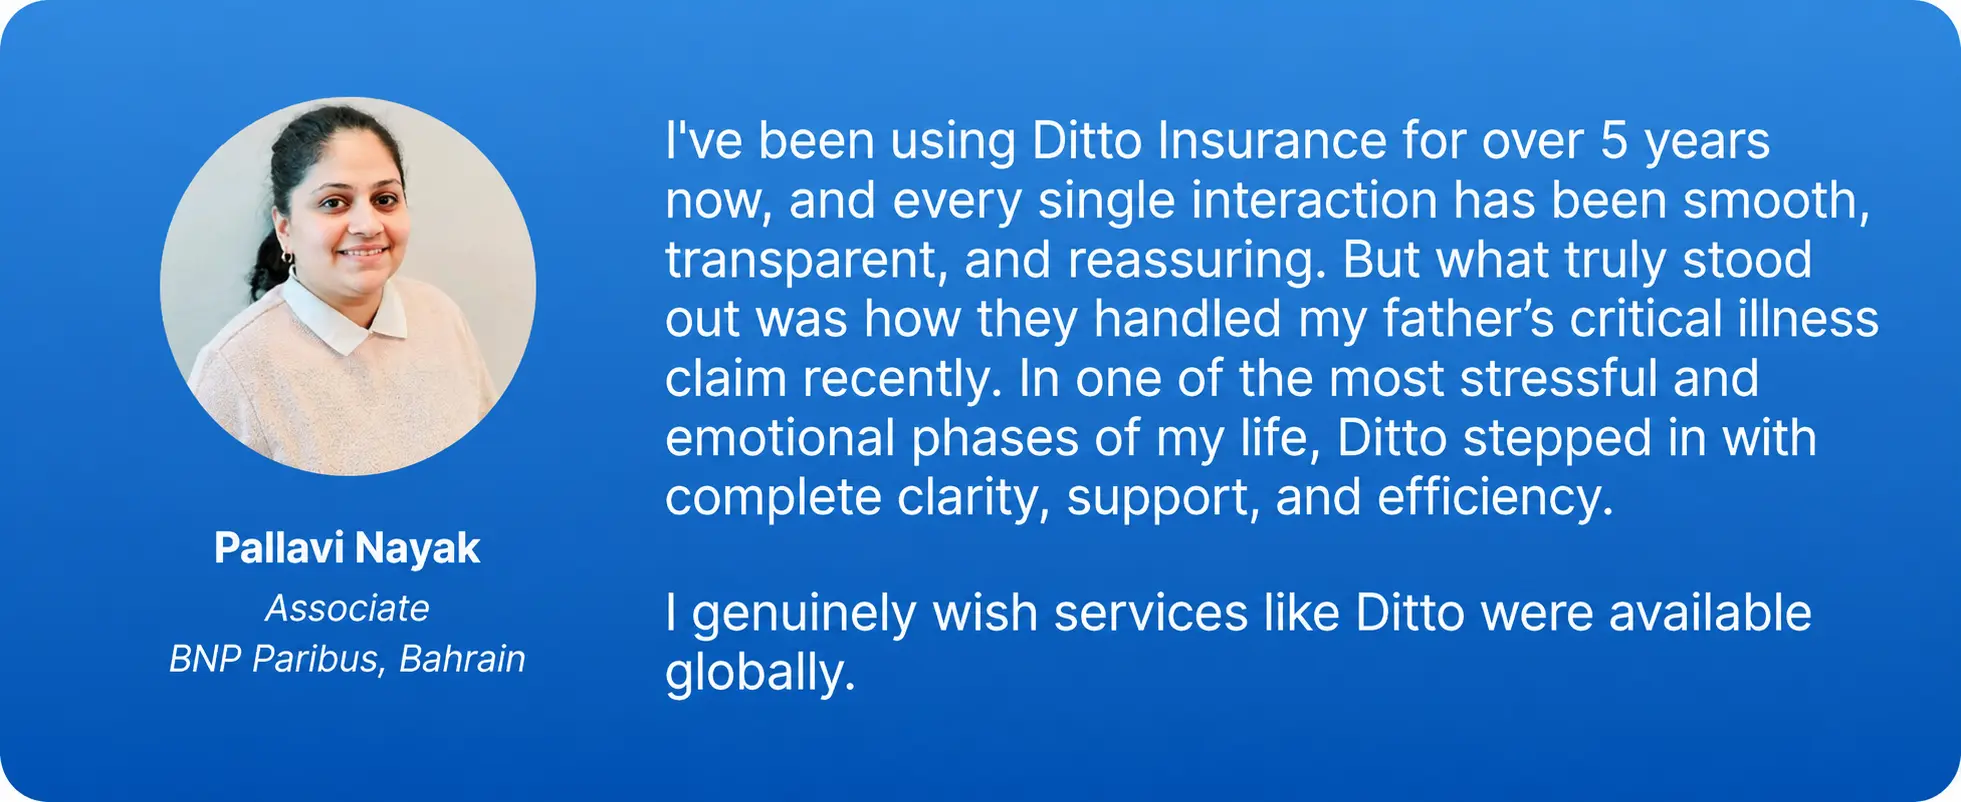
Pallavi Nayak LinkedIn Customer Testimonial

At Ditto, we’ve assisted over 12,00,000 customers choose the right insurance policy. Why customers like Pallavi love us:

    • 100% Free Consultation
    • No Spam. No Sales Pressure.
    • Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
    • Backed by Zerodha
    • Dedicated Claim Support Team
    • Compare Plans and Premiums with a Trusted Insurance Advisor

Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!

Ditto’s Take on ₹25 Lakh Health Insurance

₹25 lakh health insurance is typically the maximum base cover we recommend for most buyers in 2026. It works particularly well for single individuals in Tier 1 cities and for those in Tier 2 cities who already have corporate coverage and want to supplement it with a personal policy.

That said, it may not always be sufficient for family floaters. Since the sum insured is shared among all members, a single large claim can significantly reduce the available coverage for others within the same policy year. In such cases, opting for a higher base cover can offer more reliable protection.

Frequently Asked Questions

Is ₹25 lakh health insurance enough in India in 2026?

Yes, ₹25 lakh health insurance provides a strong base cover for most individuals and young families in India. It can handle several expensive hospitalizations, including major surgeries and prolonged ICU stays. However, the right coverage depends on your age, medical history, city, and preferred hospitals. Families sharing one policy or individuals seeking treatment at expensive private hospitals should also consider whether they need additional coverage.

How much does a ₹25 lakh health insurance policy cost per year?

The annual premium depends on your age, family size, location, medical history, and chosen insurer. For example, Aditya Birla Activ One MAX has an indicative annual premium of ₹11,214 for a 25-year-old individual in New Delhi. A family floater covering two adults aged 31 and 32 costs around ₹18,300 annually. These are sample premiums, and the final price depends on underwriting, selected benefits, and applicable discounts.

Is ₹25 lakh health insurance enough for a family of four?

A ₹25 lakh family floater can provide substantial coverage for two adults and two children. However, all four members share the same sum insured. If one family member incurs a hospitalization bill of ₹15 lakh, only ₹10 lakh of the original base cover remains for other claims during that policy year. Restoration benefits can help, subject to policy conditions. Families should consider their combined medical needs before choosing coverage.

Should I choose ₹10 lakh, ₹15 lakh, or ₹25 lakh health insurance?

₹25 lakh offers a larger financial buffer against expensive treatments and future medical inflation. The premium difference is also relatively small for certain age groups. For example, under Aditya Birla Activ One MAX, a 25-year-old in New Delhi pays approximately ₹7,964 annually for ₹10 lakh coverage, compared with ₹11,214 for ₹25 lakh. The additional ₹3,250 provides ₹15 lakh more in base coverage, subject to policy conditions.

What happens if my ₹25 lakh health insurance cover gets exhausted?

Once the available sum insured is exhausted, the insurer stops paying additional claims from that exhausted coverage. However, policies with restoration or recharge benefits provide additional coverage under specified conditions. HDFC ERGO Optima Secure+ and Care Supreme include unlimited restoration benefits. The amount restored, eligible claims, and timing of restoration depend on the policy wording. Check these conditions carefully instead of assuming every subsequent hospitalization receives automatic full coverage.

Can I increase my health insurance cover from ₹10 lakh to ₹25 lakh later?

Yes, you can request an increase in your health insurance sum insured, usually at renewal. However, the insurer can assess your current health, medical history, and underwriting eligibility before approving the additional coverage. A new diagnosis or serious medical condition can make approval difficult. Waiting periods can also apply to the increased portion of coverage. Buying adequate health insurance early reduces the risk of facing these restrictions later.

Should I buy separate ₹25 lakh health insurance policies for my parents?

Separate health insurance policies are often more practical for parents, especially when they are older than the other family members. Adding parents to a shared floater can substantially increase premiums and expose the entire family to one member's hospitalization expenses. Separate coverage keeps the parents' sum insured independent of the younger family's policy. However, compare premiums, medical underwriting requirements, and available family floater options before making the final decision.

Do I need ₹25 lakh personal health insurance if my employer already provides coverage?

Yes, having personal health insurance alongside employer-provided coverage is worth considering. Corporate health insurance depends on your employment and the employer's policy terms. Coverage can end when you leave the organization, and benefits can change during renewals. A personal ₹25 lakh policy provides independent coverage that continues as long as you renew it according to the policy conditions. It also protects you against relying entirely on your employer's insurance.

Last updated on: