

Overview
At 65, buying term insurance is no longer as simple as finding the lowest premium. Availability is limited, and you may not have access to comprehensive personal term plans. Underwriting also gets stricter, and the need for life cover changes. So, should senior citizens above 65 even consider term insurance?
This guide explains term insurance for senior citizens, including eligibility, coverage options, premiums, alternatives, and whether life insurance makes sense after retirement.
Can You Buy Term Insurance for Senior Citizens Above 65 Years?
Usually, no. Based on Ditto's extensive research, most retail individual term insurance plans do not accept new applicants over 65. Even for applicants aged 60 to 65, options are limited, with fewer plans offering entry at these ages.
Why Insurers Become Restrictive After Age 65
Higher Mortality Risk
Mortality risk increases with age, which raises the insurer's expected claims risk.
Shorter Policy Terms
Older applicants have fewer years of coverage available, which limits the insurer's ability to spread risk over time.
Stricter Underwriting
Insurers may require additional medical tests and impose tighter eligibility criteria. Additionally, existing health conditions and past medical issues can require more detailed underwriting.
Financial Justification
Insurers assess whether the requested sum assured is reasonable based on the applicant's income, assets, liabilities, and financial needs.
Talk to an expert
today and
find
the right
insurance for you.
Does a 65+ Senior Citizen Actually Need Term Insurance?
Before looking for a term plan, ask a more important question: Do you actually need life insurance at this stage?
Term insurance is designed to replace the financial loss the family faces after the policyholder’s death. So, even at 68, it can make sense if someone still depends on your income or if you have major financial obligations.
You may consider life cover if you have:
- A financially dependent spouse who relies on your income or pension.
- A dependent child whose education or other major expenses are still ahead.
- A special-needs dependent who may require lifelong financial support.
- A significant loan or liability that your family may struggle to repay.
- Business liabilities that could burden your family after your death.
- Any other genuine income dependency where your death could create a financial shortfall.
However, if you have no dependents or major liabilities and your retirement corpus is sufficient to support your family's future needs, buying fresh life cover may offer limited financial value. If you do not have health insurance, you may be better off considering senior citizen health insurance to protect against rising medical expenses.
Term Insurance Options for Senior Citizens Above 65 Years: Plans and Sample Premiums
Most standard individual term insurance plans do not accept new applicants above 65, so there are no regular term plans or sample premiums to compare for this age group.
However, some of the best term insurance for senior citizens offer coverage up to age 65.
Plans Offered for Ages up to 65 Years
- HDFC Life Click 2 Protect Supreme Plus: Click 2 Protect Supreme Plus offers an optional critical illness rider that covers up to 60 illnesses for up to 15 years, subject to terms.
- Bajaj Life eTouch II: eTouch II offers an in-built terminal illness benefit of up to ₹2 crore for eligible policyholders. You can also opt for a waiver of premium benefit for covered events such as accidental disability, subject to applicable terms and conditions.
- Aditya Birla Sun Life Super Term Plan: Super Term Plan offers an optional accelerated critical illness benefit that covers 42 illnesses and can pay up to 50% of the sum assured, subject to applicable limits. The plan also includes a terminal illness benefit of up to ₹1 crore.
Sample Premiums Across Plans and Ages
Note: This illustration is based on a salaried male non-smoker from Delhi (110010) seeking ₹2 crore term cover until age 75. Premiums are indicative and may vary based on age, policy term, riders, discounts, medical profile, and underwriting.
Eligibility Criteria for Term Insurance for Senior Citizens Above 65
Standard individual term insurance plans generally do not accept new applicants above 65. However, specialized group plans have higher entry ages. Eligibility depends on the insurer, age, medical history, financial profile, policy term, and underwriting requirements.
Here’s the maximum entry age and sum assured offered by some leading term plans.
Note: “No upper limit” means there is no predefined maximum sum assured. Actual coverage remains subject to the insurer’s underwriting assessment and the maximum eligible sum assured based on your profile.
Factors That Affect Term Insurance Premiums for Senior Citizens Above 65
Since standard individual term plans generally do not accept new applicants above 65, there is no premium to calculate for most senior citizens in this age group.
However, if a senior citizen is below age 65, the insurer will assess age, medical history, sum assured, policy term, lifestyle habits, occupation, and existing health conditions before deciding the premium and coverage terms.
Why Choose Ditto for Term Insurance?
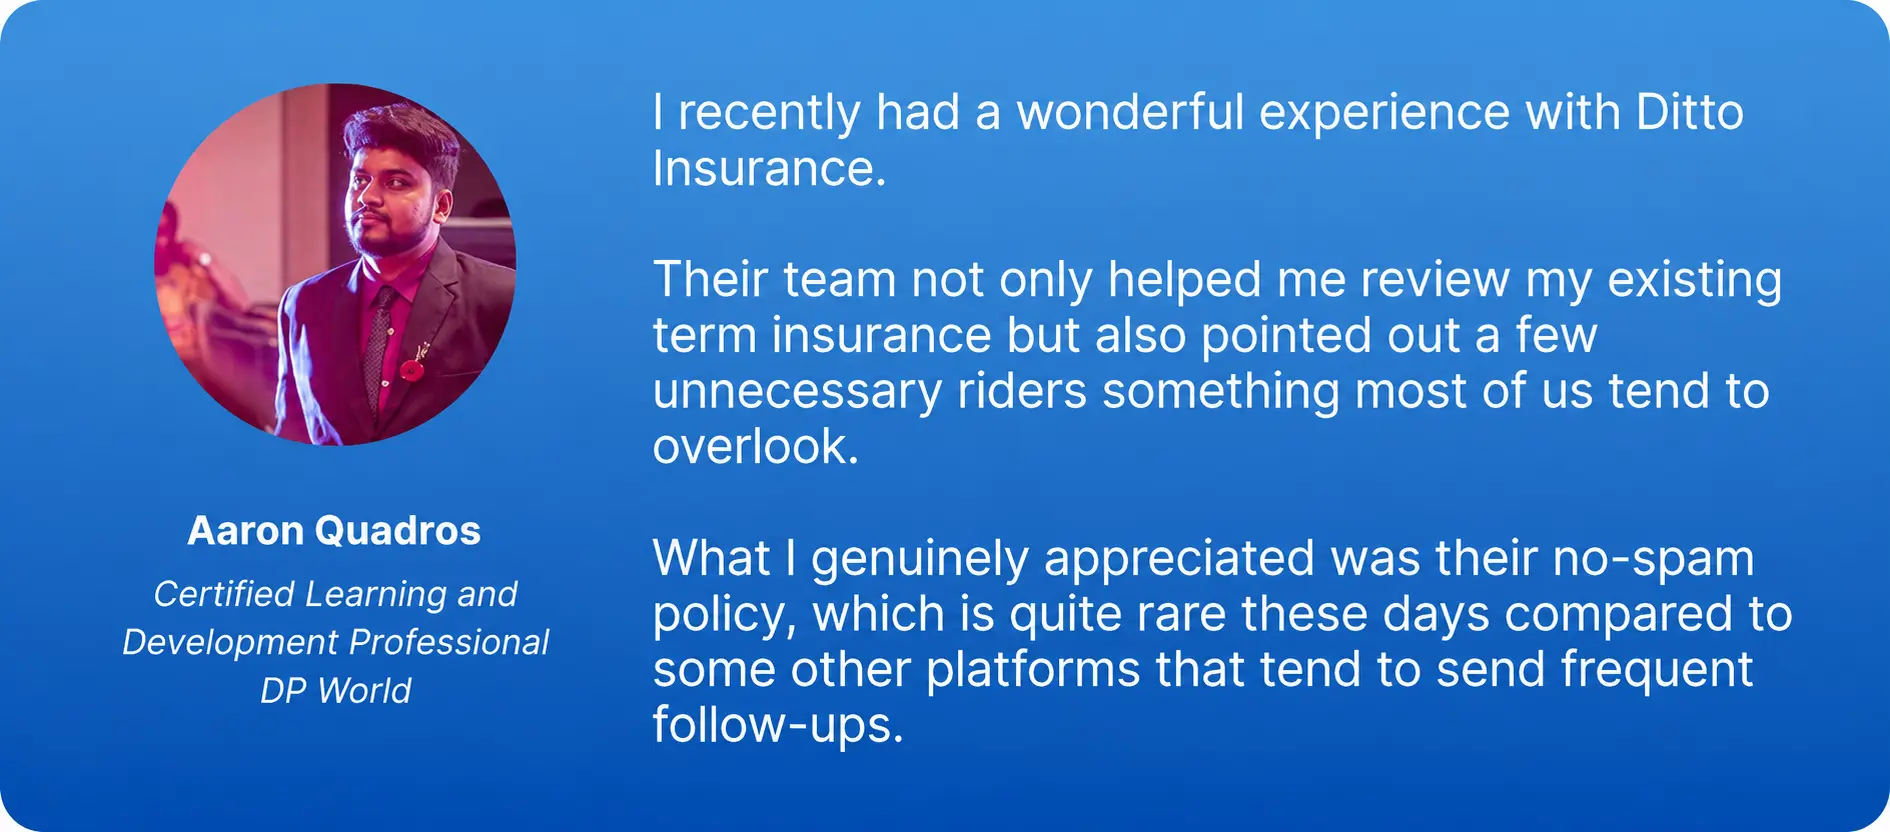
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Senior citizens above 65 years usually do not get access to the best term insurance plans. However, there can be alternatives. Group term insurance and group credit life cover can be considered if individual term insurance is unavailable or unsuitable after age 65. These plans may offer higher entry ages, although eligibility depends on the group type and insurer’s terms.
For example, HDFC Life Group Term Life allows entry up to age 79 for employer-employee groups and 69 for other groups. Canara HSBC Group Term Edge permits entry up to 80, while Bajaj Life Group Term Life allows entry up to 79 for employer-employee groups and 69 for other groups.
These are master policy or group arrangements, not individual retail plans. You must qualify through an employer, association, lender, or other eligible group. You cannot buy them independently as a substitute for a retail term insurance policy.
If you cannot find a term insurance plan after 70, other life insurance for senior citizens can be worth considering. Annuity or pension plans can provide regular income throughout retirement, depending on the product and your financial needs. Explore the Ditto guide for senior citizens for more clarity.
Frequently Asked Questions
Last updated on: