

Overview
Holding a public office can bring greater financial scrutiny, including when you apply for term insurance. Politically Exposed Persons (PEPs) may face additional checks during underwriting, but that does not automatically make them ineligible for life cover.
If you are a PEP or a close associate of one, understanding the insurer’s requirements can help you prepare the right documents and avoid delays.
This guide explains the eligibility requirements for term insurance for Politically Exposed Persons (PEPs), additional checks, and documents they may need when applying for term insurance in India.
Who Counts as a Politically Exposed Person for Term Insurance in India?
According to an RBI master direction, “Politically Exposed Persons” (PEPs) are individuals who hold or have held prominent public positions in a foreign country.
This includes heads of state or government, senior politicians, government, judicial, or military officials, senior executives of state-owned corporations, and key political party officials.
The statutory PEP definition under the Prevention of Money Laundering (PML) framework focuses on prominent public functions entrusted by a foreign country. However, insurers apply a broader definition of PEPs. This can include individuals who hold or have held prominent public positions in India or abroad, such as ministers, senior politicians, government officials, judges, and military officers.
For instance, as per Axis Max Life, the definition also covers senior executives of state-owned corporations, key political party officials, and their immediate family members. This can include spouses, children, parents, siblings, and in-laws, depending on the insurer’s policy.
Note: According to an IRDAI master circular, insurers classify politically exposed persons as high-risk profiles. Therefore, they must apply enhanced due diligence, KYC, and underwriting procedures, which may involve additional verification and cross-checks before issuing a policy.
Talk to an expert
today and
find
the right
insurance for you.
Term Insurance for Politically Exposed Persons: Eligibility and Underwriting
Politically Exposed Persons (PEPs) can generally apply for term insurance in India. IRDAI does not prescribe separate age, policy term, or sum assured limits solely based on PEP status. The insurer’s decision depends on the applicant’s eligibility, health, finances, and verification of their PEP status and sources of funds and wealth.
IRDAI requires senior management to scrutinise PEP proposals and conduct enhanced due diligence throughout the business relationship. Depending on the case, insurers may request additional tax returns, bank statements, audited financial statements, business records, or other supporting documents. They also conduct enhanced KYC checks and assess the source of funds and wealth.
Plans Available
- Axis Max Life Smart Term Plan Plus: This plan offers several protection features, including an optional critical illness rider that covers up to 64 illnesses for 20 years. Smart Term Plan Plus also includes an built-in accelerated terminal illness benefit of up to ₹1 crore, payable early after a qualifying diagnosis.
- HDFC Life Click 2 Protect Supreme Plus: This plan offers flexible cover options for major life events. Click 2 Protect Supreme Plus offers a Life Stage Benefit that lets eligible policyholders increase their cover after marriage or childbirth without a fresh application. The optional critical illness rider covers up to 60 illnesses for 15 years.
- ICICI Life iProtect Smart Plus: This plan offers flexibility through its Premium Break feature, which lets eligible policyholders defer premium payments for up to 12 months after completing the required payment period. iProtect Smart Plus also provides an instant partial payout of up to ₹3 lakh for eligible high sum assured policies.
- Bajaj Life eTouch II: This plan offers an built-in terminal illness benefit of up to ₹2 crore. eTouch II also provides an built-in waiver of premium option for covered events, such as accidental disability. The benefit is subject to the applicable policy and rider terms.
- Aditya Birla Sun Life Super Term Plan: This plan offers an optional accelerated critical illness benefit covering 42 illnesses. Super Term Plan can pay up to 50% of the sum assured, subject to applicable limits. Eligible policyholders also receive an built-in terminal illness benefit of up to ₹1 crore.
Does Being a PEP Affect Term Insurance Plan Options?
IRDAI does not prescribe specific term insurance plans for PEPs. There is also no blanket rule that limits PEPs to a fixed sum assured or prevents them from purchasing term insurance online.
However, insurers may restrict the coverage amount or offer modified terms based on their underwriting assessment. The options available will depend on the applicant’s profile and the insurer’s risk assessment.
How Does PEP Status Affect Term Insurance Premiums?
These annual premiums are for non-smoking applicants in Delhi (pincode: 110010) seeking ₹2 crore cover until age 65. They exclude first-year discounts. Use the Ditto term insurance premium calculator to get an estimate based on your details.
Note: These figures are indicative. Actual premiums depend on the applicant’s health profile, underwriting assessment, and insurer-specific terms. Insurers may apply premium loadings of 10% to 100%, depending on their risk assessment.
Medical Tests and Documents Required for PEPs
PEPs need the same medical tests as other applicants, based on their age, requested coverage, health disclosures, medical history, and the insurer’s underwriting criteria.
Documents Required for PEPs
Besides the usual documents required for term insurance, IRDAI has not prescribed a standard document checklist specifically for PEPs.
IRDAI sets the anti-money laundering requirements, while each insurer decides how to apply them during underwriting.
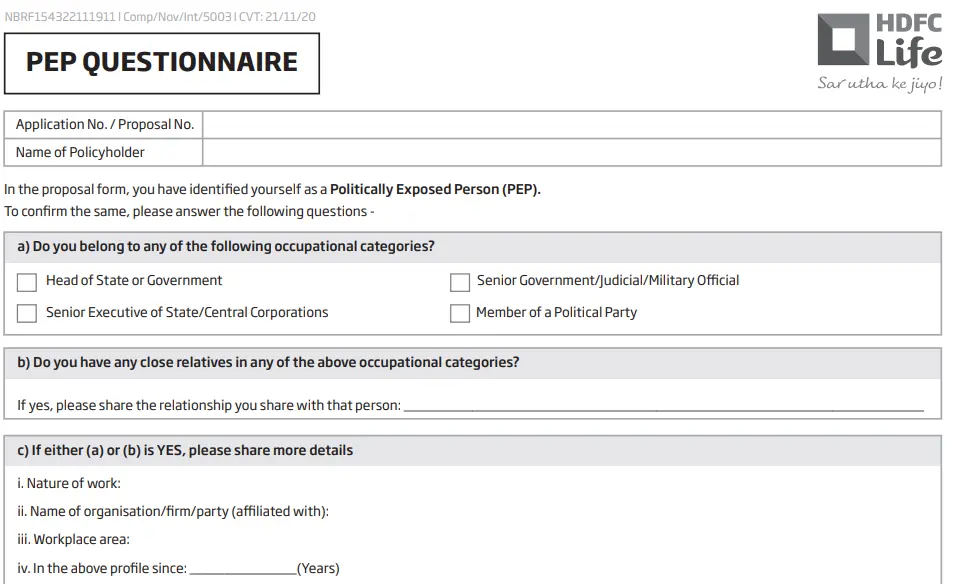
For example, HDFC Life has a separate category for High-Risk Individuals (HRI) and PEPs. It accepts several types of financial documents to verify the applicant’s income and source of funds. The insurer has a separate questionnaire for PEPs.
Purpose
Occupational Categories
Family Relationships
Applicant Details
Here’s a snippet from the HDFC Life PEP questionnaire the insurer uses for underwriting.
Why Choose Ditto for Term Insurance?
At Ditto, we’ve assisted over 12,00,000 people with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
You can book a FREE consultation. Slots are running out, so make sure you book a call or chat on WhatsApp now!
Conclusion
Insurers may conduct enhanced underwriting checks for PEPs. These can include verifying the source of funds and assessing any specific threats to the applicant’s life, including risks linked to their public position.
In our experience at Ditto over the past 6 to 12 months, most PEP-related cases involved applicants whose parents or grandparents had links to local political parties or gram panchayats. Insurers generally did not raise significant concerns when these relatives held no prominent public position.
However, we have not yet handled enough applications from senior political figures or high-ranking officials to draw conclusions about their underwriting experience.
Ultimately, PEP status does not automatically prevent you from getting term insurance. The insurer’s decision depends on your position, financial background, risk profile, and the outcome of its due diligence.
Frequently Asked Questions
Last updated on: