

Overview
Farmers face unique challenges when buying term insurance. Seasonal income, limited income documentation, and occupational risks can make it harder to qualify for private plans. However, these barriers do not mean life insurance is out of reach.
For farmers who struggle to qualify for private cover, government-backed schemes offer options like PMJJBY. According to the Press Information Bureau, PMJJBY had 26.79 crore beneficiaries and 12.55 crore active policies as of 18 February 2026, providing an accessible starting point for life protection.
This guide to term insurance for farmers explains available coverage options, government schemes, and eligibility requirements.
Why Do Farmers Need Term Insurance?
- Income Replacement: Farming income depends on weather, crop yields, and market prices. If a farmer dies, a term insurance payout can help the family manage household expenses and maintain financial stability without relying solely on uncertain agricultural income.
- Debt and Loan Protection: Farmers may have outstanding agricultural, Kisan Credit Card (KCC), or equipment loans. A term insurance payout can help the family repay these debts and reduce the risk of selling land or other assets to meet repayments.
- Affordable Financial Protection: Schemes such as Pradhan Mantri Jeevan Jyoti Bima Yojana and Pradhan Mantri Suraksha Bima Yojana offer low-cost life or accident coverage. Farmers should check their eligibility and coverage limits before relying on these schemes alone.
- Protection Beyond Crop Losses: Crop insurance schemes such as Pradhan Mantri Fasal Bima Yojana (PMFBY) cover eligible crop losses, not the farmer’s life. Term insurance provides a separate financial safety net for dependents if the farmer dies during the policy term.
Life Insurance and Accident Protection Options for Farmers
- Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY): Pradhan Mantri Jeevan Jyoti Bima Yojana is a government-backed, annually renewable life insurance scheme that provides ₹2 lakh in death cover. Coverage runs from June 1 to May 31 and can renew until age 55, subject to enrolment and eligibility rules for first-time and re-enrolling subscribers. Death due to causes other than accidents is not covered during the first 30 days after enrolment.
- Pradhan Mantri Suraksha Bima Yojana (PMSBY): Pradhan Mantri Suraksha Bima Yojana is a government-backed accident insurance scheme for eligible account holders. It provides ₹2 lakh for accidental death or total disability and ₹1 lakh for partial disability, subject to scheme conditions.
- Micro Life Insurance Plans: Microinsurance products, including LIC’s Micro Bachat (endowment plan), offer life cover designed for customers with limited budgets. Some group or individual products also provide loan protection, helping eligible families manage outstanding liabilities if the insured person dies.
Note: In addition to term insurance plans, Postal Life Insurance (PLI) and Rural Postal Life Insurance (RPLI) offer life insurance products through India Post. However, they are not exclusively pure term insurance plans, so buyers should review each product’s benefits and conditions before choosing coverage.
Talk to an expert
today and
find
the right
insurance for you.
State-Specific Farmer Life Protection Schemes
- West Bengal (Krishak Bandhu Death Benefit): West Bengal’s Krishak Bandhu scheme provides a one-time benefit of ₹2 lakh to the family of an eligible farmer aged 18–60 who dies, regardless of the cause. This is a state-funded social security benefit, not a conventional term insurance policy the farmer purchases.
- Telangana (Rythu Bima): The scheme provided ₹5 lakh to the family of an enrolled farmer upon death, irrespective of the cause, with the state government paying the premium to LIC. According to The New India Express, for 2025–26, Telangana reported 42.16 lakh enrolled farmers and ₹1,004.35 crore paid to 20,087 bereaved families.
Note: According to Telangana Today, reports indicate that the policy period ended on 14 August 2026, and the 2026–27 renewal premium had not been paid at the time of reporting. Farmers should verify the scheme’s current status before relying on this benefit.
Why Can Farmers Find It Difficult to Get Private Term Insurance?
Many private insurers can restrict access to their flagship or comprehensive term insurance plans for farmers. Some underwriting guidelines limit applications from people with agricultural income or certain agricultural profiles.
One key challenge is income verification. Farming income often varies with crop yields, market prices, and weather conditions. Seasonal earnings and limited financial records can make it harder for insurers to assess income stability and decide how much cover an applicant can afford.
Occupational risks also affect underwriting decisions for term insurance for farmers. Farmers may face machinery accidents, pesticide exposure, extreme weather, and other work-related hazards. Insurers assess these risks alongside the applicant’s health, income, and financial background when deciding whether to offer cover and on what terms.
However, this does not mean every farmer is automatically ineligible for life insurance.
Note: Farmers can also explore Saral Jeevan Bima, a standardized term insurance product offered by life insurers. It provides access to smaller life covers, although eligibility and underwriting requirements vary by insurer.
Additionally, the Bandhan Life Rural Term Plan offers basic life cover for a five-year term through a single premium of ₹300 to ₹1,000, subject to the minimum sum assured. Farmers should check the plan’s current availability, eligibility requirements, and coverage limits before applying.
Farmers in rural areas can also approach LIC or SBI Life to explore suitable options. Approval depends on the insurer’s assessment of their income, occupation, health, and supporting documents.
Sample Premiums for Farmers by Age and Cover
Private insurers do not offer standard term plans to every farmer, so premium estimates for their flagship products are not available. Actual eligibility and pricing depend on the insurer’s underwriting assessment, the applicant’s occupation, and income.
Government-backed schemes offer affordable alternatives. PMJJBY costs ₹436 per year for ₹2 lakh life cover, while PMSBY costs ₹20 per year for accident cover of up to ₹2 lakh, subject to eligibility and scheme terms.
Term Insurance for Farmers: Eligibility and Documents Required
1. Pradhan Mantri Jeevan Jyoti Bima Yojana
Eligibility Criteria
- Age: 18 to 50 years of enrolment, and coverage can continue until age 55 through annual renewal, subject to scheme rules.
- Bank or Post Office Account: You need an individual savings account with a participating bank or post office.
Documents Required
- Aadhaar card or other documents accepted by the participating institution.
- Signed consent-cum-auto-debit authorization form.
- Bank or post office account details.
- Nominee details, including name and relationship.
2. Pradhan Mantri Suraksha Bima Yojana
Eligibility Criteria
- Age: 18 to 70 years.
- Bank or Post Office Account: You need an eligible individual savings account with a participating institution. Institutional accounts are not eligible.
- Joint Accounts: Each eligible account holder can enroll separately and pay the annual premium.
Documents Required
- Aadhaar card or another accepted identity document.
- Government-issued photo identification, if requested.
- Bank account details.
- Nominee details.
Note: Check the latest scheme guidelines with your bank or post office before applying, as enrolment procedures and document requirements may vary by institution.
Common Challenges Farmers Face When Buying Term Insurance
Missed Auto-Debit Payments
Government-backed insurance schemes often rely on automatic premium deductions from a linked bank account. If the balance is insufficient on the deduction date, coverage may lapse, leaving the farmer’s family without the expected protection.
Educational Requirements
Farmers with limited formal education face challenges in meeting insurers’ eligibility criteria or completing documentation.
Tenant and Sharecropper Status
Tenant farmers and sharecroppers may earn their livelihood through agriculture without owning the land they cultivate. If land records do not carry their names, proving agricultural income and meeting an insurer’s financial documentation requirements can become more difficult.
Insufficient Coverage
PMJJBY provides ₹2 lakh in life cover, while some state schemes offer additional benefits. However, these amounts fall short of a family’s long-term expenses, outstanding farm loans, and other financial responsibilities after the farmer’s death.
Age Restrictions and Higher Premiums
Farmers who consider life insurance later in life may face limited options. New enrolment in PMJJBY is restricted to eligible individuals aged 18 to 50.
Confusion Between Insurance Products
Farmers may confuse crop insurance, accident cover, pension schemes, loan protection, and term life insurance. Each serves a different purpose, so understanding what a policy covers is essential to avoid gaps in financial protection.
Note: Based on Ditto’s experience, educational requirements, income documentation, and occupational risks make it harder for some farmers to obtain term insurance. However, these challenges do not apply to every farmer, and eligibility depends on the insurer’s underwriting assessment.
How Much Term Insurance Cover Do Farmers Need?
Farmers should choose term insurance based on their family’s expenses, outstanding farm loans, dependents, and future goals. Seasonal income makes it important to plan for financial uncertainty.
The Ditto cover calculator can help estimate suitable coverage based on your financial responsibilities. Review the amount alongside your monthly expenses and outstanding loans.
Why Choose Ditto for Term Insurance?
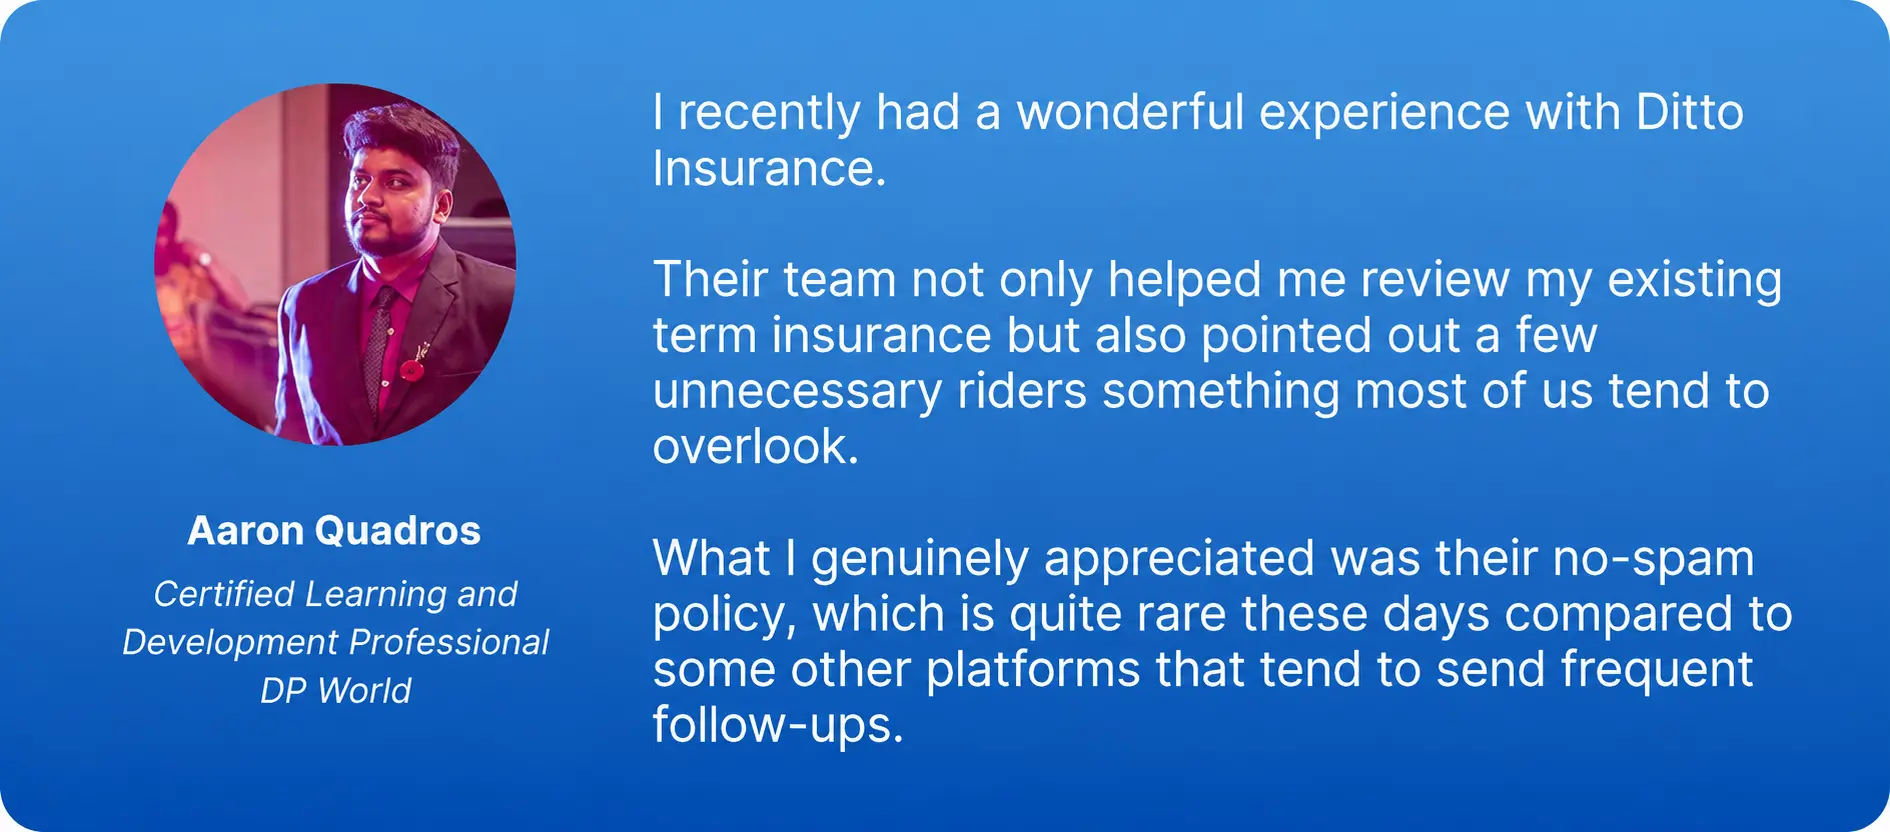
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Large-scale farmers and corporate farmers with organized operations, documented income, and clear financial records may have access to a wider range of term insurance plans. They can explore comprehensive coverage options, subject to the insurer’s underwriting assessment.
Farmers who lack conventional income documents can also check plans that may not require standard income proof, such as ICICI Life iProtect Super and Bajaj Life iSecure II. However, eligibility and documentation requirements vary by insurer, and approval is never guaranteed.
In most cases, farmers should approach insurers directly, explain their occupation and income sources, and disclose all relevant details in the proposal form. They can then compare plans based on coverage, premiums, exclusions, and policy terms before deciding.
Frequently Asked Questions
Last updated on: