Term Insurance

HDFC Life CSC Suraksha Plan: Rural Cover Review

Subhashish Banerjee

Written by Subhashish Banerjee

Insurance Writer

Gaurav Bhat

Reviewed by Gaurav Bhat

IRDAI-Certified Expert at Ditto

SP0738578124

Certified
HDFC Life CSC Suraksha Plan: Rural Cover Review

Overview

The HDFC Life CSC Suraksha Plan was a non-linked, non-participating term insurance plan designed to make basic life insurance more accessible through the Common Services Centre (CSC) network, particularly in rural and underserved markets. 

Plan Overview

  • Sum Assured: ₹30,000 to ₹2,00,000
  • Entry Age: 18 years to 55 years

Key Features

  • Death Benefit: If the insured dies during the policy term, the nominee receives the chosen sum assured.
  • Policy Term: Policyholders can choose a term between 5 and 15 years.
  • Tax Benefits: Premiums may qualify for tax benefits under applicable provisions of the Income Tax Act.

Important Conditions

  • No Maturity Benefit: The plan does not pay anything if the insured survives the policy term.
  • No Surrender Value: The plan does not provide a maturity corpus or savings component.
  • No Policy Loan: The policy does not provide a loan facility against the policy.

According to a HDFC Life 2015 media release, the insurer launched CSC Suraksha as a basic, low-ticket term insurance product built around accessibility rather than high life cover. Its relatively small sum assured means it was viewed as an entry-level protection product, not as a substitute for adequate individual term insurance for a family's long-term financial needs.

This guide explains the HDFC Life CSC Suraksha Plan, including its features, eligibility, coverage, premiums, and current status as a withdrawn product.

What Is the HDFC Life CSC Suraksha Plan?

The HDFC Life CSC Suraksha Plan was a pure-protection individual term insurance policy. It was not a savings or investment product. 

The plan provided life cover for a defined policy term, with no maturity benefit if the insured survived the policy period.

What made the plan different was its distribution model. It was designed to be sold through India's Common Services Centre (CSC) network, with a focus on improving access to basic life insurance in rural and semi-urban markets. The plan was issued under UIN 101N104V01 and later UIN 101N104V02. The insurer’s list of withdrawn plans currently includes both versions.

The plan is no longer available for fresh purchase, so this page is primarily intended for existing policyholders, nominees, and readers researching the discontinued HDFC Life CSC Suraksha Plan.

Take Note: HDFC Life's website currently states that the CSC Suraksha product is being updated. Therefore, product features, availability, or terms may change. Check the insurer's latest product information before relying on the historical details discussed here.
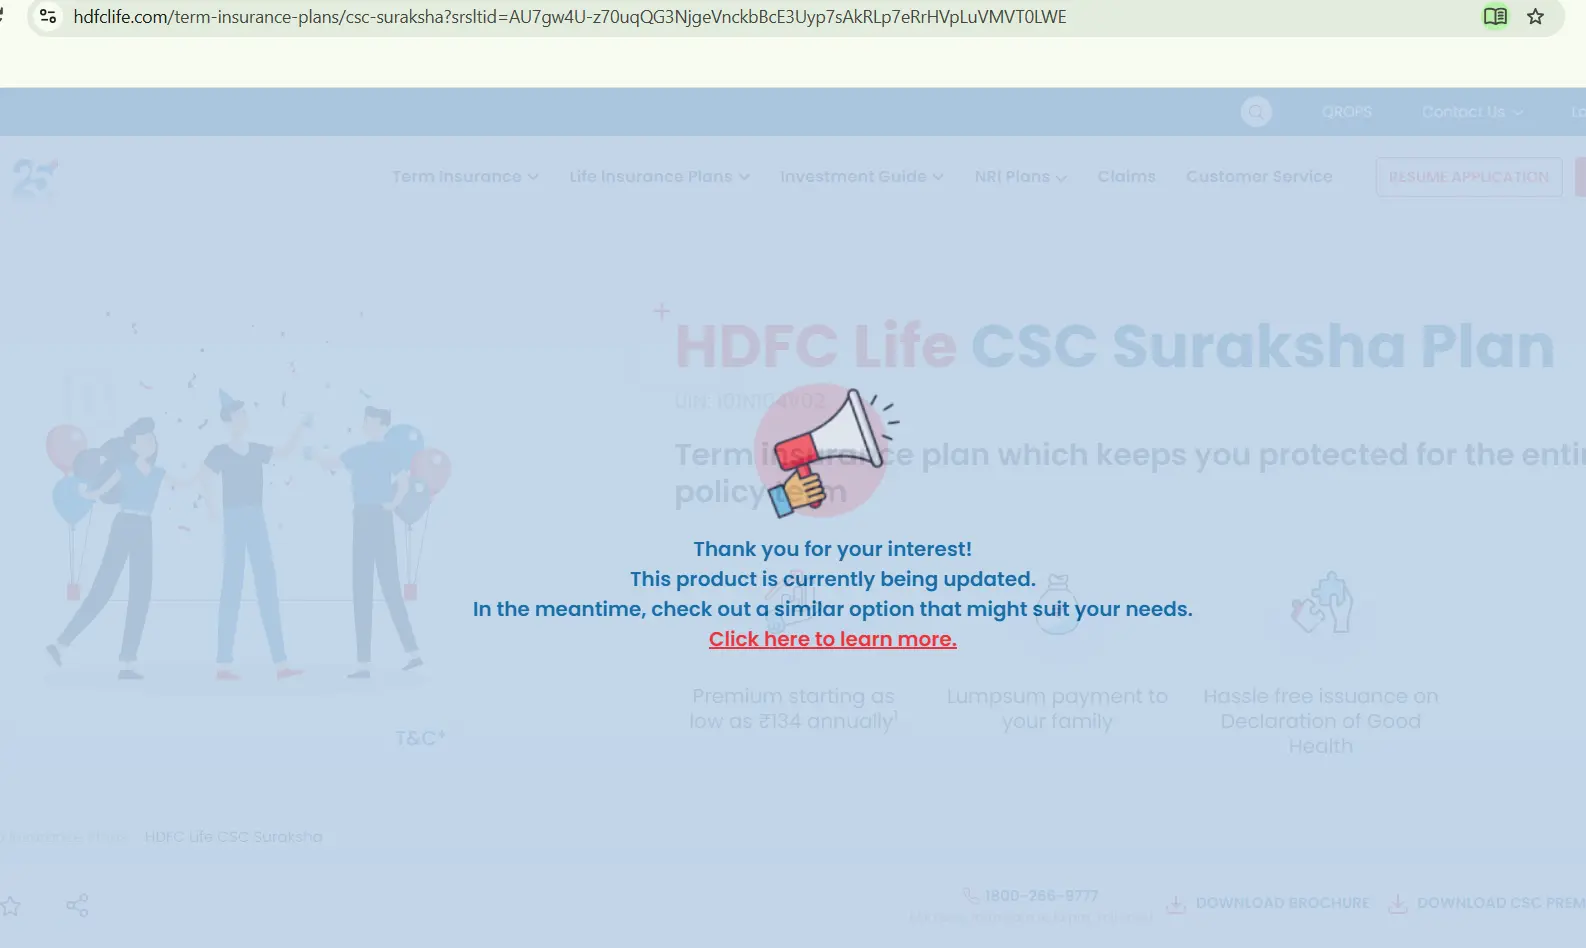
HDFC Life CSC Suraksha Plan page states the product is currently being updated and directs users to a similar option like Click 2 Protect Supreme Plus.

Talk to an expert
today and find
the right
insurance for you.
Ditto Advisor

Key Features of the HDFC Life CSC Suraksha Plan

    • Death Benefit: If the life assured dies before the maturity date, the nominee/family receives the chosen sum assured, subject to the policy terms.
    • No Maturity or Surrender Benefit: No benefit is payable if the life assured survives the policy term or if the policy is surrendered before maturity.
    • No Policy Loans: The plan does not offer any loan facility against the policy.
    • Tax Benefits: Eligible premiums may qualify for deductions under Section 123 (previously Section 80C) under the old regime. Death benefits remain tax-exempt under Section 11, previously Section 10(10D). 

Eligibility & Documents Required for HDFC Life CSC Suraksha Plan

ParameterCriteria
Premium Payment Term (PPT)Regular pay
Entry Age18 years to 55 years
Policy Term5 years to 15 years
Premium Payment ModesYearly, half-yearly, quarterly, and monthly
Sum Assured ₹30,000 to ₹2 lakh

Take Note: For the plan, applicants had to submit the basic documents required for term insurance. These included proposal form, age and identity proof, address proof, PAN or Form 60 where applicable, nominee details, and a Declaration of Good Health, subject to prevailing KYC requirements.

HDFC Life CSC Suraksha Sample Premiums 

Since HDFC Life has withdrawn the CSC Suraksha Plan and is updating its official page, current premium quotes are no longer available for new purchases. Any sample premiums shown for this plan should therefore be treated as historical illustrations, not current prices.

Historical Illustration: HDFC’s older product filing listed a rate of ₹4.46 per ₹1,000 of cover for a 30-year-old female with a 10-year policy term. For ₹30,000 of coverage, this worked out to ₹133.80 annually, before applicable taxes and cess at the time. 

CSC Suraksha has since been withdrawn, so this is not a current quote.

The actual premium would have varied based on factors such as the policyholder's age, sum assured, policy term, and applicable product rates at the time. If you wish to get a rough estimate of flagship plans offered by the insurer like Click 2 Protect Supreme Plus, use the Ditto premium calculator.

HDFC Life: Performance Metrics

Metric (Average FY 2024-26)HDFC LifeIndustry Average
Claim Settlement Ratio (CSR)99.66%99.00% (Mean)
Amount Settlement Ratio (ASR) (Average FY 2023-25)96.72%94.83% (Mean)
Annual Business Volume (In Crore)₹33,030.87₹3,778.58 (Median)
Volume of Complaints (Per 10,000 Claims)1.0013.10 (Median)
Solvency Ratio1.86x2.00x (Median)
Annual Death Claims Paid (In Crore)₹1,901.70₹237.24 (Median) 

Note: The data in the table has been derived from HDFC Life’s public disclosures and IRDAI annual reports. For more insurer metrics, explore Ditto Data Lab. These figures reflect overall performance across HDFC Life insurance plans and offerings. 

HDFC Life CSC Suraksha vs. PMJJBY and Regular Term Insurance

FactorHDFC Life CSC SurakshaPradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY)Regular Retail Term Insurance
Current AvailabilityWithdrawn in September 2024 and no longer available for new purchasesActive government-backed annual term insurance schemeActive and available from multiple private life insurers
StructureIndividual term insurance plan distributed through the CSC networkGovernment social security group term insurance schemeIndividual term insurance policy purchased directly by the policyholder
Target MarketDesigned for rural and semi-urban customers using CSC servicesDesigned for broad financial inclusion among eligible individualsDesigned for individuals seeking substantial income replacement for dependents and liability protection.
CoverOffered relatively small life cover from ₹30,000 to ₹2 lakhPMJJBY provides a fixed life cover of ₹2 lakhTypically offers coverage of several tens of lakhs to multiple crores

Take Note: The CSC Suraksha Plan offered a relatively low level of life cover, which may not be enough to protect a family's long-term financial needs. The right sum assured depends on factors such as current liabilities, household expenses, inflation, future financial goals, and the number of dependents. 

Use the Ditto cover calculator to estimate the life cover you may need.

Why Choose Ditto for Term Insurance?

At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
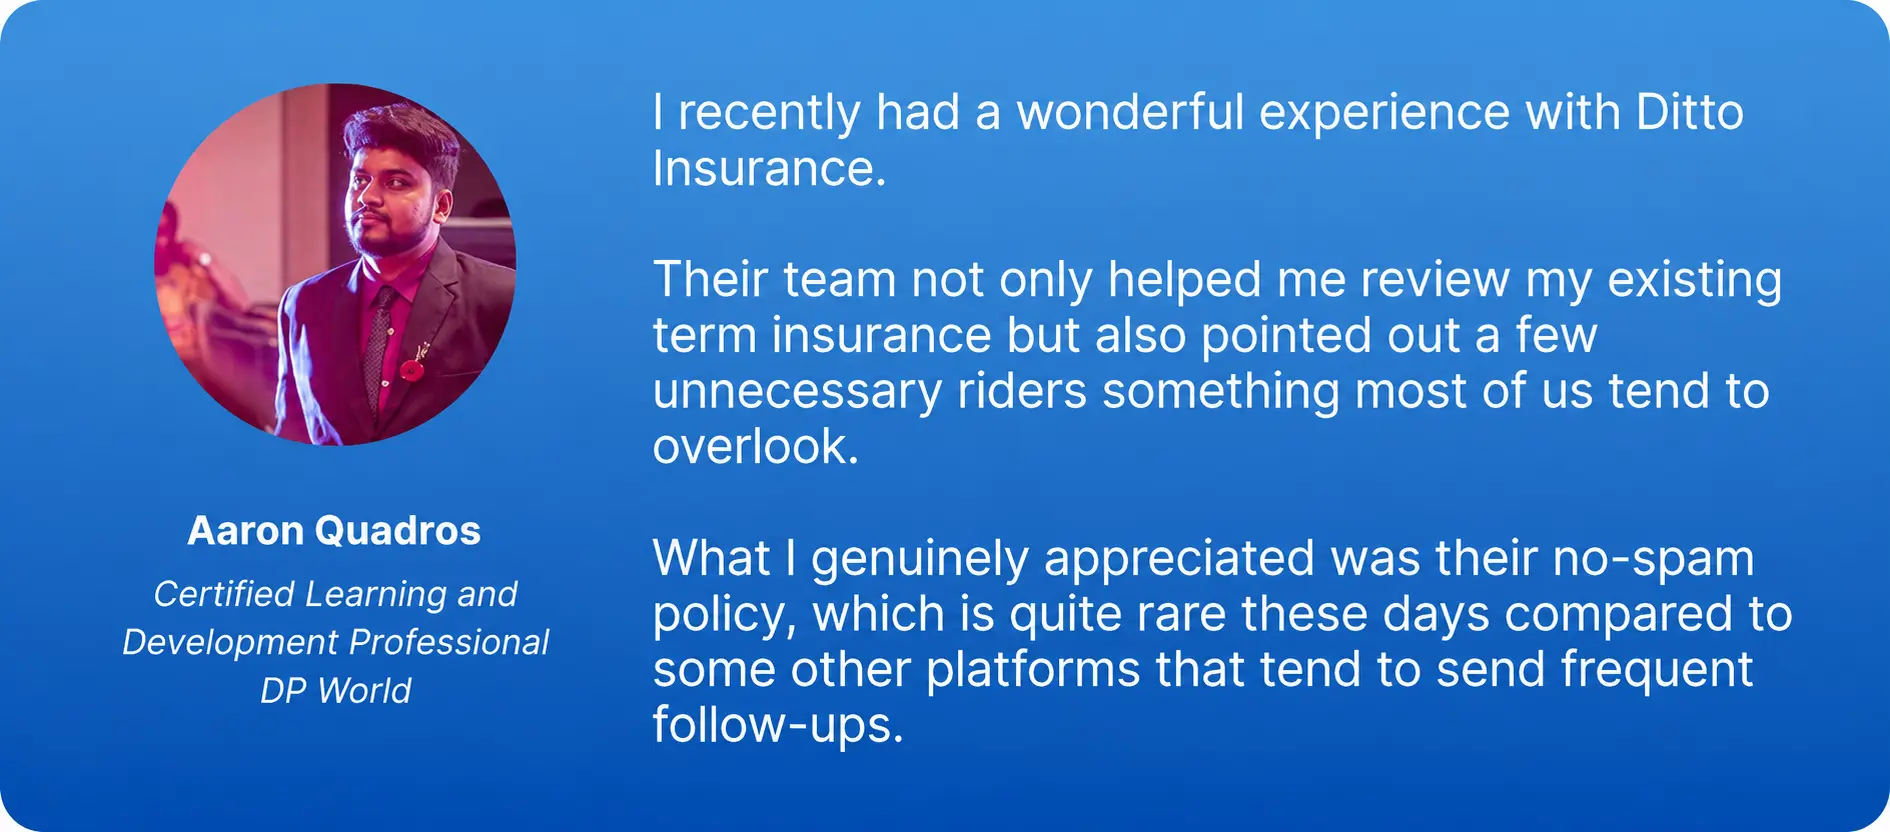
Aaron Quadros LinkedIn Testimonial
    • 100% Free Consultation
    • No Spam. No Sales Pressure.
    • Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
    • Backed by Zerodha
    • Dedicated Claim Support Team
    • Compare Plans and Premiums with a Trusted Insurance Advisor

Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!

Conclusion

HDFC Life CSC Suraksha was essentially a bridge between financial inclusion-focused insurance and conventional private term insurance. However, its relatively low sum assured meant it was never designed to replace a conventional term plan with substantial life cover.

If you prefer HDFC Life as your insurer, explore other HDFC Life term insurance plans like Click 2 Protect Supreme Plus, which offers a more comprehensive term insurance structure with greater scope for customization. It is one of the best term insurance plans in India for those seeking substantial financial protection.

Disclaimer: This article is based on publicly available information and sources available at the time of research. For further clarification, contact the HDFC Life customer care directly and refer to the latest policy documents and terms and conditions. 

Frequently Asked Questions

Who could buy the HDFC Life CSC Suraksha Plan through a Common Services Centre?

Historically, HDFC Life CSC Suraksha was distributed through Common Services Centres, mainly targeting customers in rural and semi-urban areas. Eligibility depended on the plan's entry age, policy conditions, and applicable requirements at the time. However, the plan was withdrawn in 2024 and is no longer available for new purchases.

What was the maximum sum assured available under the HDFC Life CSC Suraksha Plan?

The HDFC Life CSC Suraksha Plan historically offered a sum assured ranging from ₹30,000 to ₹2 lakh. This relatively small cover was intended to provide basic life protection. It was not structured as a high-value income replacement plan. Since the product was withdrawn in 2024, these figures are relevant only to its earlier availability.

Did the HDFC Life CSC Suraksha Plan require a medical test before enrollment?

The plan was designed with simplified issuance and could be offered using a declaration of good health, subject to the insurer's eligibility and underwriting requirements. A medical examination was not necessarily required for every applicant. Since the product has been withdrawn, prospective buyers should refer to currently available products for their present medical underwriting requirements.

How could a nominee file a claim under the HDFC Life CSC Suraksha Plan in a rural area?

A nominee can notify HDFC Life of the death claim and submit the required documents through the insurer's designated servicing channels. Under the V02 policy, servicing and grievance assistance are also available through the designated Rural Authorized Person (RAP).

Was HDFC Life CSC Suraksha better value than the ₹436 PMJJBY cover?

The two products had different structures and coverage levels. CSC Suraksha historically offered individual term insurance with sum assured options up to ₹2 lakh, while PMJJBY provides ₹2 lakh of life cover for its applicable annual premium. Comparing value requires considering eligibility, premium, policy terms, exclusions, and the specific protection required.

Could I pay HDFC Life CSC Suraksha premiums monthly at the CSC counter?

HDFC Life CSC Suraksha was distributed through Common Services Centres, but premium payment options depended on the product's prescribed payment structure and service process. You should not assume monthly payments were available at every CSC counter. Since the plan was withdrawn in 2024, new monthly payment arrangements are no longer applicable.

Was the HDFC Life CSC Suraksha Plan enough cover for a family dependent on farm income?

For a family that depends heavily on one person's farm income, the historical ₹30,000 to ₹2 lakh cover may have provided basic financial support, but it was limited compared with potential long-term income needs. Families should assess liabilities, household expenses, dependents, and future goals when deciding how much life insurance they need.

What did the suicide exclusion cover under HDFC Life CSC Suraksha?

If the life assured died by suicide within 12 months of commencement of risk or revival, the policy paid at least 80% of total premiums paid or the available surrender value, whichever was higher, subject to the policy being in force. Because the plan had no surrender value, the premium-based amount generally applied. After 12 months, the special suicide provision no longer applied.

What is HDFC Life’s claim settlement ratio?

The HDFC Life claim settlement ratio averaged 99.66% for FY 2024-26, compared with the 99.00% industry average. In FY 2025-26, HDFC Life reported a 99.72% claim settlement ratio. This means HDFC Life settled a high proportion of reported claims during the period.

Last updated on: