

Overview
LIC and SBI Life are two of India's largest life insurers, with both companies publicly listed and backed by major institutions. While LIC leads on scale, distribution reach, and legacy, SBI Life offers strong private-sector capabilities and digital infrastructure.
This guide walks you through SBI Life vs LIC, comparing term plans, features, premiums, riders, claim settlement, and key differences to help you choose confidently.
LIC vs SBI Life: Insurer Comparison
Talk to an expert
today and
find
the right
insurance for you.
LIC vs SBI Life: Plans and Sample Premiums
Plans Offered
- LIC: The insurer offers plans like New Tech Term, Jeevan Raksha, and Bima Kavach.
- SBI Life: Their offerings include Smart Shield Plus, Smart Shield Premier, and eShield Insta.
1) LIC Bima Kavach vs SBI Smart Shield Premier
Bima Kavach offers level and increasing cover options. Its level sum assured with regular pay option includes a life stage benefit, subject to an entry age of 40 years or below. The death benefit can be paid as a lump sum or in installments. An accident benefit rider is also available.
SBI Life Smart Shield Premier offers level and increasing cover. Under the increasing cover option, the sum assured rises by 10% of the base cover every five policy years, up to a 100% increase, with increases stopping at age 71. Death benefits can be paid as a lump sum, installments, or both. Its accident benefit rider offers Accidental Death Benefit (ADB) under Option A and Accidental Partial Permanent Disability (APPD) under Option B.
Sample Premiums
Note: The annual premiums are for a non-smoker, male profile for a ₹2 crore level term cover with a policy term of 20 years. The figures for LIC are derived from the official brochure.
You can also explore the SBI Smart Shield Premier official brochure for sample premiums. These are indicative premiums, and final figures will vary with factors like age, sum assured, and underwriting. Bima Kavach costs more than Smart Shield Premier for comparable coverage and policy terms.
2) LIC New Tech Term vs SBI Life Smart Shield Plus
LIC New Tech-Term offers level and increasing sum assured options to suit different coverage needs. Policyholders can choose to receive the death benefit as a lump sum or in installments. The plan also offers an accident benefit rider for additional protection against accidental death, subject to policy terms.
SBI Life Smart Shield Plus offers level and increasing sum assured options, along with a Level Cover with Future Proofing option to increase life cover. It also provides an optional Better Half Benefit for spouse cover. Death benefits can be paid as a lump sum, installments, or a combination of both. Available riders include ADB and APPD, subject to policy terms.
Sample Premiums
Note: The annual premiums shown are for a non-smoking male seeking ₹1 crore of level term cover for a 20-year policy term. LIC figures are based on its official brochure. These are indicative figures. Actual premiums may vary based on age, sum assured, underwriting, and other factors. LIC New Tech Term costs less than Smart Shield Plus for comparable coverage and policy terms.
3) LIC Jeevan Raksha vs SBI Life eSHIELD INSTA
Jeevan Raksha is a pure-risk term insurance plan that provides life cover throughout the policy term. The death benefit protects your family's finances if you die during the policy period. Depending on the selected payout option, the death benefit can be paid as a lump sum or in installments, subject to policy conditions. You can review the policy brochure for rough premium estimates.
SBI Life eShield Insta is a non-linked, non-participating life insurance product with pure risk protection and return of premium benefits. It focuses on simplicity, with digital onboarding and a fixed 10-year policy term. Plan A provides pure term insurance, while Plan B offers term insurance with return of premium (Base premiums are returned with no interest earned). Explore the policy brochure for the premium rate chart.
Ditto’s Key Takeaway: SBI Life’s flagship plan Smart Shield Plus has an edge over LIC New Tech-Term in terms of flexibility. It offers three death payout options, including a combination of lump sum and installments, along with Future Proofing and Better Half Benefit.
LIC vs SBI Life: Performance Metrics
Pros & Cons of LIC
Pros of LIC
- Large Scale: LIC has a dominant market position and one of India's largest life insurance distribution networks.
- Wide Physical Reach: Its extensive branch network offers strong access to offline servicing across India.
- Solvency Ratio: LIC has a 2.15x solvency ratio, higher than SBI Life's 1.94x, indicating a stronger capital buffer relative to regulatory requirements.
Cons of LIC
Limited Rider Benefits
LIC's Accident Benefit Rider mainly provides additional accidental death cover but lacks useful riders like Critical Illness (CI).
No Advanced Features
Term plans lack features like premium break, wellness benefits, instant payout on claim, etc.
Premium May Not Justify the Benefits
Some plans may charge higher premiums without offering proportionate additional features or benefits.
Pros & Cons of SBI Life Insurance
Pros of SBI Life
- Feature-Rich Term Plans: Smart Shield Plus offers features such as Future Proofing, Better Half Benefit, increasing cover, and whole-life cover under specified structures.
- Claim Settlement Ratio: SBI Life has a slightly stronger claim settlement track record than LIC, reflecting consistent claims-paying performance across the insurer's life insurance portfolio.
- Strong Digital Underwriting: SBI Life has invested in digital underwriting and online policy processes, which can improve the purchase experience.
Cons of SBI Life
Feature Conditions
Additional features come with specific eligibility criteria, limits, and policy conditions.
Fewer Modern Features and Riders
The plan offers fewer built-in features and rider options, such as Waiver of Premium (WOP), compared with newer term insurance products.
Volume of Complaints
SBI Life recorded slightly more complaints than LIC for the 3-year period FY 2024-26.
Why Choose Ditto for Term Insurance?
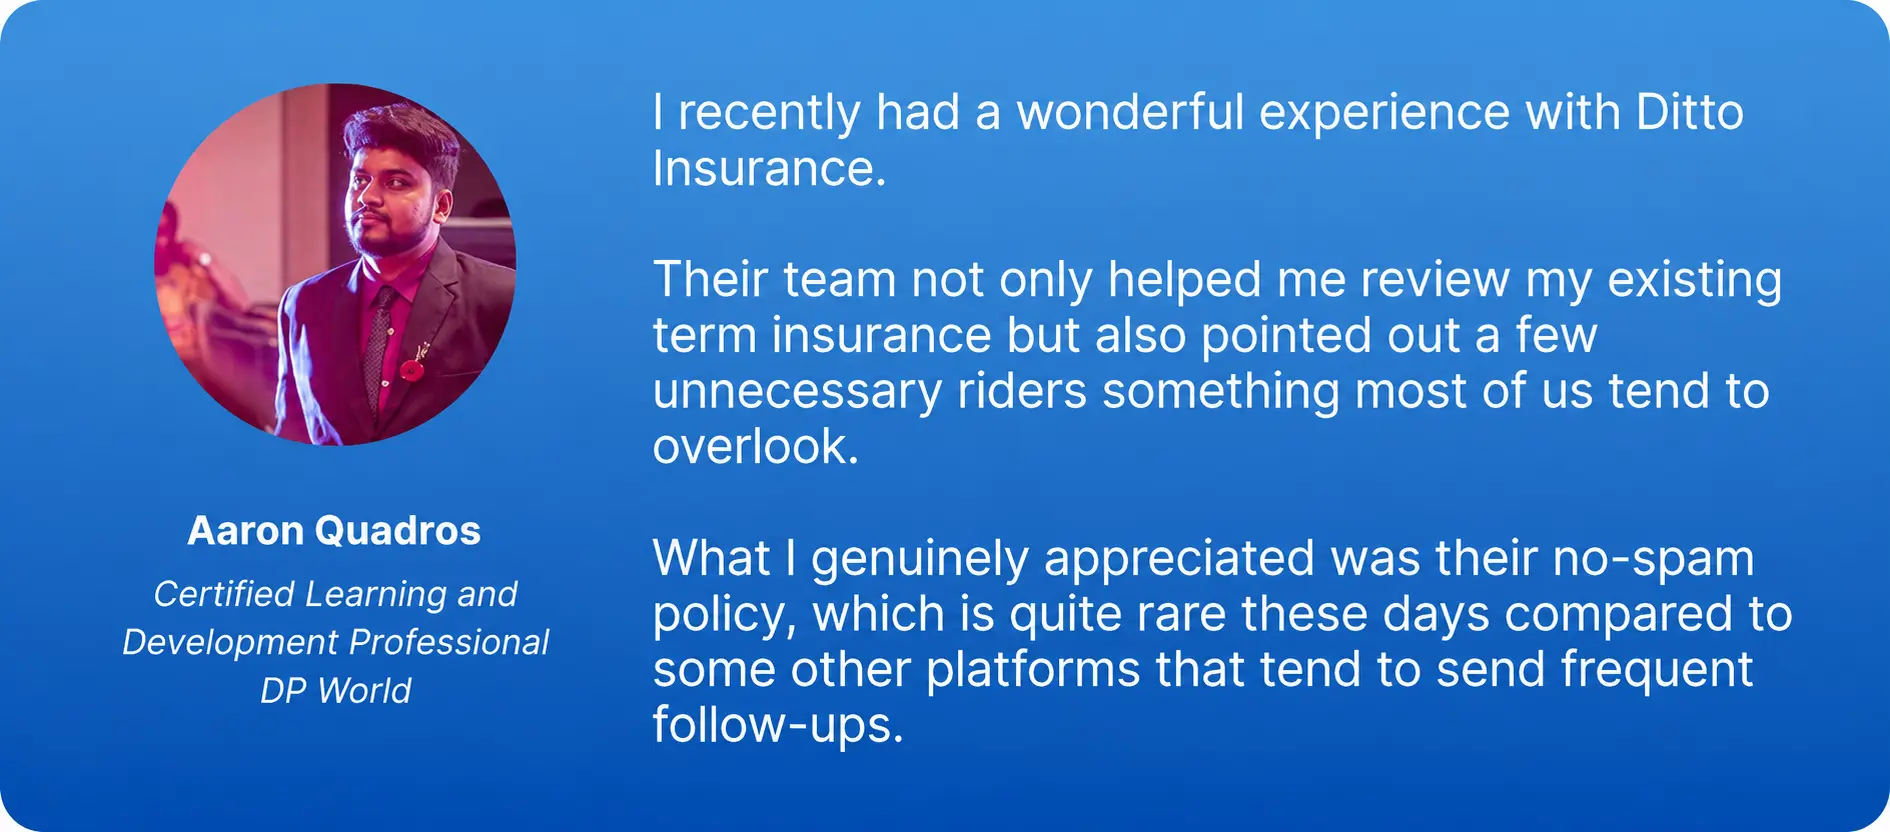
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
When it comes to LIC vs SBI Life insurance, both are large and established insurers. Focus your decision on the policy, not the brand alone. LIC may suit buyers who value physical reach, statutory guarantees, and straightforward term insurance products.
On the other hand, SBI Life may suit buyers who value features such as Future Proofing or Better Half Benefit. However, first compare cover, underwriting terms, policy conditions, and like-for-like premiums.
Both LIC and SBI Life offer term plans that make it to the best term insurance plans list. However, they offer less customization and fewer modern features than some private insurers like Axis Max Life and HDFC Life. Features such as health services, premium breaks, instant partial payouts, and WOP options can provide greater flexibility at competitive premiums.
Frequently Asked Questions
Last updated on: