

Overview
iTerm Elite by Bandhan Life Insurance offers useful features such as Special Exit Value and Cover Continuance. However, gaps in its benefits and changes in the insurer’s financial indicators deserve attention.
This guide covers key plan features, benefits, eligibility criteria, and important terms to help you assess the policy before buying.
Eligibility Criteria for Bandhan Life iTerm Elite
Note: Bandhan Life iTerm Elite is a non-linked, non-participating term insurance plan that offers life cover with flexible premium payment options.
Talk to an expert
today and
find
the right
insurance for you.
Key Features and Riders of Bandhan Life iTerm Elite
Death Benefit
If the life assured dies during the policy term while the policy is active and all due premiums are paid, the nominee receives the applicable death benefit.
Maturity Benefit
The plan offers no maturity benefit under the standard option. If the policyholder survives the policy term, no payout is made unless an eligible exit benefit applies.
Payout Options
At the time of purchase or at the time of claim, the nominee can choose to receive the death benefit as a lump sum, monthly income installments, or 50% as a lump sum and 50% as monthly income.
Insta Claim Assurance
After three policy years, the insurer pays 1% of the death benefit, up to ₹1 lakh, within one working day of death claim registration, subject to mandatory document submission. This amount is deducted from the final payout.
Additional Benefits
1) Gift to Mothers
After completion of one policy year, female policyholders can receive 10% of eligible premiums paid after childbirth or legal adoption. This benefit can be claimed twice, subject to policy conditions, a minimum one-year gap between the two events, and a maximum age limit of 45 years for exercising this benefit.
The eligible benefit is payable upon the first qualifying childbirth or legal adoption, subject to the policy terms.
In the occurrence of the second event (childbirth/adoption), if the benefit has already been claimed once, an additional 10% of eligible premiums paid, including underwriting extra premiums if any, is payable. This amount covers premiums paid between the first and second qualifying events, not all premiums paid over the policy’s history.
2) Cover for Homemakers
Policyholders with a sum assured of at least ₹1 crore can buy additional term cover for their spouse without financial underwriting. This is a separate policy. The cover is capped at 50% of the primary sum assured, up to ₹50 lakh. Medical underwriting applies, and riders are unavailable under the spouse’s policy.
3) Adapt Assure
This feature allows eligible regular pay and limited pay policyholders to increase their base sum assured by 25% to 100% of the original cover or decrease it by 25% to 50% of the prevailing cover, in 5% increments. You can use this feature up to twice during the premium payment term, after three completed policy years.
You may not make changes during the final five premium-paying years, and at least one policy year must pass between changes.
- Cover increases require medical underwriting and additional premiums based on your attained age.
- Cover reductions lower premiums, subject to plan limits.
Approved changes take effect on the next policy anniversary and remain subject to the insurer’s underwriting rules.
4) Special Exit Value (SEV)
Eligible policyholders can recover up to 100% of premiums paid, including underwriting extra premiums, through the Special Exit Value (SEV). Under limited pay, you can receive up to 50% at age 55 and the balance at 65, or the full eligible amount at 65.
Under regular pay, including pay till age 60, you can exit during a one-year window that begins 15 years before maturity. Eligibility requires entry by age 40, a policy term of at least 30 years, and maturity at age 70 or later. Single pay policies are excluded, and any Gift to Mothers payouts reduce the refund.
5) Health Management Services
With this Bandhan Life term insurance plan, you can access services such as medical consultations and international second opinions through the insurer’s registered third-party providers. These services are optional and may be modified, replaced, or withdrawn by the insurer at its discretion.
6) Cover Continuance Benefit
You can defer premiums for up to 12 consecutive months after three policy years while your risk cover continues. You must pay the outstanding premium along with your next due premium. A five-year gap must also apply between successive uses of this benefit.
7) Change in Premium Payment Option
You can switch from regular pay to limited pay only during the first policy year, subject to minimum premium requirements. The revised premium follows the limited pay rates based on your age at entry and policy term.
Note: The plan offers an Enhanced Accidental Death Benefit rider which provides a lump-sum benefit of up to three times the base sum assured if the life assured dies due to an accident within 180 days of the incident.
At Ditto, we recommend riders such as Waiver of Premium (WOP) and Critical Illness (CI) riders (not available with the plan). WOP helps maintain your policy if you meet the specified disability or illness conditions, while CI provides financial support after a covered critical illness diagnosis.
Sample Premiums by Age and Sum Assured
The illustration assumes a healthy, salaried, non-smoking male in Delhi (pincode: 110010) seeking ₹2 crore in level term cover until age 65. First-year discounts are excluded.
Note: Actual premiums may vary based on individual details, selections, and underwriting. You can use the Ditto premium calculator for rough estimates of flagship plans from HDFC Life, Axis Max Life, and ICICI Life.
Bandhan Life iTerm Elite charges higher premiums than most established insurers across the age groups compared. Despite the higher cost, it lacks certain useful features, such as an inbuilt terminal illness benefit and a critical illness rider, which limits its overall value.
Bandhan Life: Performance Metrics
Note: The data has been sourced from Bandhan Life’s public disclosures and IRDAI annual reports. You can explore Ditto Data Lab for more insurer metrics.
Pros and Cons of Bandhan Life iTerm Elite
Pros of Bandhan Life iTerm Elite
- Flexible Cover Options: Adapt Assure lets you increase or decrease your base sum assured as your financial needs change, subject to underwriting and policy conditions.
- Flexible Payment and Payout Options: Choose limited pay terms of 5, 10, or 15 years and select how your nominee receives the death benefit.
- Useful Family Benefits: The plan offers additional plan cover for eligible homemakers, a childbirth or adoption benefit for female policyholders, and health management services.
Cons of Bandhan Life iTerm Elite
- Cover Increases Require Underwriting: Adapt Assure does not guarantee an increase in cover. Medical tests and underwriting conditions apply.
- Special Exit Value Has Restrictions: Eligibility depends on the payment option and policy conditions. It is not an anytime refund of premiums, and single pay policies are ineligible.
- Limited Additional Protection: The base plan does not appear to include an inbuilt terminal illness benefit, while its rider options may not suit customers seeking extensive critical illness cover.
Why Choose Ditto for Term Insurance?
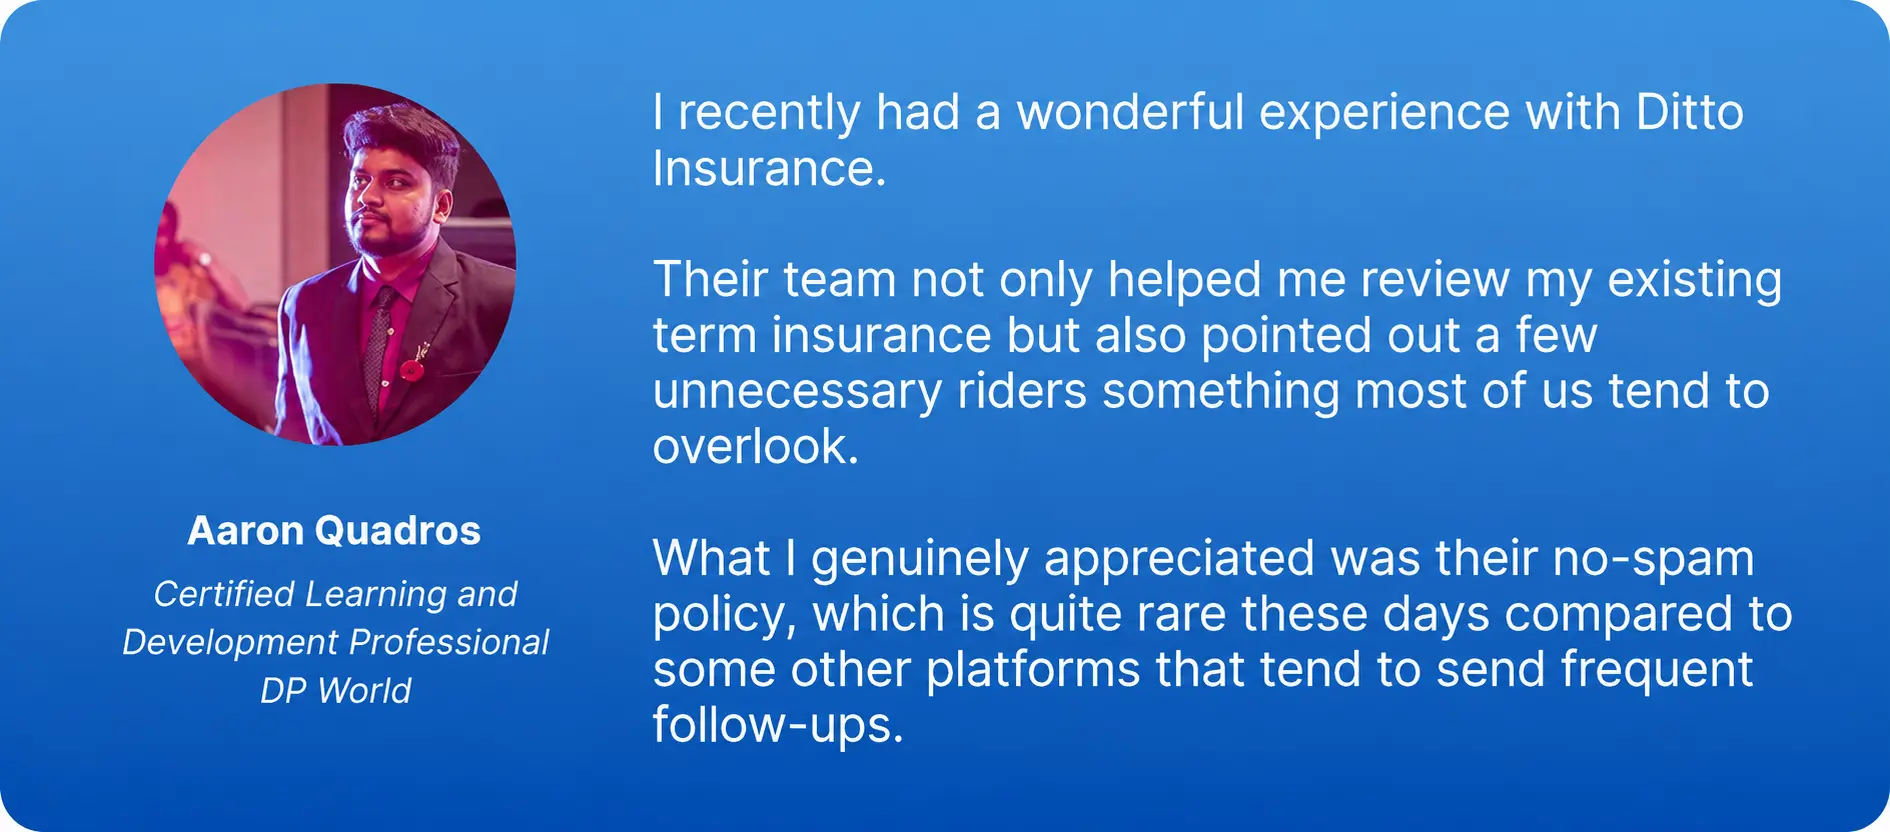
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Bandhan Life iTerm Elite is a flexible term plan with useful features such as Special Exit Value and Cover Continuance, and unique features like Adapt Assure. However, the lack of an inbuilt terminal illness benefit and a Waiver of Premium (WOP) rider limits its appeal.
From an insurer perspective, the complaint volume is a concern, with complaints reported at 1.68 times the industry median. The insurer’s solvency ratio also fell from 2.69x in FY 2024-25 to 1.55x in FY 2025-26, which warrants closer scrutiny.
Overall, while iTerm Elite offers useful flexibility, compare its features and insurer metrics with those of established providers before buying. If you prioritize broader protection and a stronger insurer track record, explore the best term insurance plans before making your decision.
Frequently Asked Questions
Last updated on: