

Overview
Bandhan Term Insurance has changed significantly in recent years, raising an important question for buyers: how competitive are its plans in today’s market?
With many insurers now offering more feature-rich term plans, it is worth looking closely at where Bandhan stands on coverage, flexibility, and overall value. In this guide, we break down its term plans, key features, riders, premiums to help you decide whether it is the right fit for you.
Bandhan Term Insurance Performance Metrics
Key Insights:
- Strong CSR: Bandhan Life’s 3-year average claim settlement ratio is above the industry average, indicating a consistent claims settlement record.
- Healthy ASR: Its amount settlement ratio suggests that the insurer is paying a substantial proportion of the total claim amount, not just settling a high number of claims.
- Higher Complaint Volume: Complaint volume is above the industry median, which may point to areas for improvement in customer service or claims handling.
- Smaller Business Scale: Bandhan Life’s annual business is below the industry median, indicating that it remains a relatively small player in the life insurance market.
- Strong Solvency Position: Its solvency ratio is above the industry median, reflecting a comparatively stronger financial cushion to meet future claim obligations.
Talk to an expert
today and
find
the right
insurance for you.
Where Can I Find the Claim Settlement Ratio of Bandhan Life Term Insurance?
You can find the claim settlement ratio of Bandhan term insurance from the following sources:
- IRDAI annual reports or handbook
- Bandhan Term Insurance’s financial disclosures and annual reports available on its official website
- Trusted insurance advisory platforms like Ditto
Top Term Insurance Plans Offered by Bandhan Term Insurance
Note: Bandhan Life offers term plans for different protection needs. iTerm Prime and iTerm Comfort are simple and cost-effective options for basic life cover, while iTerm Elite is the more comprehensive plan in the lineup, with features like instant claim assurance, health services, and a cover continuance benefit.
In addition, the iTerm Return of Premium (iTROP) plan combines protection with savings by refunding all premiums paid if the policyholder survives the policy term.
Riders Available in Bandhan Term Insurance Plans
Bandhan Term keeps its rider offering fairly limited. Its term plans mainly come with an Accidental Death Benefit Rider, which can be added for an extra premium.
This rider pays an additional lump sum to the nominee if the life assured dies due to an accident during the policy term. So, if you have a base term cover and add this rider, the payout in case of accidental death will be higher than the base sum assured.
So, if rider flexibility is a priority for you, this is one area where the insurer looks less comprehensive.
Top 5 Term Insurance Companies in India
Note: Bandhan Life Insurance does not appear in this top 5 list under Ditto’s insurer scoring methodology. Although it performs well on claim settlement metrics, it currently falls short of the leading insurers on broader product comprehensiveness, rider flexibility, and service experience.
Since our methodology looks beyond claims alone, these gaps had a meaningful impact on its overall score.
Premium Comparison for Bandhan Life Insurance’s Flagship Term Plans
Note: Premiums are for a ₹2 crore sum assured with coverage till age 65, based on a non-smoker profile male. The figures exclude first-year discounts (second-year premiums).
Insight: Bandhan Life iTerm Elite Plus can carry higher premiums across several customer profiles than plans such as Axis Max Life Smart Term Plan Plus and ICICI Prudential iProtect Smart Plus. Both plans offer terminal illness benefits, which iTerm Elite Plus lacks.
Compared with HDFC Life Click 2 Protect Supreme Plus, Bandhan Life iTerm Elite Plus may offer slightly lower premiums for some profiles. However, HDFC Life also offers a better rider ecosystem and the experience of a more established life insurer.
Why Choose Ditto for Term Insurance?
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
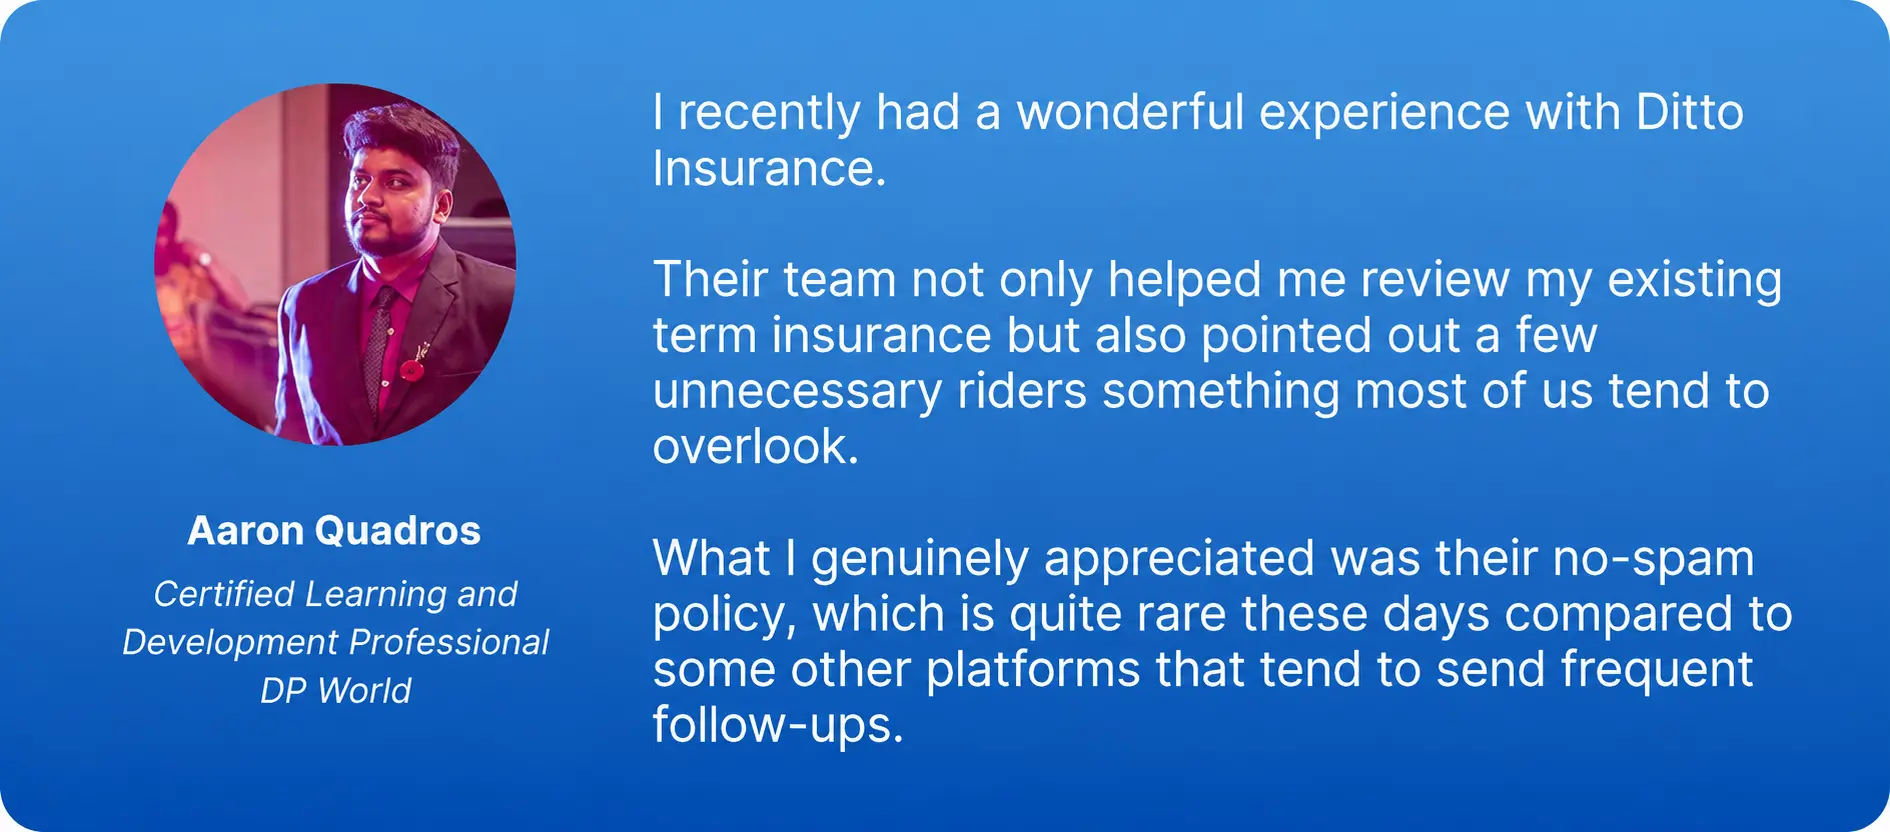
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
To simplify the decision, here’s a quick breakdown of who Bandhan term insurance is best suited for and who may be better off considering alternatives:
Who Should Buy Bandhan Term Insurance?
- You want affordable, no-frills life cover with a straightforward structure
- You are comfortable with a limited rider set (primarily accidental death benefit)
- You prefer Bandhan’s pricing and a simple buying experience
Who Should Avoid Bandhan Term Insurance?
- You want a wide range of riders (like critical illness or waiver of premium)
- You prioritize a stronger service track record and lower complaint levels
- You are looking for feature-rich plans with more built-in benefits across variants
While Bandhan Life works well for basic protection, buyers looking for stronger alternatives can also explore our list of the best term insurance companies in India.
Frequently Asked Questions
Last updated on: