

Overview
Choosing between PLI and LIC depends on more than comparing premiums or returns. They differ in how their policies are structured, who they are designed for, and the financial needs they can address.
PLI is best suited to eligible policyholders seeking traditional insurance with a savings component, while LIC offers a broader range of products for different protection and investment needs.
Factors such as policy duration, sum assured, bonus structure, maturity benefits, and the level of life cover can therefore significantly affect the outcome. Before choosing between the two, compare similar plans on benefits and costs rather than comparing the insurers as a whole.
This guide looks at the key differences between PLI and LIC to help you decide which option best fits your financial goals.
PLI vs. LIC: How Are They Different?
PLI is an insurance scheme administered by the Department of Posts, with six traditional policies and a maximum sum assured of ₹50 lakh under most adult plans.
By comparison, LIC is an IRDAI-registered life insurer with a much wider product portfolio, including traditional savings plans, term insurance, pension plans, and Unit-Linked Insurance Plans.
LIC also has a dedicated term insurance portfolio, with plans such as Digi Term, Yuva Term, New Tech-Term, Bima Kavach, and Jeevan Raksha. Therefore, someone looking for pure life protection would be comparing a very different product under LIC than they would under PLI.
Note: Details about PLI eligibility are available in the Postal Life Insurance guide, while rural residents can explore Rural Postal Life Insurance (RPLI).
For PLI login, policyholders can register on the PLI portal using their policy details and access services such as PLI online payment. LIC policyholders can use the LIC customer portal or app for LIC login and manage services such as LIC premium payment through available digital payment options.
PLI vs. LIC: Plans and Sample Premiums
PLI Santosh vs. LIC New Endowment Plan 714: Premium and Maturity Comparison
Key Insights: For the same ₹5 lakh sum assured and a 25-year term, the premium difference is relatively small. PLI Santosh costs about ₹19,490 a year, while LIC New Endowment Plan 714 costs about ₹19,992 a year, a difference of only around ₹500 annually or ₹12,500 over 25 years. However, premium alone should not decide between the two.
The same amount paid towards a high-cover pure term plan can potentially provide ₹1 crore or more of life cover, depending on eligibility and underwriting. This aligns more closely with the primary purpose of life insurance: ensuring adequate financial protection for dependents. PLI and LIC endowment plans, by contrast, combine life cover with a savings component.
Therefore, the comparison should focus first on adequate life cover, followed by premiums, guarantees, maturity benefits, bonuses, and liquidity.
Talk to an expert
today and
find
the right
insurance for you.
PLI vs. LIC: Bonus Rates, Returns, and Claim Experience
LIC vs. PLI: Bonus Rates
PLI participating plans earn simple reversionary bonuses, which are declared annually as an amount per ₹1,000 of sum assured. For FY 2026–27, the bonus rates vary across PLI plans, as shown below.
Bonus Rates (FY 2026–27)
Note: For LIC, participating plans also declare bonuses, but rates vary by plan and policy term. Non-participating plans, such as New Jeevan Sathi, do not earn bonuses. Instead, they provide guaranteed additions and other benefits specified in the policy terms. When comparing PLI vs. LIC returns, don't consider the bonus rate in isolation. You should also consider the premium paid, sum assured, policy term, guaranteed benefits, accumulated bonuses, and final maturity value.
PLI vs. LIC: Returns
Returns from PLI and LIC depend on the plan, premium, policy term, sum assured, and applicable bonuses or guaranteed additions. Therefore, the bonus rate alone does not determine which policy offers better returns.
For a meaningful comparison, consider total premiums paid and maturity benefits for similar plans. For example, you can compare PLI Santosh with the LIC New Endowment Plan (Plan 714) using the same age, sum assured, policy term, and premium-paying term. Comparing the effective return, or IRR, can provide a clearer picture of the returns each policy generates.
PLI vs. LIC: Claim Experience
Claim experience is an important factor when comparing PLI and LIC.
- LIC is regulated by the Insurance Regulatory and Development Authority of India (IRDAI), and its claim settlement data is available through public disclosures and IRDAI reports. LIC recorded an average Claim Settlement Ratio (CSR) of 98.16% for FY 2024–26.
- The Department of Posts administers PLI, and it does not fall under IRDAI's regulatory framework. Therefore, its claim experience cannot be directly compared with LIC's CSR. According to the India Post annual report, 8,737 PLI death claims were settled between January 1 and December 31, 2025, with total payouts of ₹378.65 crore. For January 1 to March 31, 2026, an estimated 2,184 death claims were expected to be settled, totaling ₹94.66 crore.
When evaluating claims, policyholders should consider more than the CSR. Policy terms, exclusions, documentation requirements, and the claims process should also be reviewed before deciding.
PLI vs. LIC: Tax Benefits
- Section 80C (Now Section 123): Eligible life insurance premiums paid can qualify for a deduction under Section 80C when the taxpayer opts for the old tax regime, subject to the applicable limits and conditions.
- Section 10(10D) (Now Section 11, Schedule II): Death benefits are exempt from tax, while maturity proceeds may also qualify for exemption if the prescribed conditions are met. These include applicable premium-to-sum-assured requirements. For non-ULIP policies issued on or after 1 April 2023, the exemption is also subject to an aggregate annual premium limit of ₹5 lakh across qualifying policies.
Pros and Cons of Postal Life Insurance
Pros
- Government-Backed: PLI is administered by the Department of Posts and offers a government-backed insurance structure.
- Competitive Premiums: PLI premiums can be lower than those of comparable private endowment plans.
- Declared Bonuses: Eligible participating PLI plans provide annual bonuses as per the rates declared for the respective plans.
- Policy Loans: Loans are available against eligible policies after the applicable period, which is 3 to 4 years depending on the plan.
Cons
- ₹50 Lakh Coverage Limit: The maximum sum assured under most adult PLI plans is ₹50 lakh, which may not be enough to protect most households.
- No Pure Term Plan: PLI does not offer a straightforward high-cover term insurance plan.
- Restricted Eligibility: PLI is available only to specified categories of employees and professionals.
- Limited Product Features: Compared with LIC, PLI offers fewer product options and riders, and some processes may involve more paperwork.
Pros and Cons of LIC
Pros
- Wide Product Range: LIC offers products ranging from term insurance and endowment plans to pension plans and ULIPs.
- Broad Eligibility: LIC policies are available to a wider list of eligible individuals, subject to underwriting.
- Government Guarantee: Under Section 37 of the LIC Act, the Central Government expressly guarantees the sums assured under LIC policies, including declared bonuses, subject to the applicable provisions.
- Extensive Branch Network: LIC has a large network of branches and service points across India.
- Riders: Several LIC plans offer additional riders, such as accidental death and disability benefits, for enhanced protection, subject to the policy terms.
Cons
- Higher Premiums: Premiums for some traditional LIC plans may be higher than those of comparable PLI plans.
- Bonuses Are Not Guaranteed: Bonus rates for participating plans depend on the bonuses declared by LIC and are not guaranteed in advance.
- Moderate Returns: Returns from traditional endowment plans may be modest compared with other long-term fixed-income options like PPF, FDs, and debt mutual funds.
Why Choose Ditto for Life Insurance?
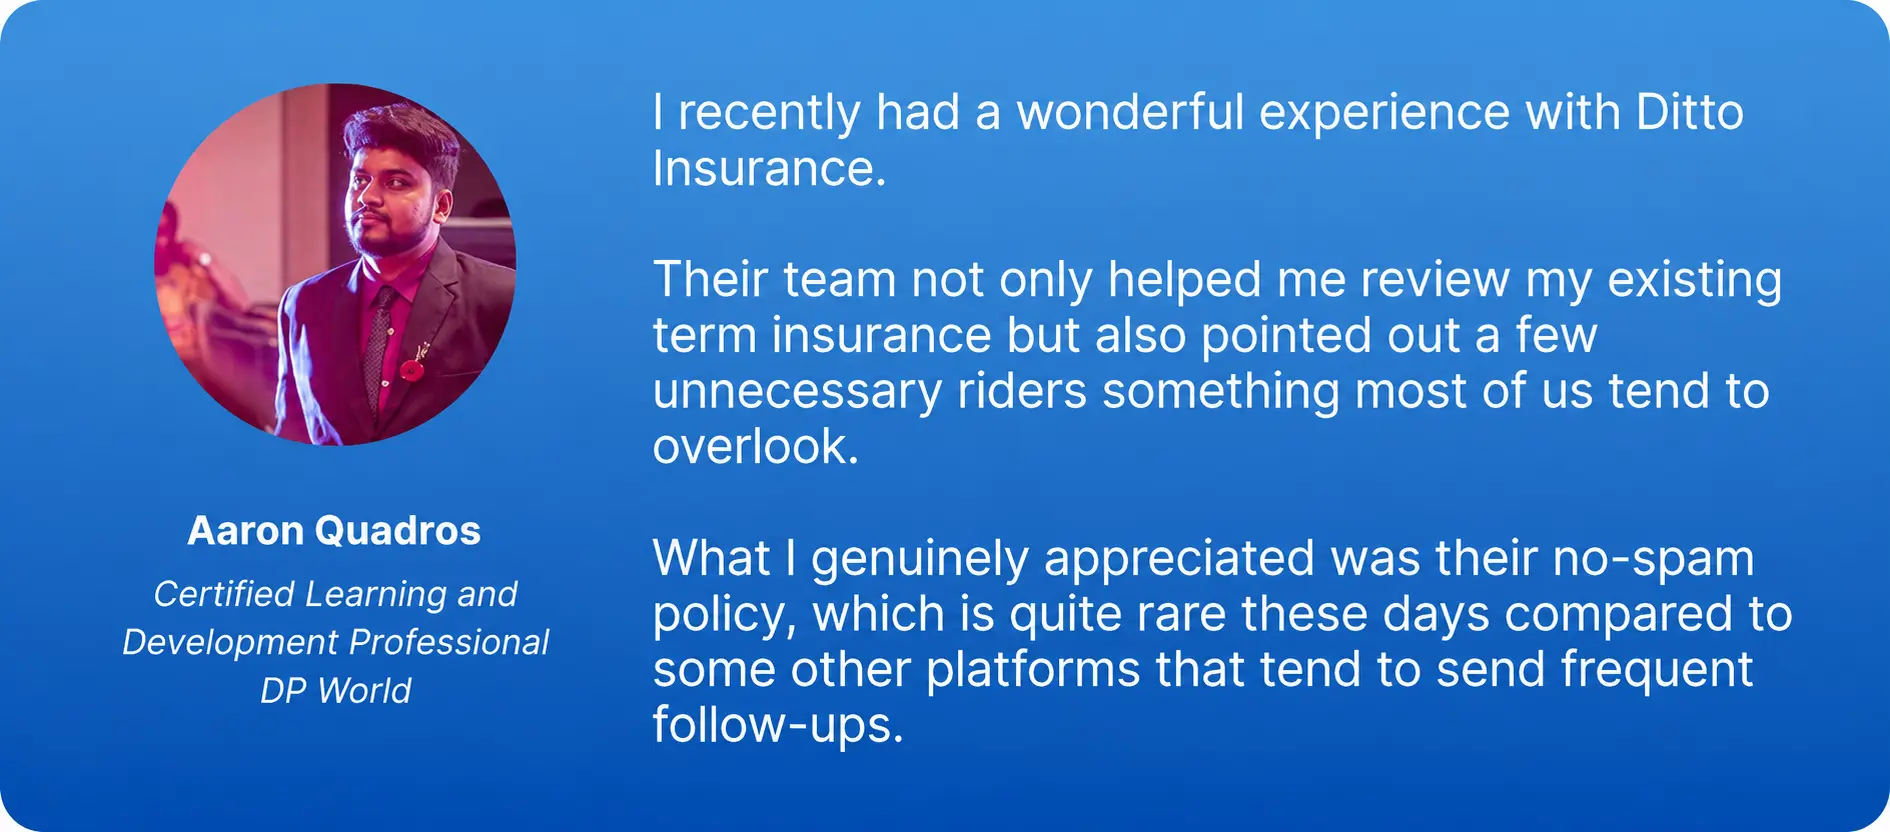
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
PLI and LIC serve different insurance needs. PLI may suit eligible buyers seeking traditional savings-linked insurance, while LIC offers a wider range of plans and higher-cover options. The right choice depends on eligibility, coverage needs, premiums, and expected maturity benefits.
For pure protection, a dedicated term insurance plan is better suited to providing higher life cover. If you are considering LIC, read our guide to LIC term insurance plans to understand its current term offerings. You can also compare other insurers and plans through our guide to the best term insurance plans in India before choosing a policy.
Frequently Asked Questions
Last updated on: