

Overview
Finding health insurance can be especially difficult when you already have a pre-existing disease. A shorter waiting period can sound like a clear advantage, but you should consider more before deciding whether a plan is right for you.
That is where Prudential Health PRUHealth Guardian stands out. It is built for people with pre-existing conditions, but whether it offers enough protection depends on the fine print.
In this PRUHealth Guardian review, we cover what the plan includes, its key features and riders, eligibility and medical requirements, sample premiums, Prudential Health India's performance metrics, and the plan's pros and cons to help you decide whether it belongs on your shortlist.
What Is the Prudential Health PRUHealth Guardian Plan?
PRUHealth Guardian is a health insurance plan from Prudential Health India, offering sum insured options ranging from ₹5 lakh to ₹25 lakh. You can buy it on an individual or family floater basis, and it has a two-year waiting period for pre-existing diseases.
Guardian is one of four health insurance plans offered by Prudential Health India, alongside Protect, Edge, and Signature. Prudential Health India is a relatively new standalone health insurer, backed by Prudential plc and the HCL Group. Since the insurer has only recently commenced operations, it does not have any claims or service track record.
Key Features & Riders of Prudential Health PRUHealth Guardian Plan
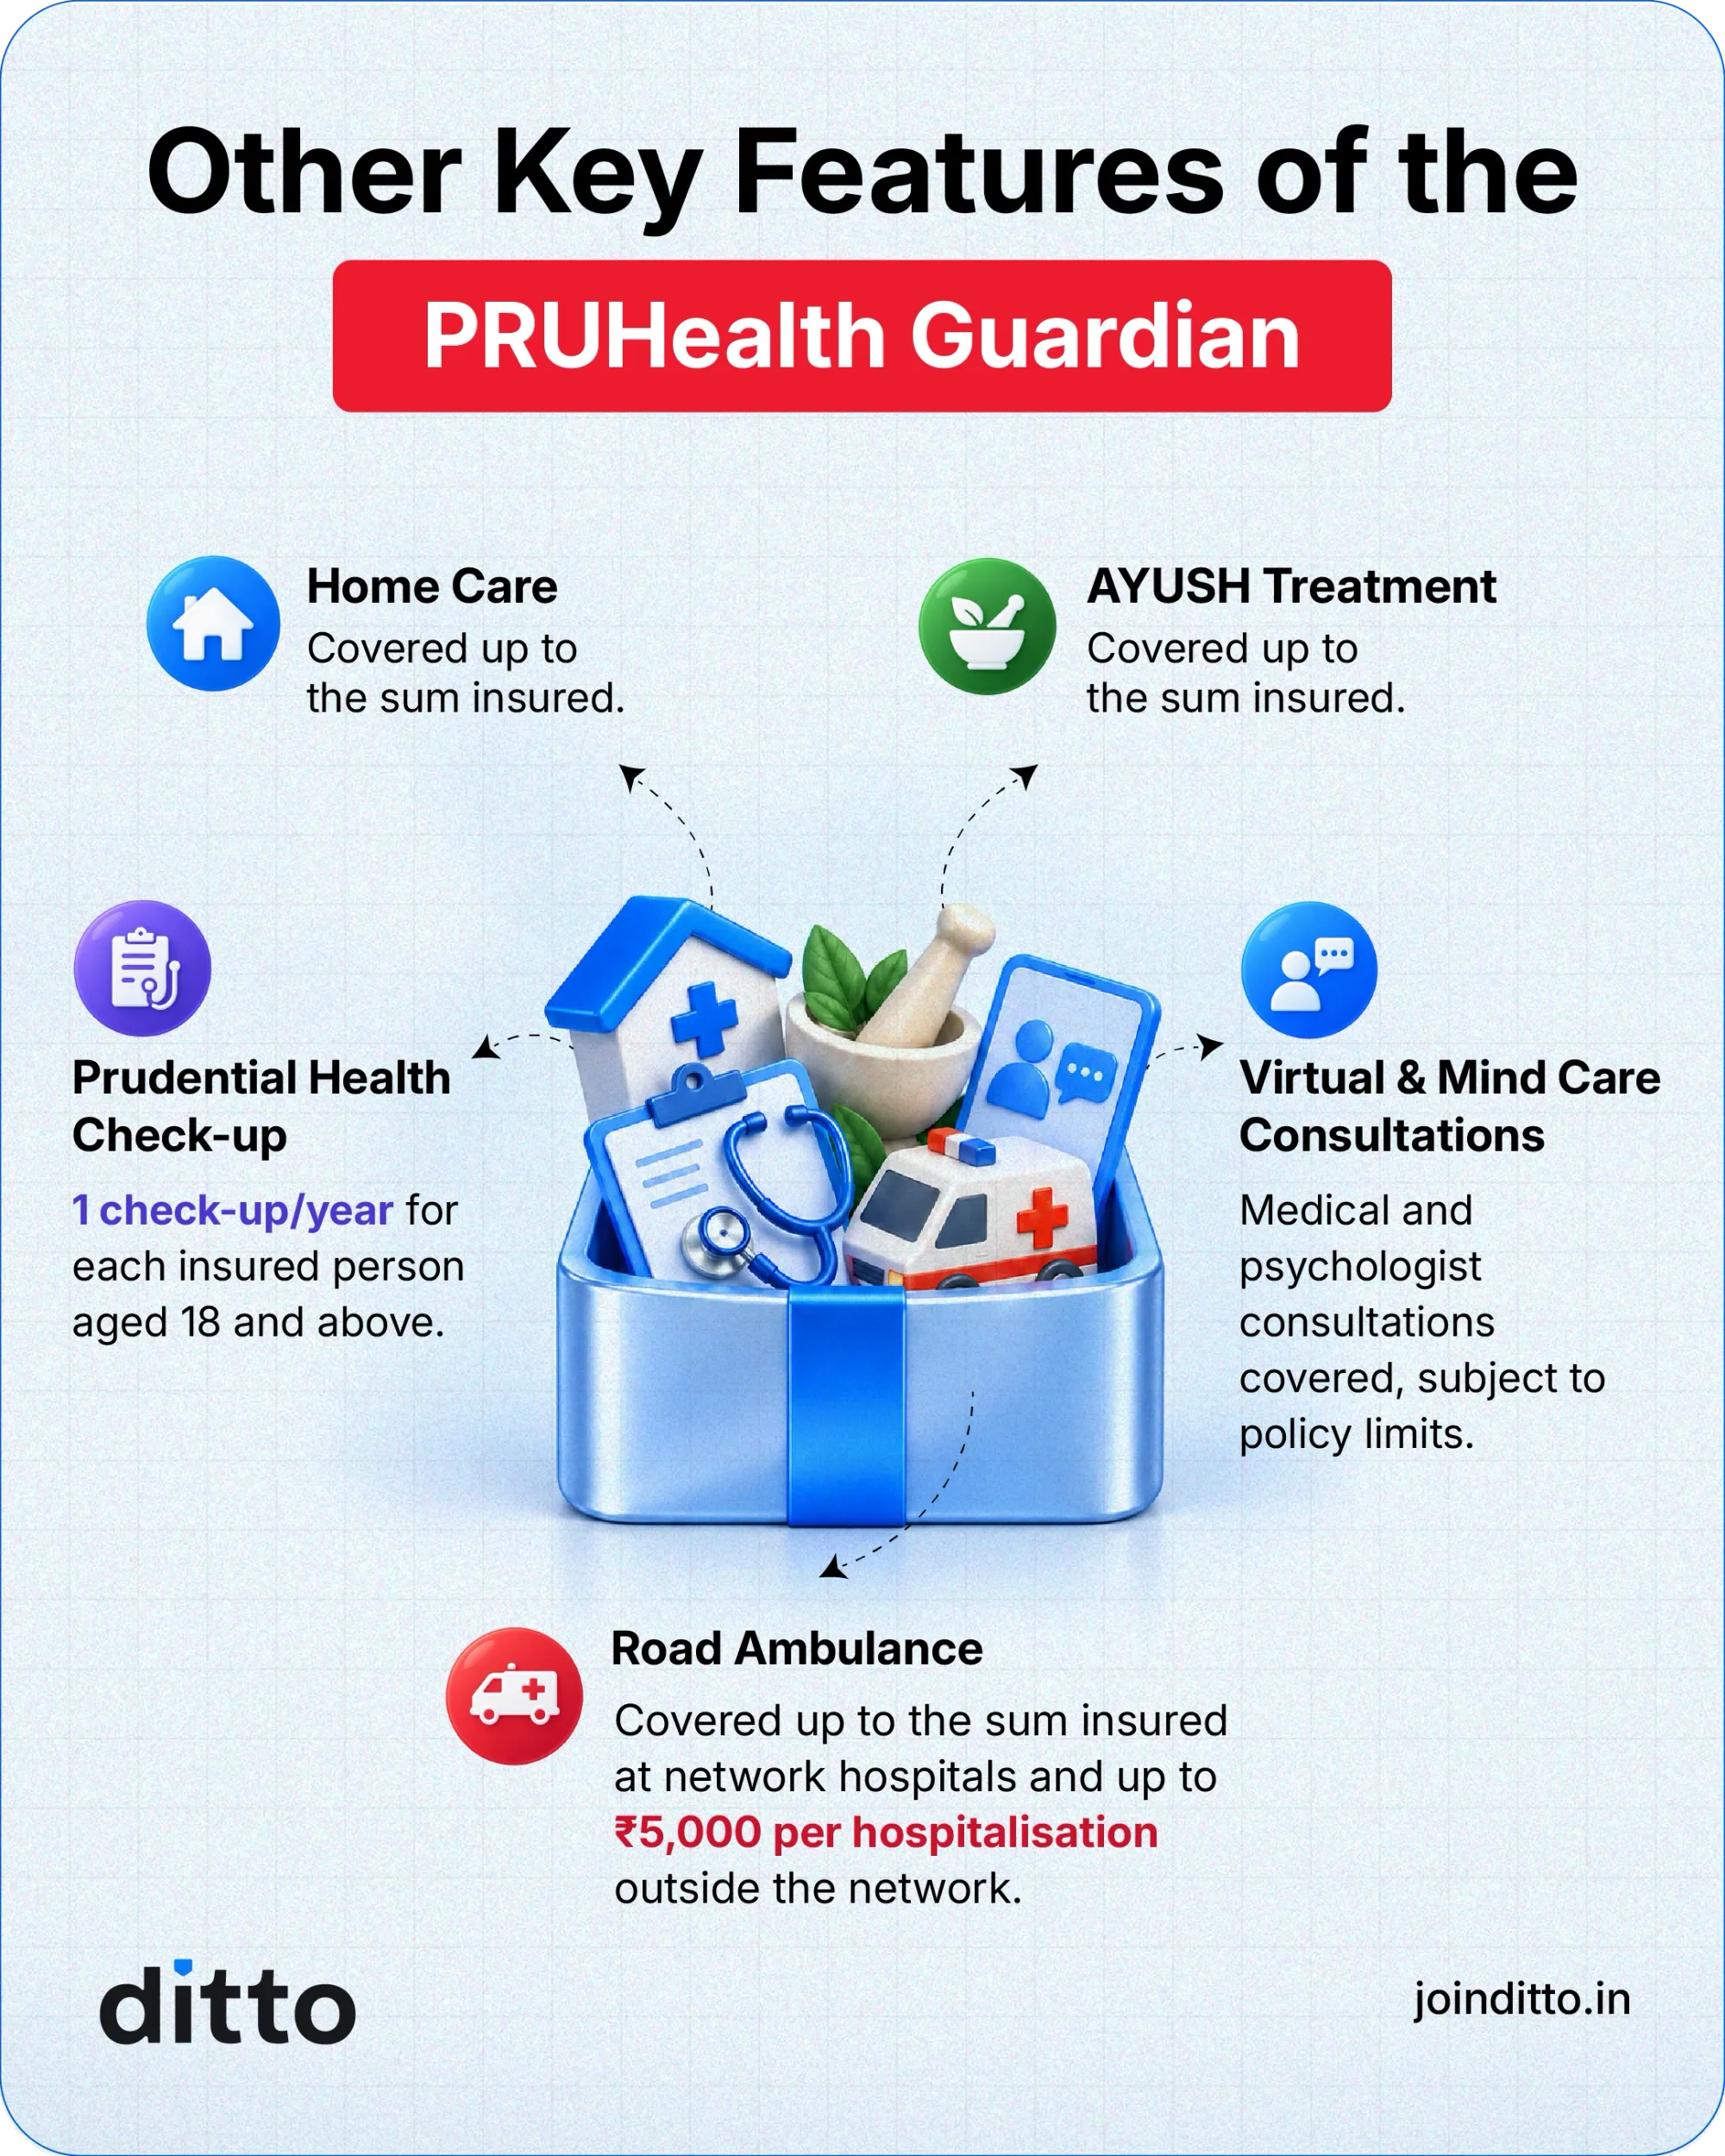
Other Key Features
Optional Covers and Add-Ons
PRUHealth Guardian has a wide add-on menu, with 20 optional covers listed in the prospectus.
PRUHealth Guardian also offers several other optional covers, including Prudential Select Network, Air Ambulance, Second Medical Opinion, and Double Your Cover After 7 Years. Refer to the PRUHealth Guardian prospectus for the complete list, limits, and eligibility conditions.
Ditto's Take
Talk to an expert
today and
find
the right
insurance for you.
Prudential Health PRUHealth Guardian Plan: Eligibility, Entry Age & Medical Requirements
Who Can Buy PRUHealth Guardian?
- The policy is available on both an individual and family floater basis.
- An individual policy can cover up to 20 members, with each insured person having a separate sum insured.
- A family floater can cover up to 6 members, including self, a legally married spouse, and dependent natural or legally adopted children.
Entry and Exit Age
Adults
Entry age is 18 to 99 years.
Dependent Children
Children can enter from 91 days under a family floater and from 5 years under an individual policy. They can remain covered as dependents up to 25 years.
Children Above 25 Years
If they are still dependent on their parents, they can remain covered, but only under a separate individual policy, not as a dependent child under the floater.
Exit Age
There is no maximum cover-ceasing age on renewal.
Medical Requirements and Underwriting
The policy documents do not prescribe a fixed pre-policy medical test requirement for every applicant. Policy issuance is subject to Prudential's underwriting, medical history, proposal form disclosures, and applicable policy terms. Whether additional medical information or tests are required depends on the individual application.
Any pre-existing disease must be declared at the time of application and accepted by the insurer for coverage under the policy, subject to the applicable waiting period and policy terms.
Prudential Health PRUHealth Guardian Plan: Sample Premiums by Age and Coverage
Note: A stands for adult and C stands for child. These are indicative base premiums for a ₹15 lakh sum insured for Zone 1, based on the age bands in the official premium chart. Actual premiums can vary based on age, location, medical history, underwriting, add-ons selected, discounts, and family structure.
For base premiums across other age profiles, family combinations, and sum insured options, refer to the official PRUHealth Guardian premium chart provided on the official website.
Prudential Health India: Performance Metrics
Prudential Health Insurance India is still too new to have a meaningful performance track record. Since the insurer only recently commenced operations, comparable metrics such as the Claim Settlement Ratio (CSR), Incurred Claims Ratio (ICR), and complaint data are not yet available.
This is a normal limitation for a new insurer. It simply means there isn't enough claims history yet to assess Prudential the way we can evaluate established insurers such as Care Health Insurance or HDFC ERGO, which have several years of claims and service data available.
Prudential currently reports 12,000+ network hospitals across India. That's a sizable network, but hospital count alone does not tell us how smoothly cashless claims will be handled in practice.
For now, Prudential's promoter backing, product design, and hospital network are useful early signals, but they cannot substitute for an actual claims track record. At Ditto, we'd prefer to watch how the insurer performs over the next few years. For comparable data on established insurers, explore the Ditto Data Lab.
Pros and Cons of Prudential Health PRUHealth Guardian
Pros
- PED Waiting Period: Pre-existing diseases are covered after 24 months of continuous coverage, subject to disclosure, underwriting, and policy terms.
- Broad Starting Hospital Network: Prudential Health lists 12,000+ network hospitals across India, giving the insurer a fairly wide cashless footprint from the outset.
- Fairly Competitive Healthy Lifestyle Discount: The optional cover lets adults aged 18+ earn up to a 35% discount on renewal premiums based on the number of eligible healthy days completed during the policy year.
- Strong Built-In Outpatient Support: Guardian includes unlimited GP tele/video consultations, an annual health check-up, and four psychologist tele/video consultations as part of its base benefits.
- Useful Child Protect Option: This optional cover can waive a child's base premium for up to 5 years or until age 18, whichever is earlier, following specified life-altering events involving the parent/proposer.
Cons
- Mandatory Co-Payment: You have to bear 20% of eligible claim expenses under the base plan, which can translate into a sizable out-of-pocket amount on large claims.
- Disease-Wise Sub-Limits: Treatments such as knee replacement, cataract, hernia, cancer, and cardiovascular conditions have specific payout caps unless you choose the relevant modification cover.
- Limited Restoration: Restoration is available only once in a policy year, from the second claim onwards, and only for an unrelated claim.
- Shorter Pre- and Post-Hospitalization Cover: Eligible expenses are covered for only 30 days before hospitalization and 60 days after discharge.
- Room-Category Restrictions: Depending on the option selected, you are eligible for either a shared AC room or a single private AC room.
- Limited Insurer Track Record: Prudential Health India has only recently commenced operations, so there isn't enough CSR, ICR, or complaint data to judge its long-term claims and service performance.
- No Annual Loyalty Addition: Guardian does not automatically increase your sum insured at every renewal through a Loyalty Addition or cumulative bonus.
Ditto's Take
Why Choose Ditto for Health Insurance?
At Ditto, we’ve assisted over 12,00,000 customers choose the right insurance policy. Why customers like Pallavi love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
PRUHealth Guardian is best suited to buyers with pre-existing diseases who value a shorter 24-month PED waiting period. However, that advantage comes with trade-offs such as a 20% mandatory co-payment, disease-wise sub-limits, room-rent restrictions, and limited restoration, all of which can increase out-of-pocket costs at claim time.
Prudential Health is still new, so limited claims and service data make it hard to judge its long-term performance. And since the insurer offers other plans with fewer restrictions, Guardian should not be the default choice simply because of its shorter PED waiting period.
Before buying, compare it with the best health insurance plans in India on waiting periods, room eligibility, co-payments, sub-limits, restoration, and final premium.
Frequently Asked Questions
Last updated on: