

Overview
Relocating to another city in India does not cancel your existing health insurance policy. However, it can affect your premiums, access to cashless hospitals, and out-of-pocket expenses, depending on your policy's terms.
This guide explains how relocating to a new city impacts your health insurance, including zone-based pricing, hospital networks, address updates, and policy portability.
Understanding the Impact of Relocating on Existing Health Insurance Policy
- No Need to Buy a New Policy: IRDAI does not require you to purchase a new health insurance policy when you move cities. Your existing policy can continue, subject to its territorial coverage and terms.
- Premium Zones and Treatment Zones: The zone used to calculate your premium can differ from the zone used for treatment. A higher premium zone does not automatically mean you will face an additional co-payment in another city.
- Waiting Periods Continue: Moving to another city does not automatically restart your waiting periods. If you maintain uninterrupted coverage, your accumulated waiting-period credits and other eligible continuity benefits remain intact.
- Premiums Can Change: Relocation can affect your premium if your insurer uses zone-based pricing. However, not every insurer adjusts premiums immediately. Some apply changes only at renewal, while others allow mid-term adjustments under specific policy terms.
Talk to an expert
today and
find
the right
insurance for you.
Note: Health insurance premiums can vary by city based on local healthcare and hospital costs. Metro areas such as Delhi-NCR have higher premiums, while smaller towns like Patna have lower rates, depending on the insurer's zone-based or tier-based pricing.
Annual Premiums Across PIN Codes
Note: A represents an adult, and C represents a child. The premiums for a sum insured of ₹15 lakh shown are indicative estimates for healthy individuals opting for HDFC ERGO Optima Secure+. Actual premiums can vary based on age, city, medical history, and add-ons.
Premium Insight: Delhi falls under Tier 1, while Patna comes under Tier 6. For the same profiles, premiums in Patna are approximately 12% to 26% lower than in Delhi.
Temporary vs. Permanent Relocation
Factors That Influence Health Insurance During Relocation
Key Insights: What to Check Before Relocating
- Do Not Port Only for Hospital Network Gaps: A limited cashless network in your new neighborhood does not automatically mean you should switch insurers, since network hospital tie-ups keep changing and expanding. Consider portability if you are also dissatisfied with the insurer's policy terms, coverage, or service.
- Update Your Address Promptly: Moving from a Tier 2 or Tier 3 city to Delhi or Mumbai does not automatically invalidate cashless claims. However, an outdated address can lead to repeated queries and delays during claim processing.
- Pan-India Coverage Still Requires Updated Details: Even if your policy offers pan-India coverage without zonal co-payments, update your current address. Outdated records can trigger verification queries and delay cashless pre-authorization.
- Review Your Sum Insured After Relocation: Healthcare costs can vary significantly between cities, so your existing cover may no longer be sufficient. We recommend increasing your base sum insured based on your budget and needs
How Does Relocating to a New City Affect Your Health Insurance Premium?
1) Moving From a Smaller City to a Metro
Moving from a smaller city to a metro increases your health insurance premium if the insurer uses health insurance zones to price plans. Higher healthcare costs in cities like Delhi and Mumbai can affect renewal premiums.
2) Moving From a Metro to a Smaller City
Moving from a metro to a Tier 2 or Tier 3 city can reduce your premium if the insurer offers lower rates for that zone. However, a refund or lower renewal premium is not automatic. It depends on the insurer's pricing rules.
3) Zonal Pricing and Co-Payment Rules
Insurers classify cities into different pricing zones. If you have a geographical co-payment in health insurance, treatment in a higher-cost zone can require you to pay a portion of the claim. Check whether upgrading your zone-based health insurance or choosing pan-India coverage can avoid this expense.
Comparing Health Insurance Options When Moving to a New City
- Keep Your Existing Policy: Continuing your current policy preserves coverage and eligible continuity benefits. This option works well if your insurer has a suitable hospital network in the new city and your policy does not impose restrictive geographical co-payments.
- Upgrade Your Premium Zone: You can request a zone upgrade if your new city falls under a higher-cost zone. This can help avoid additional co-payments for treatment there. However, your premiums can increase, and some insurers may not allow a later downgrade.
- Migrate to Another Plan With the Same Insurer: If your current plan no longer suits your needs, ask your insurer about migrating to another available product. Eligible continuity credits can be carried forward, but the new plan may have different benefits, exclusions, and pricing.
Benefits of Reviewing Your Health Insurance Before Relocating
Avoid Unexpected Premium Increases
Prevent Surprise Co-Payments
Find Suitable Cashless Hospitals
Maintain Continuous Coverage
Identify Coverage Gaps
Why Choose Ditto for Health Insurance?
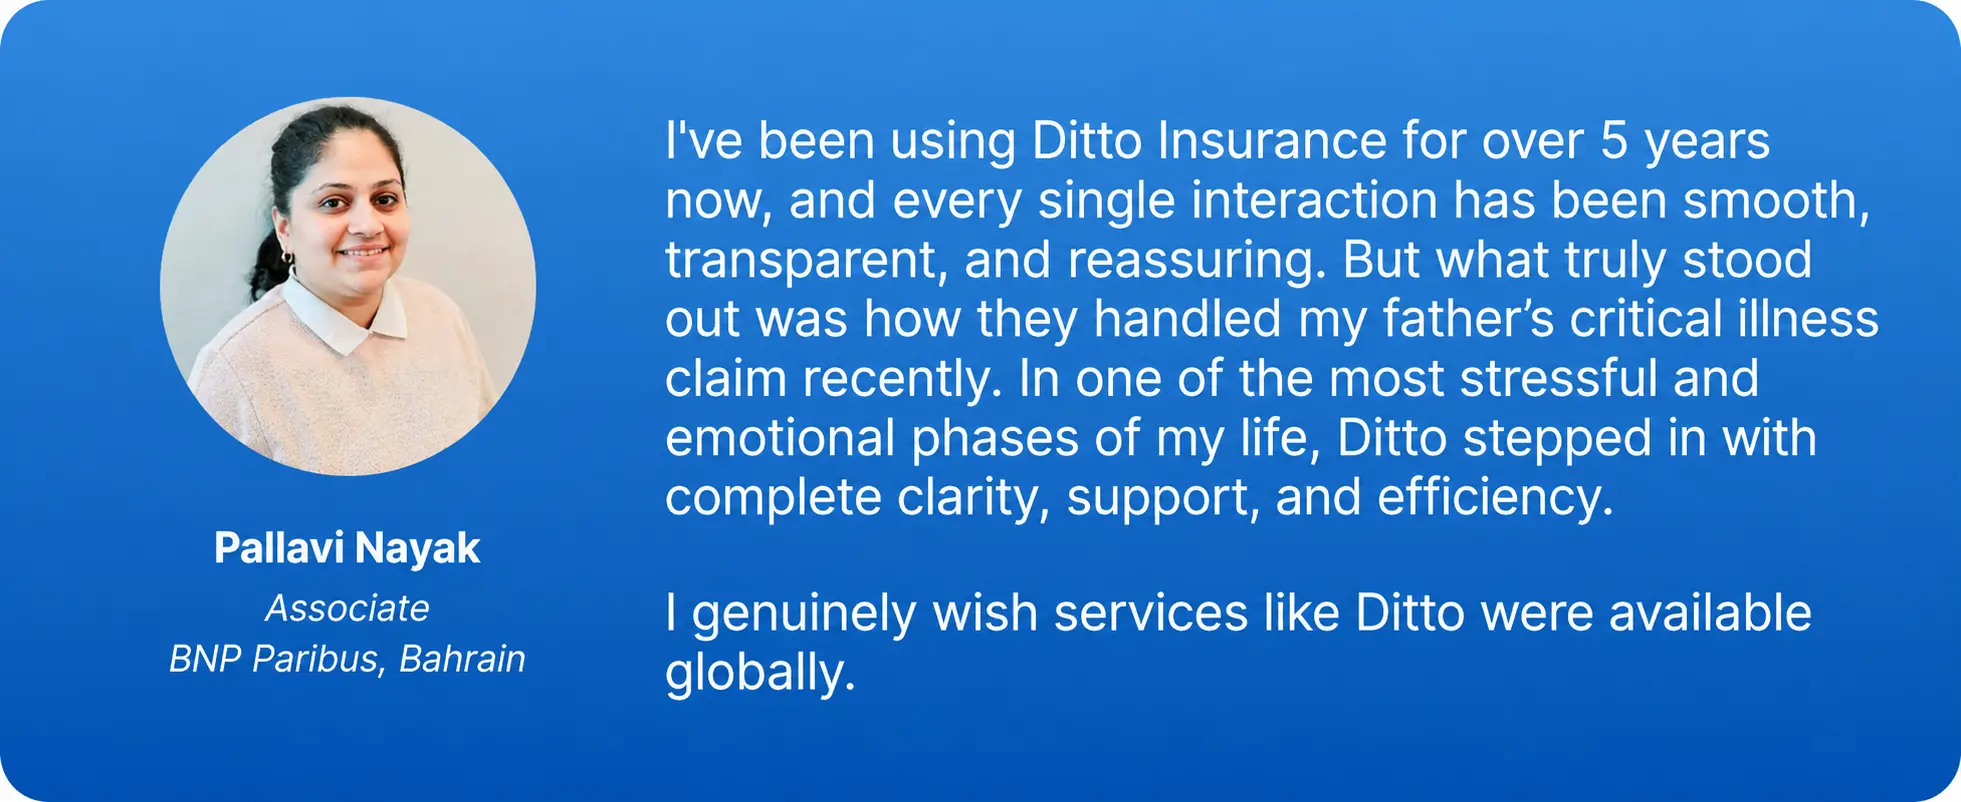
At Ditto, we’ve assisted over 12,00,000 customers choose the right insurance policy. Why customers like Pallavi love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Relocating does not mean you need to replace your health insurance policy. However, you should check whether your existing cover remains financially and practically suitable in your new city.
The bigger risks go beyond higher premiums. An unnoticed geographical co-payment, inadequate coverage for local hospital costs, limited cashless hospital access, or loss of continuity benefits can lead to unexpected expenses.
At Ditto, we recommend the best health insurance plans without zonal co-payments. If you bought a plan through us and are relocating, contact our team. We can help you notify the insurer and check whether a pro-rata premium adjustment or a higher/lower renewal premium applies.
Frequently Asked Questions
Last updated on: