

Overview
Getting married brings new responsibilities, including decisions about healthcare and financial protection. Choosing the right policy early can help couples manage medical expenses while preparing for future needs.
This guide to health insurance for couples explains the available policy types, key benefits, coverage options, and factors to consider before buying. It also helps you assess whether a shared family floater or separate individual policies suit your needs.
Why Health Insurance Is Crucial After Marriage?
- Financial Protection for Both Spouses: A hospitalization involving either partner can put pressure on shared savings. Health insurance helps cover eligible medical expenses and protects your finances from unexpected healthcare costs.
- Start Waiting Periods Early: Buying health insurance soon after marriage allows waiting periods to begin early. This can help you access benefits for pre-existing conditions and specified illnesses once the applicable waiting periods are complete.
- Reduce Dependence on Employer Policies: Employer-provided health insurance can end when you change jobs or leave your organization. A personal policy gives you lifelong coverage, regardless of your employment status.
- Plan Coverage for Future Children: If you plan to start a family, check how the policy covers newborns and when you can add them. Understanding enrollment rules in advance can help you arrange coverage without delays.
- Prepare for Long-Term Healthcare Needs: Existing medical conditions and future diagnoses can affect coverage, waiting periods, and underwriting. Buying a policy early can help you establish coverage before your healthcare needs change.
Note: There is no separate category called “couple health insurance” by IRDAI. Married couples can instead choose a family floater policy that covers both spouses or maintain separate individual health insurance policies.
Talk to an expert
today and
find
the right
insurance for you.
Individual vs. Family Floater: What Works for Newly Married Couples?
Note: If one spouse has a severe or complicated medical history that makes them ineligible for comprehensive plans, consider separate individual policies. This allows the healthier spouse to have independent coverage without being affected by the other partner's underwriting terms.
Key Insights for Newly Married Couples
- Adding Your Spouse Mid-Term: If you already have a policy and want to add your spouse, some insurers allow mid-term inclusion. This can help avoid waiting until renewal. Check the required documents, additional premium, and effective date of coverage.
- Choosing a Family Floater for First-Time Buyers: If both spouses are healthy and buying health insurance for the first time, a family floater is the most cost-effective option. It offers shared coverage at a relatively lower combined premium.
Best Health Insurance Plans for Married Couples
Key Features Newlyweds Should Look For
- Adequate Base Sum Insured: Choose a sum insured that can cover the couple's likely medical expenses. In a family floater, remember that one major hospitalization can use up a large part of the shared coverage.
- No Restrictions: Look for plans without any room-rent limits, co-payments, or disease-wise sub-limits, as these features can increase your out-of-pocket expenses.
- Restoration Benefit: Check whether the restoration benefit applies to the same person and repeated claims for the same illness. This can be useful if both spouses need hospitalization during the same policy year.
- Waiting Periods: Compare waiting periods for pre-existing and specified illness diseases and look for shorter options where available. This is especially important if either spouse already has a diagnosed medical condition.
- Consumables Protection: Look for coverage for specified non-medical items, such as gloves, masks, and other hospital consumables. These expenses can form a significant part of your hospital bill if the policy excludes them.
- Cashless Hospital Network: Check whether your preferred hospitals in your city offer cashless treatment under the policy. A large national network count alone is not enough if nearby hospitals are not included.
- Pre- and Post-Hospitalization Coverage: Check how many days of medical expenses the policy covers before admission and after discharge. This matters because diagnostic tests, medicines, and follow-up consultations can add to your expenses.
Maternity Coverage: What Newly Married Couples Should Know
If you are newly married and plan to start a family, consider maternity coverage early. Most retail health insurance plans have waiting periods you must complete before you can claim delivery expenses. If you are already pregnant when you buy the policy, maternity benefits will not cover the ongoing pregnancy.
At Ditto, we recommend choosing a comprehensive health insurance plan that meets your hospitalization needs even without maternity coverage. Prioritize an adequate sum insured, fewer restrictions, suitable room eligibility, and a reliable hospital network.
Note: Most retail health insurance plans allow you to add your newborn to the policy only after 90 days of birth. Check your insurer's enrollment rules and timelines, as these may vary by plan.
How Much Cover Does a Newly Married Couple Need?
The right sum insured for medical insurance for husband and wife depends on treatment costs at your preferred hospitals, each spouse's health profile, existing coverage, and financial capacity. Consider these factors before deciding how much cover your family floater should provide.
For two relatively healthy adults in their late twenties or early thirties, ₹15 lakh to ₹25 lakh can be a starting point. Couples in high-cost cities or those planning to add children may need to consider higher coverage.
Mistakes to Avoid While Buying a Health Insurance Plan as a Newly Married Couple
Canceling an Existing Policy Without Reviewing It
Assuming Marriage Automatically Covers Your Spouse
Ignoring Sum Insured and Policy Restrictions
Relying Only on Employer Cover
Why Choose Ditto for Health Insurance?
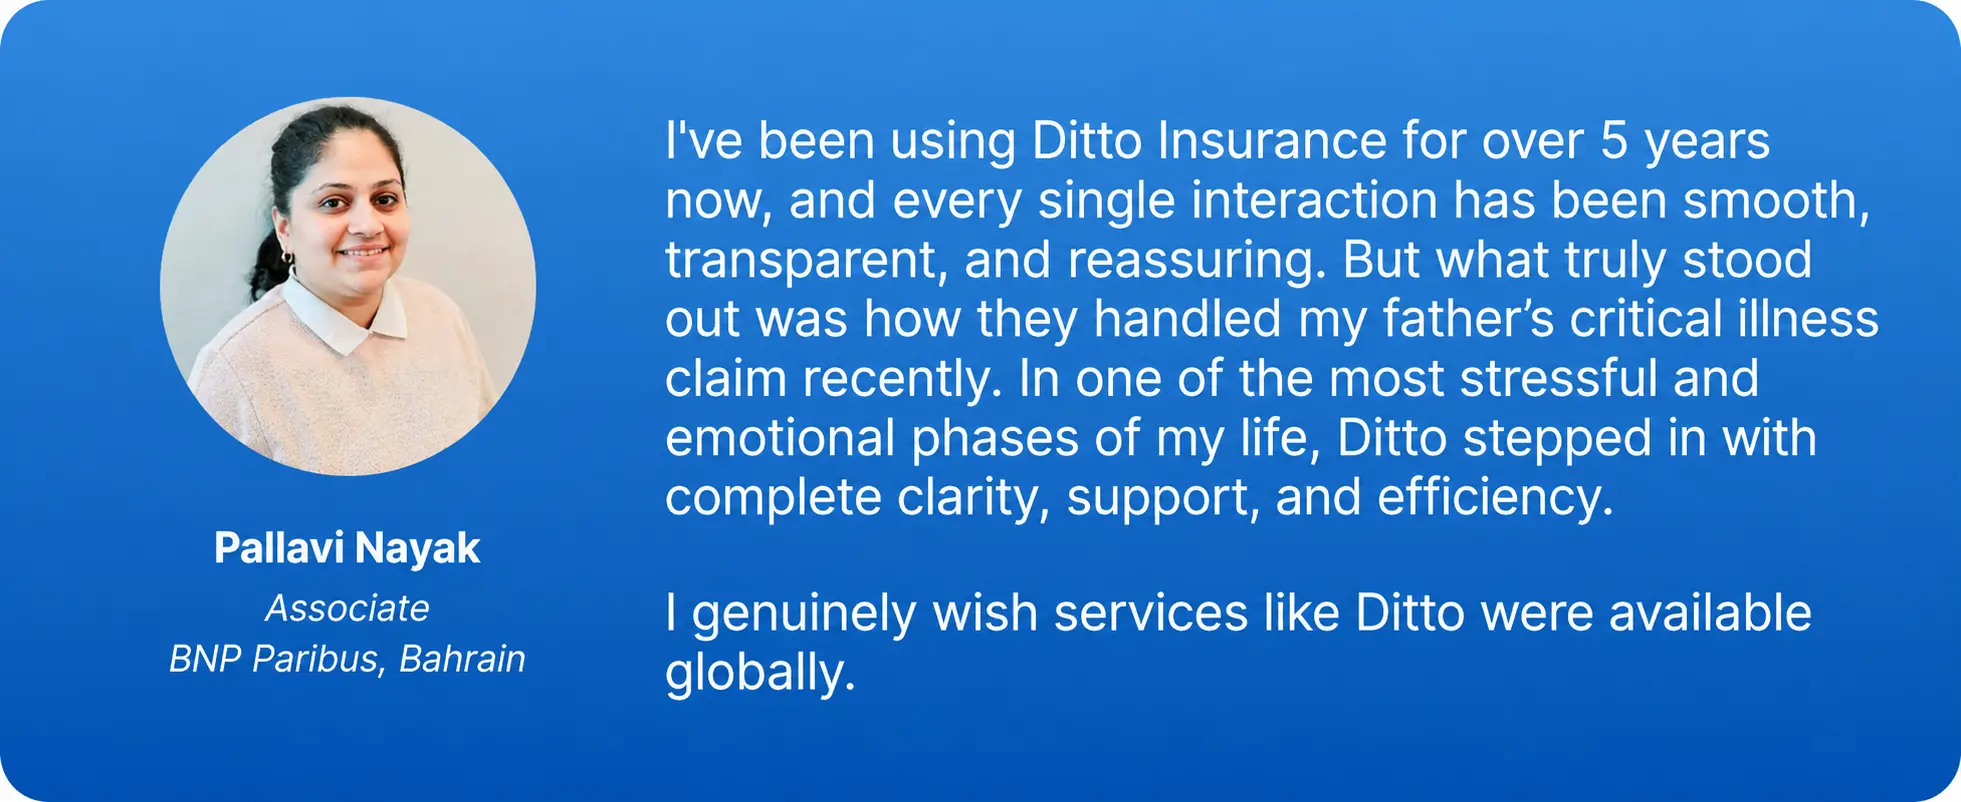
At Ditto, we’ve assisted over 12,00,000 customers choose the right insurance policy. Why customers like Pallavi love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Choosing between a family floater and separate individual policies depends on your existing coverage and health needs. Use these situations to decide what works for your household.
- Both Healthy, Neither Has Insurance: Compare comprehensive family floater plans and choose a cover that suits your preferred hospitals and financial capacity.
- Both Already Have Strong Individual Policies: Retain your existing policies if they offer suitable coverage and benefits. Switch to a family floater only if it provides a clear advantage without sacrificing valuable continuity benefits.
- One Spouse Has an Older Policy, the Other Is Uninsured: Preserve the older policy and its accumulated benefits. Explore adding your spouse or buying a separate policy, depending on the insurer's rules and available coverage.
Ultimately, choose coverage that protects both partners without compromising existing benefits. Compare the best health insurance plans based on coverage, exclusions, hospital networks, and long-term affordability before deciding.
Frequently Asked Questions
Last updated on: