

Overview
Choosing between Go Digit and Aditya Birla Health Insurance? Both offer comprehensive health plans, but their approach to coverage differs. While Go Digit focuses on digital convenience and flexible add-ons, Aditya Birla stands out for its wider range of plans and wellness-focused benefits.
This guide compares their features, premiums, and hospital networks to help you decide which insurer fits your healthcare needs.
About the Insurers
Go Digit Health Insurance
Incorporated in 2016 and operational since 2017, Go Digit is a listed private-sector general insurer with IRDAI registration number 158. Backed by Fairfax Financial, it offers motor, health, and other general insurance products.
Aditya Birla Health Insurance
Aditya Birla Health Insurance Company Limited was incorporated in April 2015 and began operations in October 2016. It is a standalone health insurer with IRDAI registration number 153. Its major shareholders include Aditya Birla Capital, holding 45.89%, and South Africa's Momentum Group, holding 44.08%.
Talk to an expert
today and
find
the right
insurance for you.
Go Digit and Aditya Birla: Performance Metrics
Note: This data is sourced from the IRDAI annual reports, Go Digit public disclosures, and Aditya Birla public disclosures. For more data on insurer metrics, explore Ditto Data Lab.
Digit Infinity Wallet vs. Aditya Birla Activ One MAX: Key Features Compared
Digit Infinity Wallet and Aditya Birla Activ One MAX offer comprehensive health coverage with flexible add-on options.
- Sum Insured: Activ One MAX offers coverage from ₹5 lakh to ₹2 crore, while Infinity Wallet provides ₹2 lakh to ₹3 crore. Both plans cover eligible domiciliary, daycare, and AYUSH treatments up to the sum insured.
- Co-Payment: Neither plan has mandatory co-payment. The insurer covers eligible treatment expenses up to the available sum insured, subject to the policy terms.
- Room Rent: Both plans offer room flexibility without a room rent limit. You can choose from shared rooms, single rooms, deluxe rooms, or other available categories without a separate room rent cap.
- Pre- and Post-Hospitalization: Activ One MAX covers medical expenses for 90 days before hospitalization and 180 days after discharge. Infinity Wallet, on the other hand, offers 60 days of pre-hospitalization and 180 days of post-hospitalization coverage.
- Restoration Benefit: Activ One MAX offers unlimited restoration from the second claim of the policy coverage for any illness. Infinity Wallet provides unlimited restoration up to the base sum insured for any illness (subject to other terms and conditions).
- Cumulative Bonus: Activ One MAX offers Super Credit, which increases the sum insured by 100% each year, up to 500% (max. up to ₹3 crore), irrespective of claims. Infinity Wallet adds 50% for every claim-free year, capped at 100% of the base sum insured.
- Ambulance Cover: Activ One MAX covers road ambulance expenses up to the sum insured but does not cover air ambulances. Infinity Wallet covers road ambulance expenses up to 1% of the base sum insured, capped at ₹15,000, and also includes emergency air ambulance cover.
- Consumable Cover: Activ One MAX includes consumable coverage as a built-in benefit. Infinity Wallet offers this protection through an optional add-on.
Add-Ons Offered
Digit Infinity Wallet
Consumable Cover
Advance Care
Infinite Cumulative Bonus
Aditya Birla Activ One MAX
- Chronic Care Add-on: This add-on provides Day 1 hospitalization coverage for specified conditions, including diabetes, hypertension, and obesity, etc. It is subject to underwriting and can involve additional loading. Once selected at inception, it cannot be removed during the policy lifetime.
- Reduction in Pre-Existing Disease Waiting Period: This add-on reduces the standard three-year waiting period to one or two years, subject to the condition and underwriting. It cannot be removed during the policy lifetime once selected at purchase.
Note: The features and riders listed above are not exhaustive. For complete details, refer to the respective insurer's policy brochure and policy wording.
Apart from their flagship plans, Go Digit and Aditya Birla Health Insurance offer other health insurance options. You can also explore Digit Double Wallet and Digit Worldwide Treatment from Go Digit. Other Aditya Birla Health Insurance plans include Activ Fit Plus and Activ Fit Preferred.
Sample Premiums Comparison by Age and Cover
Note: The premiums shown are indicative quotes for a Delhi resident (pincode: 110001) with a ₹15 lakh sum insured. Actual premiums may vary based on age, location, medical history, applicable discounts, and selected add-ons.
Pros and Cons of Go Digit and Aditya Birla
Pros of Go Digit Health Insurance
- Select plans offer air ambulance coverage, which can help policyholders manage emergency medical transportation costs.
- Go Digit publishes transparency reports that offer insights into its operations, claims performance, and customer service practices.
- As of September 30, 2026, Go Digit General Insurance reported a solvency ratio of 2.40x compared to Aditya Birla’s 1.56x.
Cons of Go Digit Health Insurance
- Go Digit has a comparatively smaller health insurance portfolio, which can indicate a less extensive presence in the health insurance market.
- Consumables coverage requires an optional add-on, which increases the overall premium.
- Go Digit receives slightly more complaints per claim than Aditya Birla, although its complaint levels remain below the industry average.
Pros of Aditya Birla Health Insurance
- Aditya Birla offers a wider hospital network, giving policyholders access to more healthcare facilities across different locations.
- With Aditya Birla Health Insurance's HealthReturns, policyholders can earn rewards which can be used to offset a portion of their annual premium.
Cons of Aditya Birla Health Insurance
- The Aditya Birla Health Insurance claim settlement ratio is comparatively lower than the Go Digit Health Insurance claim settlement ratio, so customers may want to review the insurer's claims performance before purchasing. However, the metric is well above the industry average.
- Aditya Birla reports a comparatively lower ICR, indicating that a smaller share of its health insurance premium income went towards settling claims during the period. However, it is still in a healthy range of 55% to 85%.
Why Choose Ditto for Health Insurance?
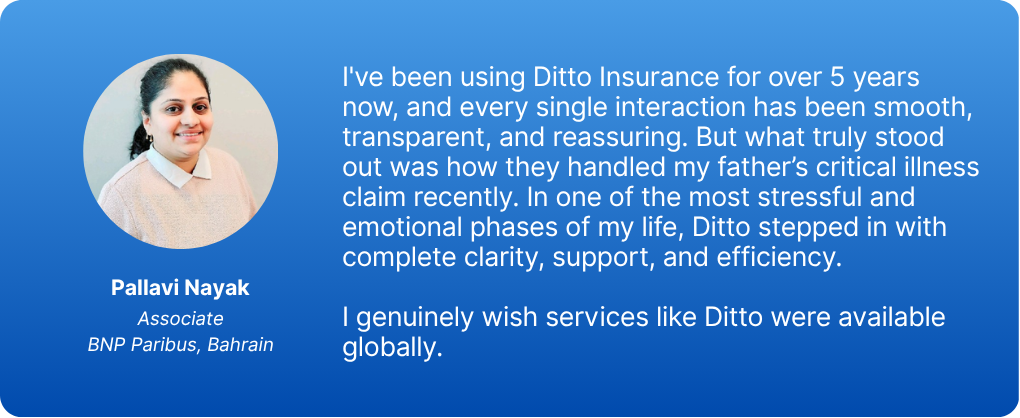
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Pallavi love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Aditya Birla Health Insurance suits buyers who prioritize a wider hospital network and comprehensive wellness benefits. Its Activ One MAX plan also features among the five best health insurance plans, making it worth considering for extensive coverage.
Go Digit Health Insurance can suit younger buyers who prefer digital-first services, simple onboarding, and online claims support. However, its long-term value will depend on claims experience, underwriting performance, and business growth.
Frequently Asked Questions
Last updated on: