

Overview
Imagine your father bought a life insurance policy 15 years ago, passed away, and nobody in the family knew it existed. That payout could still be sitting with the insurer today, completely unclaimed. And this isn't a rare story.
According to the Ministry of Finance, ₹8,973.89 crore in unclaimed insurance amounts was outstanding with insurers as of February 28, 2026.
Low insurance literacy is a major reason this keeps happening, as is the lack of a system to alert families when a payout is due. To close exactly these gaps, IRDAI set up the Policyholders' Education and Protection Fund (PEPF), a new ₹800 crore institutional fund dedicated to policyholder welfare.
In this article, we'll walk you through what the PEPF is, why IRDAI created it, how the fund will actually be used, and how you can check if you or a family member has unclaimed insurance money waiting. We'll also cover what this means for you as a policyholder going forward.
What Is the Policyholders' Education and Protection Fund (PEPF)?
The Policyholders' Education and Protection Fund (PEPF) is a dedicated fund created by the Insurance Regulatory and Development Authority of India (IRDAI) in March 2026. It was established under Section 16A of the IRDA Act, 1999, added through the Sabka Bima Sabki Raksha (Amendment of Insurance Laws) Act, 2025 (SBSR Act), a broader set of insurance reforms that received Presidential assent in December 2025.
Think of the PEPF as insurance's version of a public welfare fund, much like the Investor Education and Protection Fund (IEPF) and banks' Depositor Education and Awareness Fund (DEAF).
The core idea is to use a dedicated pool of money, separate from any single insurer's balance sheet, to protect and educate policyholders across the entire industry.
The Timeline So Far
- March 2026: IRDAI formally constitutes the PEPF with an ₹800 crore corpus.
- June 2026: IRDAI releases a consultation paper (exposure draft) proposing how the fund should be governed and used, inviting public comments until July 13, 2026.
- July 28, 2026: At its 137th Authority Meeting in Hyderabad, IRDAI approves the IRDAI (Policyholders' Education and Protection Fund) Regulations, 2026, operationalizing the fund.
These regulations came into force from the date they were published in the Official Gazette, and IRDAI has committed to reviewing them once every three years.
Why Did IRDAI Establish the PEPF?
IRDAI didn't create the PEPF as a policy formality. It's a direct response to three problems that have followed India's insurance industry for years.
Low Insurance Literacy
Mis-Selling
A Growing Pile of Unclaimed Money
Here's what this means in simple terms: money that rightfully belongs to families is stuck with insurance companies simply because nobody knows it exists or how to claim it. The PEPF gives IRDAI a dedicated, reserved pool of money to fund awareness campaigns and build better tracing tools, without depending on any single insurer's budget, in support of the regulator's "Insurance for All by 2047" goal.
Talk to an expert
today and
find
the right
insurance for you.
This isn't new to India's financial sector. Other regulators have run similar funds for years, and IRDAI's PEPF borrows heavily from that playbook:
How Will the PEPF Regulations 2026 Be Used?
Where the Money Comes From
The PEPF's corpus is funded through:
- Grants and donations from the Central government, State governments, IRDAI, and other institutions.
- Penalties collected by IRDAI under the IRDA Act, 1999, and the Insurance Act, 1938.
- Undistributed disgorgement amounts (money insurers were ordered to return to policyholders that was never claimed).
- Contributions made by IRDAI itself.
- Certain unutilized investment income credited back to the corpus.
- Any other sources notified through future regulations.
How the Money Gets Spent
Only the investment income earned on the ₹800 crore corpus is used for actual spending. The corpus itself isn't touched.
- Nationwide insurance literacy and awareness campaigns, including regional-language material.
- Strengthening grievance redressal systems, including platforms like Bima Bharosa.
- Technology-enabled policyholder services, such as proactive alerts during disasters or claim windows.
- Building infrastructure to trace and recover unclaimed insurance amounts.
- Other policyholder-focused initiatives IRDAI notifies from time to time.
A Fund Management Committee oversees how the money is governed, allocated, and monitored for results, similar to how the IEPF Authority runs India's investor protection fund, or how the RBI administers DEAF for bank depositors.
In effect, the PEPF brings the insurance sector in line with protections that other parts of India's financial system have had for years.
How to Check for Unclaimed Insurance Amounts?
You don't have to wait for PEPF-funded tracing systems to check this today. IRDAI already runs a free, centralized way to search for unclaimed insurance money through the Bima Bharosa portal.
- Visit the Bima Bharosa Unclaimed Amount page.
- You can use the insurer links listed there or submit IRDAI’s unclaimed amount query form. The current form asks for the policyholder’s name, mobile number, date of birth, contact details, selected insurer, and policy number. PAN is optional.
- You can select up to five insurers. If an amount is identified, complete the claim directly with the insurer using the documents it requests.
You can also check directly with individual insurers. Life Insurance Corporation of India (LIC) and Axis Max Life, for instance, both run their own unclaimed amounts pages where you can search using your policy number, PAN card, policyholder’s name, or date of birth.
If you find a match, contact the insurer directly with your ID proof and policy details to start the claim process.
Note
What Does the PEPF Mean for Policyholders?
For an everyday policyholder, you won't interact with the PEPF directly. You won't get a bill or a login for it. What you should expect instead is a gradual, cumulative improvement in a few areas:
Better Awareness Content
More explainer campaigns and regional-language material over the next few years.
Better Grievance Handling
Continued investment in platforms like Bima Bharosa should streamline complaint resolution.
Fewer Missed Payouts
The fund aims to improve tracing and outreach so policyholders and nominees can more easily identify unclaimed amounts.
Proactive Alerts
Tech-enabled alerts, especially during disasters, could help policyholders act faster on claims.
As you can see, the fund is designed to work quietly in the background, not change how you buy a policy or file a claim today. Its real test will be execution, since the regulations were approved only in July 2026 and the Fund Management Committee's work is just getting started.
Why Choose Ditto for Insurance?
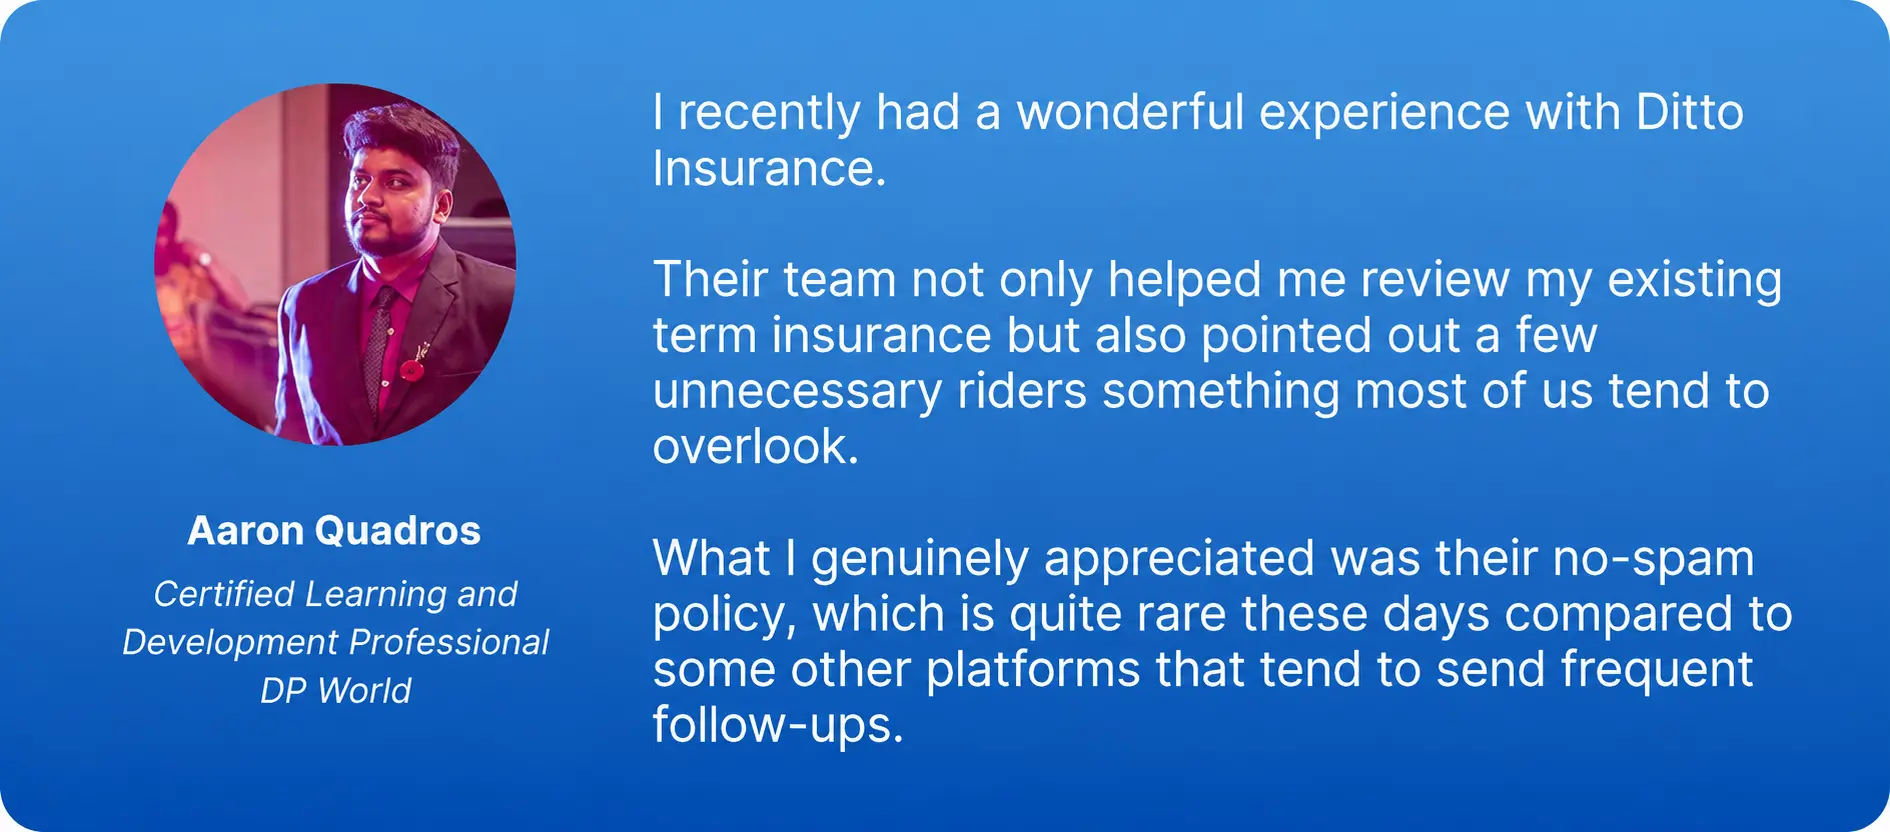
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
The Policyholders' Education and Protection Fund is IRDAI’s response to long-standing gaps in insurance awareness, policyholder support, and tracing unclaimed amounts.
An ₹800 crore fund, backed by formal regulations and a dedicated committee, is a meaningful step. But funds like this only work if people actually use the systems built with them.
Our advice: don't wait for PEPF's awareness campaigns to reach you. Check the Bima Bharosa portal today for any unclaimed amount under your name or a family member's name. Make sure your own policies have updated nominee details, and that at least two or three people close to you know these policies exist.
Frequently Asked Questions
Last updated on: