

Overview
What happens if a worker gets injured on the job and suddenly can’t earn the way they used to?
That’s where labour insurance can help. Depending on the type of cover, it can provide financial support for work-related injuries, disabilities, occupational illnesses, and even death.
But there is no single labour insurance policy, and the rules can get confusing quickly. Different workers may be covered under different schemes, with different eligibility criteria, benefits, and claim processes.
So, in this guide, we’ll break down what labour insurance means in India, the different types of protection available, who can qualify, what benefits they offer, and where the coverage may still fall short.
What Is Labour Insurance in India?
“Labour Insurance” is not a separate insurance category recognized by IRDAI or a single government scheme. The term is commonly used to describe different forms of insurance for labour, such as Employees’ State Insurance (ESI), Employee’s Compensation Insurance (ECI), construction worker welfare benefits, and accident or life insurance schemes available to eligible workers.
- ESI: Provides medical and cash benefits to eligible employees and their dependents.
- ECI: Covers an employer’s liability for qualifying work-related injuries, occupational diseases, disability, or death.
- Construction Worker Welfare Boards: Provide separate welfare benefits to eligible, registered construction workers.
Note: For employers, Employee’s Compensation Insurance (ECI) can help transfer eligible statutory liabilities arising from workplace injuries, occupational diseases, disability, or death. Since November 21, 2025, these liabilities have been governed by the Employee’s Compensation provisions under Chapter VII of the Code on Social Security, 2020, which subsumed the earlier Employees’ Compensation Act, 1923.
Importantly, these provisions generally apply where the Code's ESI provisions do not apply. Therefore, a private Employee’s Compensation policy should not be treated as a substitute for mandatory ESI coverage.
However, the legal obligation to provide eligible compensation does not automatically mean an employer must purchase an insurance policy. Employers may use insurance to manage covered compensation liabilities, but the underlying statutory responsibility remains governed by the applicable law.
Talk to an expert
today and
find
the right
insurance for you.
Types of Labour Insurance: ESI, Workmen's Compensation and Labour Card Schemes
Take Note: An e-Shram Card is not automatic insurance. It is a national database and welfare-access platform for unorganized workers. It covers categories such as construction workers, migrant workers, domestic workers, and agricultural workers.
Registration can help workers access eligible social security schemes, but the benefits they receive depend on each scheme's eligibility criteria and rules.
According to the Press Information Bureau (PIB), as of August 25, 2026, over 31.89 crore unorganized workers had registered on the e-Shram portal.
What Is an ESIC Number?
Who Is Eligible and How to Register for Labour Insurance?
Government-Backed Social Schemes
- Eligibility for ESI Scheme: Under the current framework, ESI generally applies to establishments with 10 or more employees. Eligible employees do not purchase ESI independently, unlike private insurance. The employer handles registration and enrolls eligible employees under the scheme.
- How to Register for ESI: The employer submits the employee’s details, family information, residence, and selected dispensary through the ESI portal. The employee receives a unique ESI Insurance Number, which remains valid for life, including when changing employers. If a worker moves from Factory A to Factory B, they should provide their existing ESI number to the new employer rather than obtain a new one.
Private Insurance Plans
- Eligibility: Unlike statutory schemes such as ESI, private plans like ICICI Lombard Workmen Compensation Policy generally do not have a worker-level income ceiling or a fixed minimum employee count. Coverage can extend to manual, construction, electrical, warehouse, and service-sector workers, subject to policy terms.
- How to Register: The employer or contractor purchases the policy by providing business details, risk location, worker categories, wage information, contractor details, claims history, and required add-ons. Insurers such as ICICI Lombard offer online purchase and business insurance assistance. The policy schedule then records the covered workers, locations, work activities, declared wages, limits, and selected add-ons.
Benefits, Cover Limits and How to File a Claim for Labour Insurance
Benefits of Government-Backed Schemes Like ESI
Medical Benefits
From the first day of insurable employment, ESI provides access to medical treatment through authorized dispensaries and hospitals, covering primary, secondary, and tertiary care.
Sickness Benefit
Eligible employees receive 70% of average daily wages for up to 91 days. Extended sickness benefit can provide 80% for up to 730 days for specified diseases.
Maternity Benefit
ESI provides maternity cash benefits at 100% of average daily wages, subject to applicable contribution and eligibility conditions.
Disablement Benefit
Temporary disablement provides 90% of wages during incapacity. Permanent disablement benefits depend on the assessed loss of earning capacity.
Dependents and Funeral Benefits
Eligible dependents can receive 90% of wages as a periodic pension following employment-injury death. Funeral expenses of ₹15,000 are also payable, subject to applicable conditions.
Take Note: Under the current ESIC wage eligibility rules, the wage ceiling for coverage is ₹21,000 per month. For persons with disabilities, the ceiling is ₹25,000 per month. These limits have been effective since January 1, 2017, subject to applicable ESIC rules.
How to File an ESI Claim?
- Medical Treatment: Use your ESI Insurance Number or e-Pehchan Card to access treatment through your allotted ESI medical facility or an authorized referral network.
- Cash Benefits: Eligible insured persons can submit claims for sickness, extended sickness, maternity, and temporary disablement benefits through the IP Portal. You can also track claim status online.
- Work-Related Accidents: Inform your employer immediately after an accident. The employer must report qualifying workplace accidents to ESIC through the applicable process, including Accident Report Form 12.
- Funeral Expenses: Eligible claimants can apply using Form 22, along with the required proof of death and documents establishing their eligibility.
Benefits of Private Plans From Insurers
- Work-Related Death: Provides compensation to eligible dependents when a covered employee dies due to a work-related accident or occupational cause.
- Permanent Total Disablement: Covers statutory compensation payable when a covered workplace injury results in permanent total disablement.
- Permanent Partial Disablement: Provides compensation based on the assessed loss of earning capacity caused by a covered permanent partial disability.
- Temporary Disablement: Provides periodic compensation for eligible temporary disablement resulting from a covered workplace injury.
- Legal Defense Costs: Can cover eligible legal expenses incurred in defending a compensation claim, where covered and incurred with the insurer’s consent.
- Medical Expenses: Medical expenses are not automatically included. Medical Expenses Cover is available as an optional add-on.
- Occupational Diseases: Occupational disease coverage is available through an optional add-on, subject to the applicable policy terms and conditions.
Claim Process
Raise the Claim
Notify the insurer about the incident through its prescribed claim channels.
Survey and Assessment
The insurer may appoint a surveyor to assess the loss or incident and determine the documents required.
Submit Documents
Provide the requested documents and information through the insurer’s designated process.
Claim Verification
The insurer reviews the submitted documents and assessment report before deciding on the claim.
Settlement
Once the assessment is complete, the insurer communicates the settlement amount and completes the required formalities.
Claim Payment
After approval and completion of KYC or other requirements, the insurer pays the approved claim amount to the policyholder.
Labour Insurance vs. Private Health and Term Insurance: Do You Still Need Cover?
Labour insurance can provide important financial protection for workers and their families. However, these benefits are usually linked to specific schemes, eligibility rules, or employment conditions. They may not cover every healthcare expense or provide enough financial support after a worker’s death.
Private health and term insurance can fill these gaps. Health insurance can offer broader medical protection, while term insurance can provide a larger death benefit to protect dependents and replace lost income.
Why Choose Ditto for Insurance?
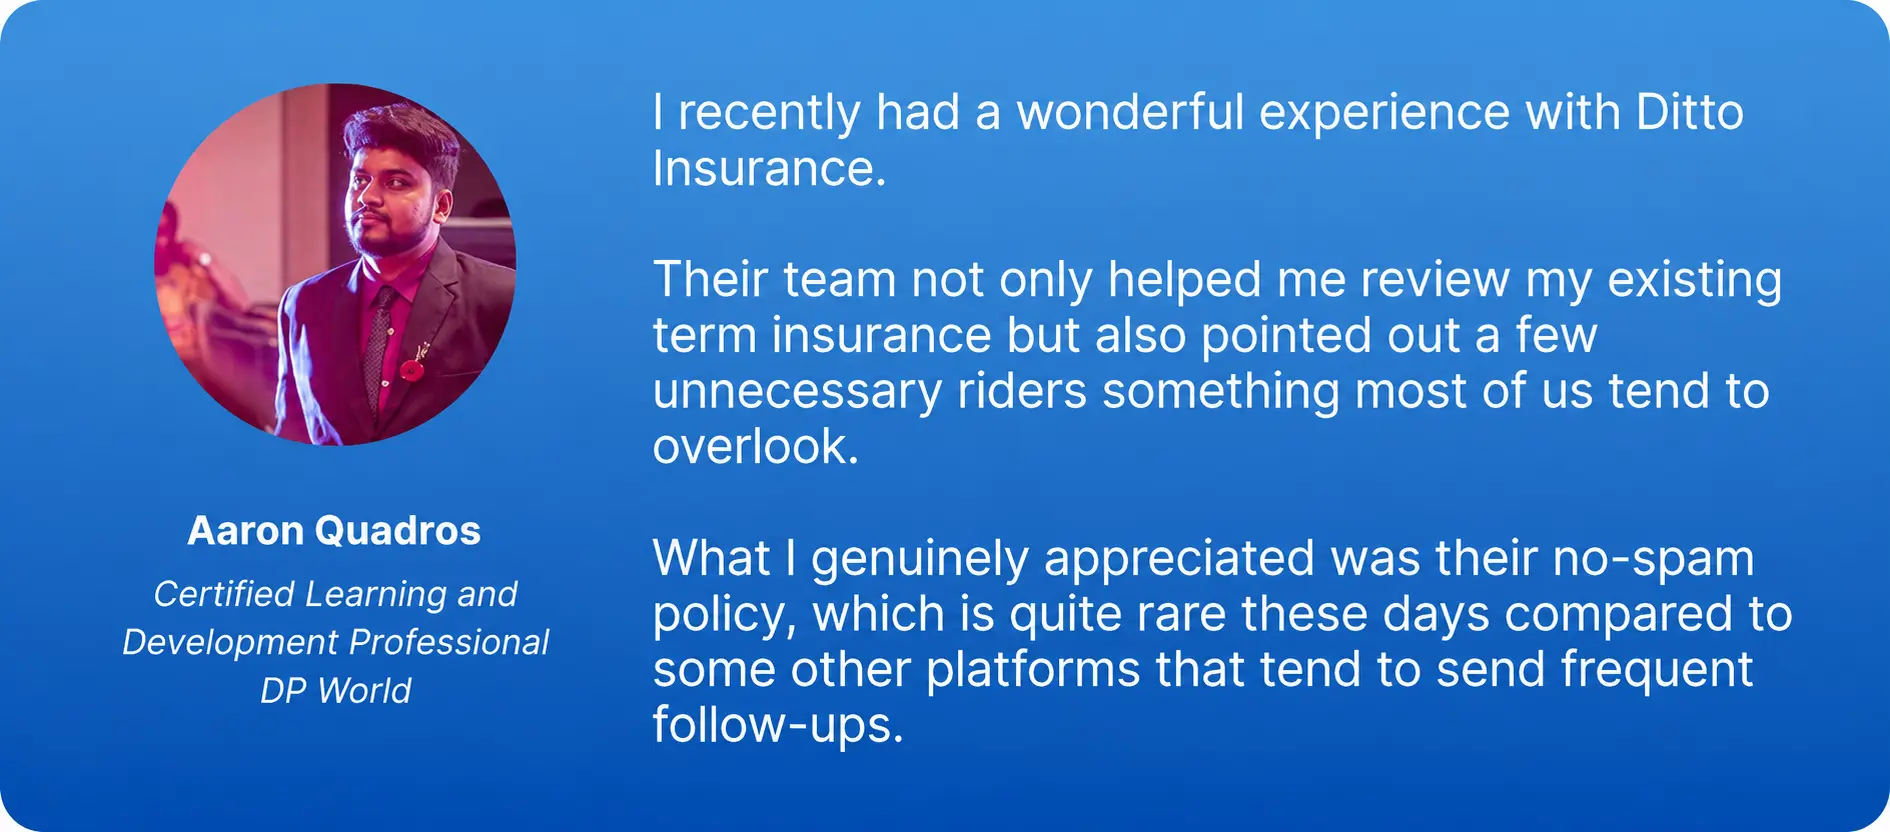
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Labour insurance can provide valuable protection against workplace accidents, employment injuries, and other risks covered under specific worker welfare schemes. However, it should not be treated as a complete substitute for personal insurance. The extent of protection depends on the scheme, employment status, and eligibility rules.
For broader financial protection, workers can consider the best health insurance plans for medical expenses and the best term insurance plans for income replacement and family protection. These covers remain useful beyond the workplace.
However, if eligibility or higher premiums are a concern, which is often the case for this population, consider standardized options such as Saral Jeevan Bima and Arogya Sanjeevani.
Disclosure: Ditto currently offers advisory services only for health insurance and term life insurance. We do not advise on the government schemes or other labour insurance products discussed in this article. This article is intended for educational purposes only and should not be treated as insurance advice or a recommendation to purchase any specific product or scheme.
Frequently Asked Questions
Last updated on: