Term Insurance

SUD Life Smart Term Plan: Features & Premiums

Moushmi Kaur

Written by Moushmi Kaur

Insurance Writer

Gaurav Bhat

Reviewed by Gaurav Bhat

IRDAI-Certified Expert at Ditto

SP0738578124

Certified
SUD Life Smart Term Plan: Features & Premiums

Overview

The SUD Life Smart Term Plan is a non-linked, non-participating pure-risk individual life insurance plan with no maturity benefit offered by Star Union Dai-ichi Life Insurance. 

Key Features

  • Life Cover: Flexible sum assured options to suit individual budgets and protection needs.
  • Policy Term: Flexible policy durations of 10 to 50 years.
  • Premium Payment Term: Regular pay or limited pay options of 7, 10, or 15 years.
  • Death Benefit Payout: Lump sum, monthly income, or a combination of both.
  • Life Stage Upgrade: Increase your base sum assured by up to 50% on marriage and 25% on other key milestones, subject to an overall cap of 100%.
  • Tax Benefits: Eligible premiums may qualify for deductions of up to ₹1.5 lakh under Section 123 (formerly Section 80C) of the Income Tax Act, 2025, if you opt for the old tax regime. Death benefits are tax-exempt under Schedule II(2) (formerly Section 10(10D)), subject to applicable conditions.

The SUD Life Smart Term Plan (UIN: 142N096V01), offered by Star Union Dai-ichi Life Insurance, is worth evaluating for its customization options. However, the lack of riders and restrictions on certain features are important considerations. 

Let's look at its eligibility, benefits, premiums, and insurer performance to help you decide whether it meets your protection needs.

Eligibility Criteria for SUD Life Smart Term Plan

ParameterDetails
Entry Age18 to 65 years
Maturity Age28 to 85 years
Minimum Sum Assured₹25 lakh
Maximum Sum AssuredNo-Limit (Subject to underwriting)
Premium Payment TermRegular pay, limited pay: 7, 10, or 15 years
Policy Term10 to 50 years (Regular pay and 7-year limited pay)15 to 50 years (10-year limited pay)20 to 50 years (15-year limited pay)
Premium Payment FrequencyAnnual, half-yearly, quarterly, or monthly

Note: The premium depends on several factors, including the policyholder's age, gender, sum assured, policy term, and premium payment term. SUD Life also considers the policyholder's source of income, employment status, and whether they are a first-time insurance buyer or an existing SUD Life policyholder.

Key Features of SUD Life Smart Term Plan

1) Pure Protection With No Maturity Benefit

The SUD Life Smart Term Plan is a pure risk policy. The nominee receives the applicable death benefit if the life assured passes away during the policy term. However, no maturity benefit is payable on survival.

2) Flexible Death Benefit Payout

The plan offers three payout options:

    • Lump Sum: The entire death benefit is paid immediately.
    • Monthly Income: 1% of the death benefit is paid monthly for 125 months.
    • Lump Sum Plus Monthly Income: 50% is paid immediately, followed by 0.50% of the death benefit monthly for 125 months.

The policyholder can change the selected payout option during the policy term.

3) Life Stage Upgrade

Policyholders can increase their base sum assured following qualifying life events:

Life EventMaximum Increase
Marriage50%
First Child25%
Second Child25%
Home Loan25%
Education Loan For Children25%

The total increase cannot exceed 100% of the base sum assured, subject to a maximum of ₹50 lakh per event.

Conditions: You must select this at inception, and it is available only under regular pay policies. 

    • Submit requests within six months of the qualifying event and before age 50. 
    • At least 10 years of outstanding policy term and premium payment term must remain, and no previous claim should have been made. 
    • Any increase in the sum assured attracts an additional premium, calculated based on the policyholder’s attained age and the remaining policy term at the time of the increase.

4) Flexible Premium Payment Options

Policyholders can choose regular pay, where premiums are paid throughout the policy term, or limited pay options of 7, 10, or 15 years.

5) Special Exit Value

The plan allows eligible policyholders to exit at age 60, 61, or 62 and receive 100% of the total base plan premiums paid, excluding extra premiums.

Conditions: The policy term must be at least 40 years, maturity age must be at least 70 years, and the policy must be active. Moreover, the Life Stage Upgrade must not have been exercised.

6) Premium Discounts 

SUD Life offers the following discounts:

    • First-Time Insurance Buyers: 5% on the first-year annualized premium.
    • Salaried Individuals: 5% on the first-year annualized premium.
    • Female Policyholders: 10% on the annualized premium throughout the payment tenure.
    • Existing SUD Life Policyholders: 5% on the first-year annualized premium, provided their existing policy is active.

7) Grace Period

The standard grace period is 15 days for monthly premiums and 30 days for other payment frequencies. An extended grace period of 15 additional days for monthly payments and 60 days for other modes is also available, subject to conditions.

8) Tax Benefits

The plan offers tax benefits under the Income Tax Act, 2025, subject to applicable conditions. Premiums paid may qualify for deductions of up to ₹1.5 lakh under Section 123 (formerly Section 80C) if you opt for the old tax regime. Additionally, death benefits are generally tax-exempt under Schedule II (formerly Section 10(10D)), subject to applicable conditions. Read our guide on term insurance tax benefits for more details.

Note: The plan does not offer any riders.

Sample Premiums by Age and Sum Assured

The SUD Life Smart Term Plan brochure provides indicative annual premiums ranging from ₹4,291 to ₹41,480 for non-smoker male policyholders aged 25 to 45, across sum assured options of ₹25 lakh to ₹2 crore, with a maturity age of 60 years. Premiums exclude applicable taxes and extra premiums, and no discounts have been applied.

Entry Age₹25 Lakh₹50 Lakh₹1 Crore₹2 Crore
25 years₹4,291₹6,013₹8,839₹16,562
30 years₹4,958₹7,023₹10,371₹19,666
35 years₹5,999₹8,591₹12,751₹24,470
40 years₹7,577₹10,982₹16,418₹31,844
45 years₹9,688₹14,142₹21,211₹41,480

Premiums vary based on age, gender, sum assured, policy term, premium payment term, and underwriting factors. A SUD Life term plan calculator can help estimate the premium for different coverage amounts and policy terms. 

Ditto's Take: Don't choose a term plan based on affordability alone. Compare premiums, claim settlement track records, and coverage features across insurers.

SUD Life: Performance Metrics

Key Operational MetricsSUD Life (Average FY 24-26)Industry Average
Claim Settlement Ratio (CSR)98.82%99.00% (Mean)
Amount Settlement Ratio (ASR) (Average FY 23-25)95.80%94.83% (Mean)
Complaint Volume (Per 10,000 Claims)17.6713.10 (Median)
Solvency Ratio2.00x2.0x (Median)
Annual Business Volumes (in Crore)₹4,243.99₹3,778.58 (Median)
Amount Paid in Death Claims (in Crore)₹142.27₹237.24 (Median) 

Note: The SUD Life claim settlement ratio stood at 98.82%, slightly below the industry average of 99%. Its complaint volume was also higher than the industry median, making claims experience an important factor to consider.

The figures are for the insurer as a whole and are sourced from SUD Life Insurance’s public disclosures and IRDAI annual reports. For more data on life insurers' track record, visit the Ditto Data Lab.

Talk to an expert
today and find
the right
insurance for you.
Ditto Advisor

Pros and Cons of SUD Life Smart Term Plan

Pros

    • Life Stage Upgrade lets policyholders increase their cover at key life milestones, subject to eligibility conditions.
    • Flexible death benefit payouts through lump sum, monthly income, or a combination of both.
    • Special discounts for female policyholders (10%), first-time buyers (5%), and salaried individuals (5%).

Cons

    • No riders, including ones we at Ditto consider a major value-add, like critical illness benefits or waiver-of-premium options.
    • Relatively modest business scale, with a claim settlement ratio of 98.82%, slightly below the industry average of 99%. Its complaint volume is also higher than the industry median, at 17.67 complaints per 10,000 claims (average FY 2024–26).
    • The plan misses several features offered by leading term insurance policies, including terminal illness benefits, premium break options, health management services, and instant partial claim payouts.

Why Choose Ditto for Term Insurance?

At Ditto, we’ve assisted over 12,00,000 people with choosing the right insurance policy. Why customers like Aaron below love us:
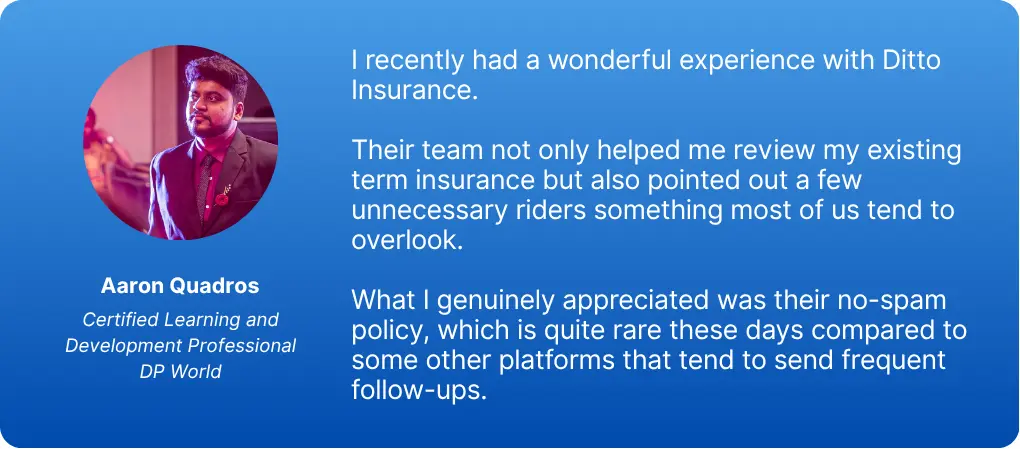
Aaron Quadros LinkedIn Testimonial
    • 100% Free Consultation
    • No Spam. No Sales Pressure.
    • Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
    • Backed by Zerodha
    • Dedicated Claim Support Team
    • Compare Plans and Premiums with a Trusted Insurance Advisor

You can book a FREE consultation. Slots are running out, so make sure you book a call or chat on WhatsApp now!

Conclusion

The SUD Life Smart Term Plan offers basic life cover, flexible payouts, and a useful Life Stage Upgrade. However, the absence of riders limits its flexibility, while its 98.82% claim settlement ratio falls below the industry average of 99.00%.

Larger insurers such as Axis Max Life, ICICI Life, and HDFC Life offer more comprehensive options, including critical illness, accidental disability, and waiver of premium benefits, depending on the plan.

SUD Life is a reasonable option for basic term cover, but it offers little that sets it apart from better-established competitors. Compare it with our best term insurance plans in India before deciding.

Frequently Asked Questions

Does the SUD Life Smart Term Plan offer a maturity benefit?

No. The SUD Life Smart Term Plan is a pure term insurance policy, so it pays no maturity benefit if the policyholder survives the policy term. However, its Special Exit Value feature allows eligible policyholders to exit at age 60, 61, or 62 and receive a refund of eligible base plan premiums paid, excluding extra premiums. This option is subject to conditions, including a minimum policy term of 40 years and a maturity age of at least 70. Exercising it terminates the policy and all life cover.

What happens if I miss a premium payment under the SUD Life Smart Term Plan?

SUD Life offers a 15-day grace period for monthly premiums and 30 days for other payment modes. The life cover remains active during this period. If the premium remains unpaid after the grace period, the policy may lapse. Policyholders can generally apply for revival within five years of the first unpaid premium, subject to payment of outstanding dues, applicable interest, and underwriting requirements. The plan also offers an extended grace period to eligible policyholders after completing five policy years, subject to specific conditions.

Can I increase my life cover under the SUD Life Smart Term Plan after marriage or having a child?

Yes. The Life Stage Upgrade allows policyholders to increase their base sum assured by up to 50% on marriage and 25% for qualifying events such as childbirth, adoption, or certain loans, subject to an overall increase limit of 100%. This feature must be selected at inception under a Regular Pay policy. Submit the request within six months of the qualifying event and before the policyholder turns 50. An additional premium, based on the attained age and remaining policy term, applies to the increased cover. Exercising this benefit also makes the policyholder ineligible for the Special Exit Value.

Can I choose a lump sum or monthly income payout under the SUD Life Smart Term Plan?

Yes. The plan offers three death benefit payout options. The nominee can receive the entire benefit as a lump sum, a monthly income of 1% of the death benefit for 125 months, or a combination of 50% upfront and 0.5% monthly for 125 months. For example, a ₹1 crore death benefit would provide ₹1 lakh per month under the monthly income option. Since installment payouts are spread over time, consider the family’s immediate expenses and long-term financial needs when selecting the payout option.

Can I buy the SUD Life Smart Term Plan if I already have another term insurance policy?

Yes, you can hold multiple term insurance policies from different insurers. However, SUD Life will assess the existing life cover, income, financial obligations, and underwriting eligibility before deciding the additional coverage it can offer. All existing policies and pending applications must be disclosed accurately. Non-disclosure or material misrepresentation can lead to claim-related complications. Since multiple policies also mean multiple premium payments, ensure the combined coverage meets your family's needs without straining your budget.

Can I change the nominee in My SUD Life Smart Term Plan after buying the policy?

Yes. You can generally change your nominee while the policy is active by submitting a nomination change request to SUD Life. You may need to provide the new nominee's name, relationship with the policyholder, date of birth, and other required details. The insurer must record the change. If the policy has been assigned to someone else, additional restrictions may apply. Review your nomination after major life events such as marriage, divorce, or the birth of a child.

Does the SUD Life Smart Term Plan offer any discount for non-smokers or healthy individuals?

Non-smokers may qualify for lower premiums, as tobacco use is an important factor in life insurance underwriting. However, SUD Life does not advertise a separate fixed-percentage discount for healthy individuals. The plan offers a 10% premium discount for female policyholders and a 5% first-year discount for eligible first-time buyers, salaried individuals, and existing SUD Life customers. The final premium also depends on age, medical history, and underwriting assessment. Use SUD Life's official premium illustration tool to check the applicable rates.

Does the SUD Life Smart Term Plan offer an extended grace period?

Yes. After completing five policy years, eligible policyholders can request an extended grace period of an additional 15 days for monthly premiums or 60 days for other payment modes. The policy must be active, and you must inform SUD Life before the premium due date. You can use the extension again only after another five policy years. The life cover remains active during the extended period, subject to policy terms.

Last updated on: