

Overview
With three plan options and two cover variants, the iSelect Smart360 Term Plan by Canara HSBC Life Insurance gives you plenty of ways to customize your coverage. But more choices don't necessarily mean better protection.
So, before picking a variant, it is worth looking at what each option actually offers. In this guide, we break down the plan’s key features, riders, insurer track record, and whether it can meet your long-term financial protection needs.
What Is the Canara HSBC Life iSelect Smart360 Term Plan?
iSelect Smart360 Term Plan (UIN: 136N080V02) is a Canara HSBC Life term insurance product. It is a non-linked, non-participating, individual pure-risk life insurance plan. You can purchase it online through Canara HSBC Life’s website, partner websites, or through the insurer’s sales representatives and distributors.
Eligibility Criteria
Talk to an expert
today and
find
the right
insurance for you.
Canara HSBC Life iSelect Smart360 Plan Options, Key Features, and Riders
Plan Options
Life Secure
Both the life assured and spouse can be covered under the same policy, subject to eligibility and applicable conditions. If the life assured or covered spouse dies during the policy term, the applicable sum assured on death is paid, subject to the selected coverage option and policy terms.
Life Secure with Income
A monthly survival income is payable from the policy anniversary coinciding with or following the life assured's 60th birthday, continuing until maturity or death. If the life assured dies during the policy term, the sum assured on death, reduced by cumulative monthly income already paid, is payable.
Life Secure with Return of Premium
If the life assured dies during the policy term, the applicable sum assured on death is paid, and the policy terminates. If the life assured survives until maturity, the sum assured on maturity (base premiums) is paid, after which the policy terminates.
Note: At Ditto, we do not recommend Return of Premium (ROP) plans. They can cost 60%–100% more than standard term plans, sometimes even more, simply to return your base premiums on maturity.
Key Features
- Level Cover Option: Your sum assured stays unchanged throughout the policy term. If you choose regular pay, you can increase the cover up to three times after specific events, subject to the life stage cover enhancement terms.
- Increasing Cover Option: Your sum assured increases by 10% every policy year on a simple-interest basis, provided the policy remains in force. The total increase is capped at 100% of the original sum assured, excluding optional in-built covers.
- Life Stage Cover Enhancement: You can increase your sum assured by 50% after marriage and 25% after childbirth/legal adoption, or buying a new house. You can use this benefit up to three times during the policy term. The request must be made within one year of the event and is available only with Life Secure.
- Flexible Death Benefit Payout: Choose to receive the death benefit as a lump sum, monthly income, or a combination of both, depending on your family's financial needs.
- Terminal Illness Benefit: If you are diagnosed with a terminal illness, you can receive a lump sum benefit of up to ₹2 crore immediately. This is an accelerated benefit, so the death benefit reduces by the amount paid under this benefit. The feature is not available with the Life Secure With Income variant.
- Option to Cover Spouse: Under the Life Secure option, both you and your spouse receive separate life covers under the same policy. After the first death, the affected life’s death benefit is paid, while cover continues for the surviving spouse at a reduced premium. After the second death’s payout, the policy terminates. At Ditto, we recommend opting for separate term plans if both spouses earn individually for simplicity, separate nominees, and rider flexibility.
- Special Exit Value: The Life Secure option offers an early exit value for eligible long-term policies, potentially returning total premiums paid at a specified exit point. The benefit requires a long policy term of 40 years or more and is unavailable with spouse cover, Block Your Premium (BYP), or certain waiver-trigger events.
Optional Built-In Covers
- Accidental Death Benefit (ADB): If the life assured dies solely due to an accident within 180 days of the unfortunate event, the applicable sum assured on death plus the ADB sum assured is paid. The policy then terminates.
- Accidental Total and Permanent Disability (ATPD) Premium Protection: If the life assured suffers from a qualifying disability, all future premiums for the affected life are waived. Other applicable covers continue for the remaining policy term, provided the policy remains in force.
- Accidental Total and Permanent Disability Premium Protection Plus: If the life assured suffers a qualifying disability, the ATPD sum assured is paid as a lump sum and future premiums are waived. Other covers continue for the remaining policy term. You can choose either ATPD Premium Protection or ATPD Premium Protection Plus, not both.
- Child Care Benefit (CCB): This optional benefit provides an additional payout if the life assured or working spouse dies while the covered child is 0 to 21 years old. The CCB sum assured can help fund planned milestones and is available only with the Life Secure option.
- Block Your Premium: You can lock the base premium rate for five years. During this period, you can increase the death benefit by 25%, 50%, 75%, or 100%, as selected at inception, without fresh underwriting or age-based repricing, subject to policy conditions.
Note: The BYP benefit comes at an additional premium. If you exercise the cover increase, you also pay an extra premium for the additional cover at the blocked rate. So, BYP offers pricing flexibility, not free additional coverage.
Canara HSBC iSelect Smart360 Sample Premium Comparison by Age and Cover
The illustration below assumes a salaried, non-smoking male in Delhi (110010) seeking ₹2 crore level term cover until age 65. First-year discounts are excluded. Actual premiums may vary based on underwriting and individual profiles.
Note: Premiums can be higher than those of some established insurers such as Axis Max Life and ICICI Prudential, but the plan can still be competitive against larger insurers like HDFC Life.
Additionally, the plan offers limited illness-based rider options. In contrast, Smart Term Plan Plus offers critical illness protection covering up to 64 illnesses, while ICICI Prudential iProtect Smart Plus and Click 2 Protect Supreme Plus offer coverage for up to 60 illnesses.
The waiver of premium benefit is also relatively restrictive. Under Canara HSBC iSelect Smart360, premium protection is linked to accidental total and permanent disability under the ATPD options. In comparison, plans like Smart Term Plan Plus offer an optional waiver triggered by diagnosis of a listed critical illness and disability.
At Ditto, we recommend riders like waiver of premium and critical illness as they offer real-life protection for the money you pay.
Canara HSBC Life: Performance Metrics
Note: The data in the above table reflects the insurer’s overall performance. It is sourced from Canara HSBC Life Insurance’s public disclosures and IRDAI annual reports. For more insurer-level metrics, explore the Ditto Data Lab.
Pros & Cons of Canara HSBC Life iSelect Smart360
Pros of Canara HSBC Life iSelect Smart360
- Strong Disability Protection: ATPD Premium Protection Plus combines a lump sum payout with premium waiver, while keeping other applicable covers active.
- Spouse Cover: Both lives can remain covered under the same policy. The surviving spouse retains their cover after the first death.
- Useful Child Care Benefit: CCB provides additional protection during the years when your child depends on you financially.
- Early Exit: Eligible Life Secure policies can offer a Special Exit Value, giving you an option to exit later if you no longer need the cover. The feature is a cost-effective alternative to the return of premium option.
Cons of Canara HSBC Life iSelect Smart360
- Income Benefit Reduces Future Death Benefit: Under Life Secure with Income, survival income already paid is deducted from the subsequent Death Benefit.
- Cover Until 99 Is Excessive: Very long-term cover sounds attractive, but most people primarily need protection during their income-earning and family-dependency years.
- ROP Has an Opportunity Cost: Getting your premiums back does not mean you earned investment returns. The amount returned comes without interest, investment returns, or capital gains.
Did You Know?
Why Choose Ditto for Term Insurance?
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
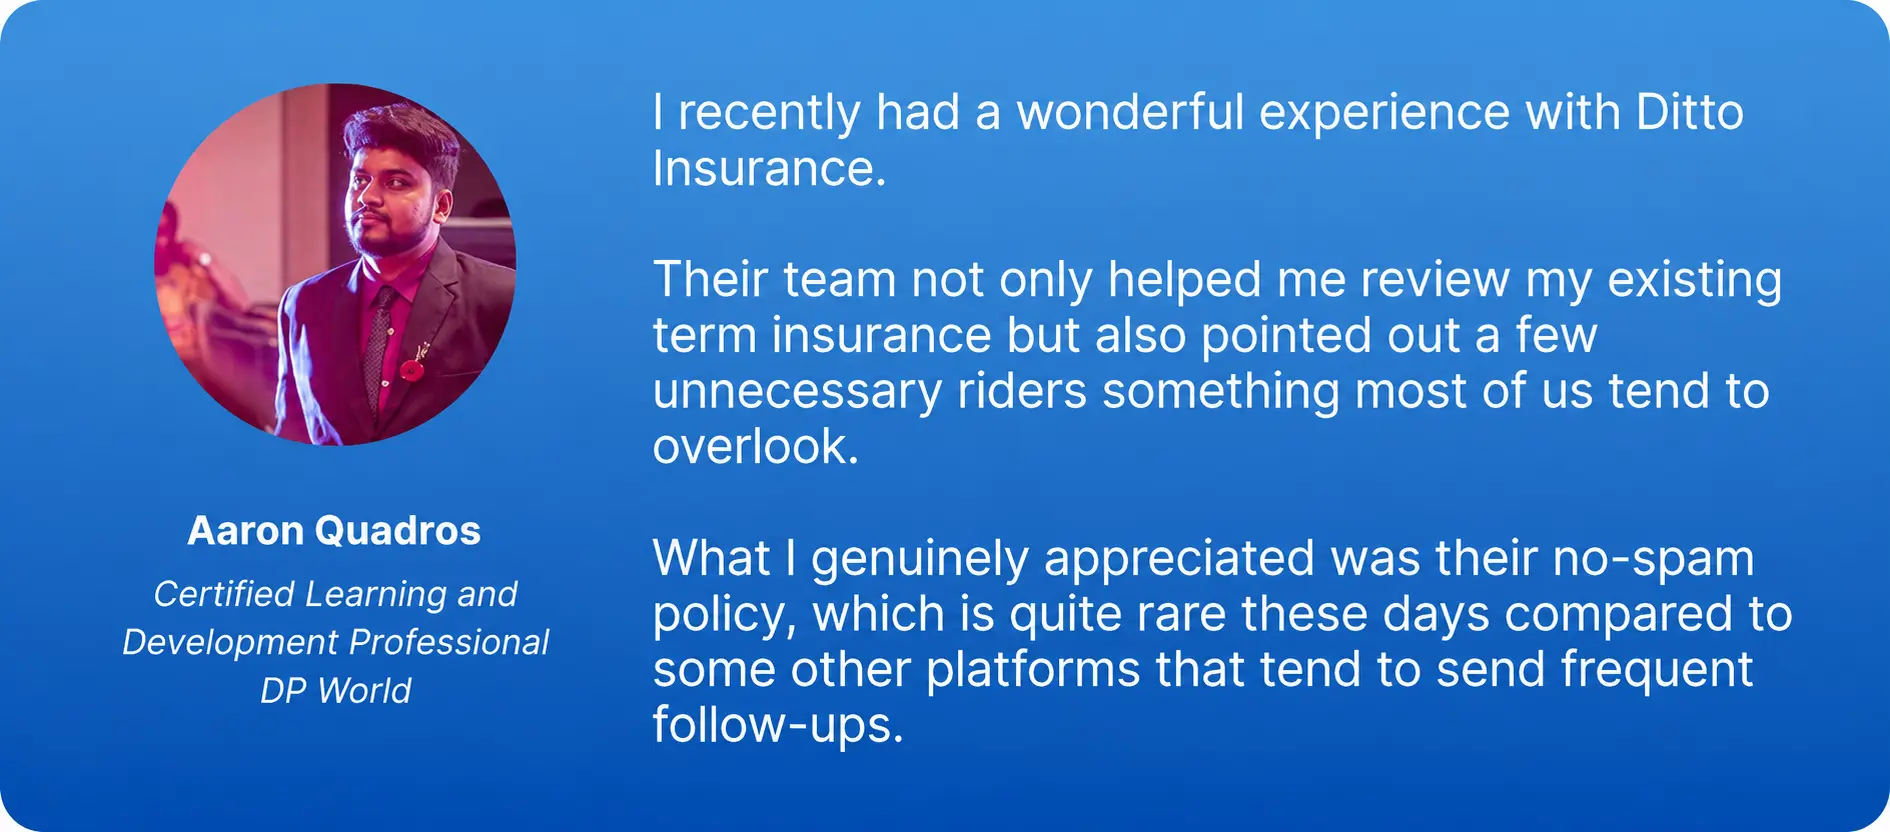
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Canara HSBC Life iSelect Smart360 is a feature-rich and highly customizable term plan, with useful options for spouse joint life protection, disability, and child care. However, it lacks instant claim payout, health management benefits, and critical illness cover options.
From an insurer perspective, Canara HSBC Life remains a mid-sized player and falls below our ₹5,000 crore business-volume benchmark. We recommend comparing the best term insurance plans from larger insurers for stronger scale and a more established overall footprint.
Frequently Asked Questions
Last updated on: