

Overview
With rising inflation, your family's future expenses can increase significantly over time. Adequate life cover helps protect your loved ones from financial uncertainty and keeps important goals funded if your income stops unexpectedly.
However, choosing the right term plan can be difficult with new products entering the market. Aviva Life recently launched the Smart Return of Premium Term Plan on 17th September, combining life cover with a premium refund at maturity. But is getting your premiums back worth the higher cost?
In the next few minutes, this guide walks you through the Aviva term insurance plan, including its features, benefits, premiums, riders, and key considerations.
What Is the Aviva Smart Return of Premium Term Plan & How It Works?
Smart Return of Premium Term Plan (UIN:122N161V01) by Aviva Life is a non-linked, non-participating individual term insurance plan. The product is a pure term plan with return of premium component.
How Does the Plan Work?
Choose Your Life Cover
Select the desired sum assured and policy term based on your family's financial needs.
Pay the Premiums
Pay premiums throughout the chosen payment term to keep the policy active and maintain life cover.
Death During the Policy Term
If the life assured dies during the policy term, the nominee receives the applicable death benefit, subject to policy terms.
Survival Until Maturity
If the life assured survives the entire policy term, the insurer pays the applicable maturity benefit. The base premiums are returned on maturity, which excludes any extra premium for loading/underwriting and any rider premium.
Features
- Flexible Premium Payments: Choose from yearly, half-yearly, quarterly, or monthly premium payment modes.
- Policy Loan: Access a loan of up to 80% of the applicable surrender value, subject to eligibility and policy terms.
Eligibility Criteria
Talk to an expert
today and
find
the right
insurance for you.
Aviva Smart Return of Premium Term Plan: Payout Options and Riders
- Aviva Accidental Casualty Non-Linked Rider: The rider sum assured is payable if the life assured dies due to an accident during the rider policy term (in addition to the base sum assured). The death must occur within 180 days of the accident, subject to applicable rider terms and conditions. The rider sum assured can go up to ₹30 lakh, subject to the base cover and underwriting.
- Aviva New Critical Illness Non-Linked Rider: If opted for, the rider pays the applicable sum assured as a lump sum payout if the life assured is diagnosed with any of the 49 covered critical illnesses, subject to a 90-day waiting period and a 30-day survival period. The rider sum assured ranges from ₹1 lakh to ₹10 lakh, subject to underwriting.
Note: The death benefit is paid to the nominee or beneficiary as a lump sum. The term insurance plan with return of premium option does not offer monthly income or combination payout options, which can provide greater flexibility based on the family's financial needs.
When choosing riders, prioritize benefits that address major financial risks. At Ditto, we recommend critical illness and waiver of premium riders. Accidental death benefit may be considered based on your occupation and lifestyle, but it should not replace adequate base life cover.
Aviva Smart Return of Premium Term Plan Sample Premium by Age
Note: The indicative figures shown represent male policyholders seeking ₹50 lakh cover until age 55, based on the official premium calculator. The premiums can vary based on age, medical history, policy term, riders, and discounts.
For comparison, Aviva Signature Platinum 3D, a pure term plan, costs around ₹4,871 annually for a 25-year-old seeking ₹50 lakh cover until age 55. This creates an annual premium difference of ₹10,055 compared with the ROP plan.
If you invest this ₹10,055 annual premium difference at an assumed 6% return, it could grow to around ₹8 lakh over 30 years. This highlights why separating insurance from investments can offer greater flexibility and potentially better wealth creation.
The plan offers low life cover, which doesn't keep pace with rising inflation. Aviva Signature Platinum 3D costs around ₹7,882 annually for a 25-year-old seeking ₹1 crore cover until age 55. This provides twice the sum assured at almost half the premium of the ROP plan.
Aviva Insurance: Performance Metrics
Note: The data represents the insurer's overall performance. The data is sourced from Aviva Life public disclosures and IRDAI annual reports. You can explore the Ditto Data Lab for more interesting insurer data.
Return of Premium vs. Pure Term Insurance: Which Is Better?
Pure term insurance provides substantial life protection at a relatively affordable premium. At Ditto, we do not recommend return of premium plans because they can cost 60% to 100% more than standard term insurance. The money returned has no capital appreciation.
Instead, consider pure term insurance and invest the premium difference separately. This keeps your insurance focused on protection while letting your investments grow independently, rather than committing extra money to an ROP structure.
A better alternative to return of premium plans can be term insurance with advanced features such as a Special Exit (zero cost) option. Plans like Axis Max Life Smart Term Plan Plus and HDFC Life Click 2 Protect Supreme Plus offer such features, giving policyholders greater flexibility to get their money back without paying higher ROP premiums.
Why Choose Ditto for Term Insurance?
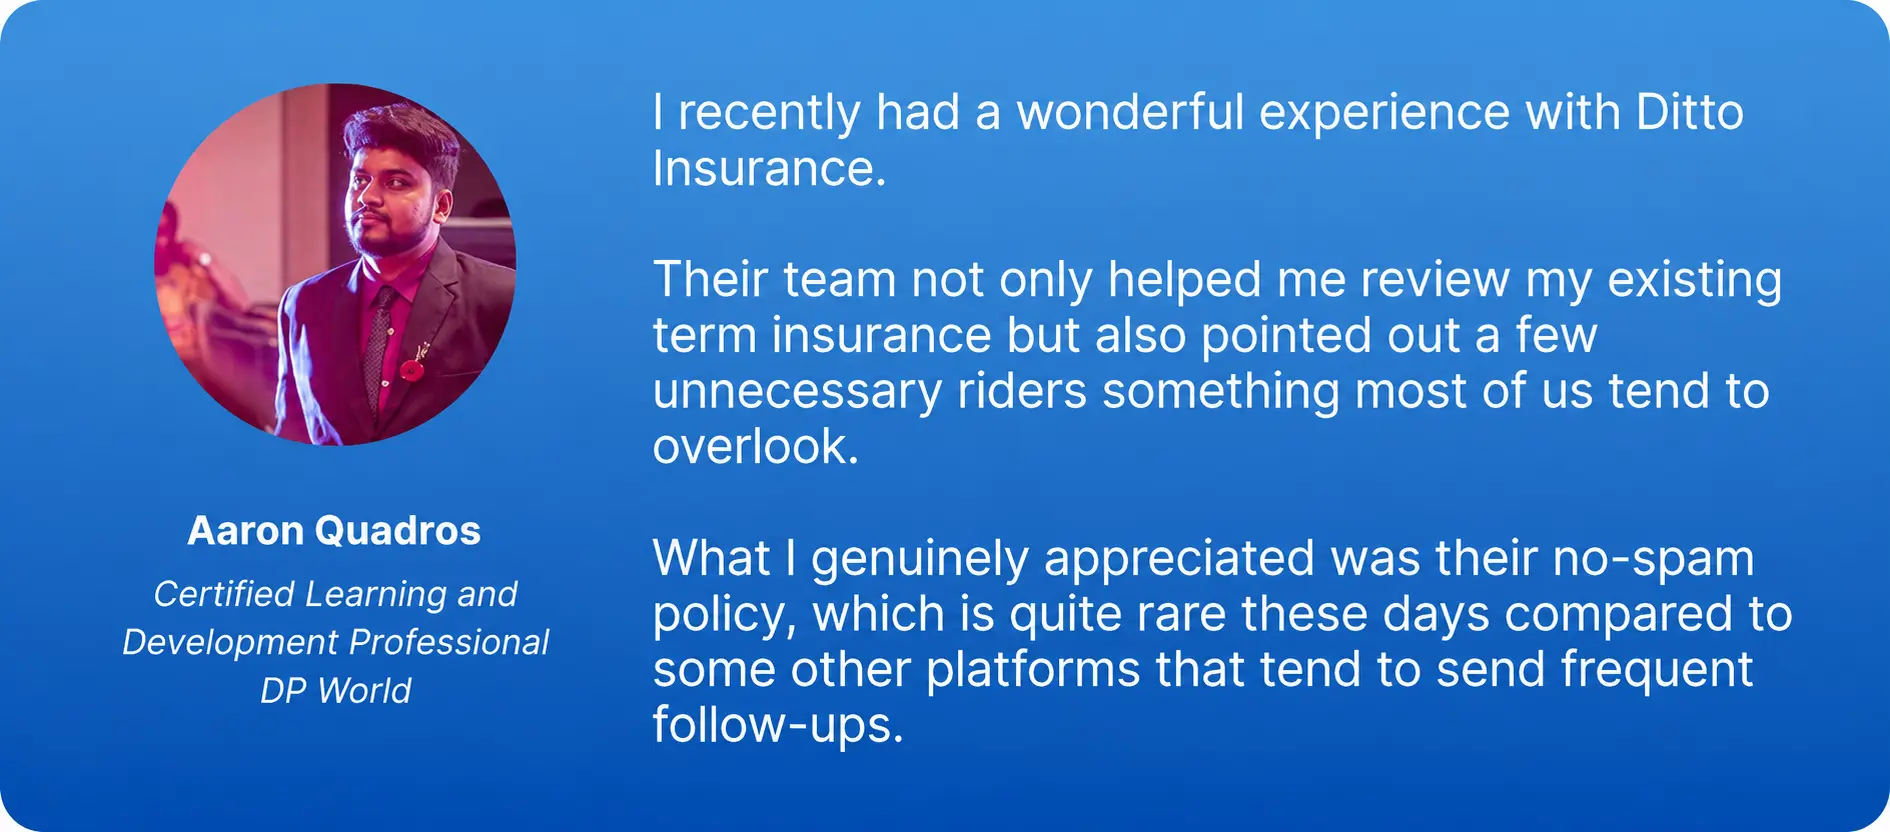
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
From a product perspective, Aviva Smart Return of Premium offers basic protection with a maximum sum assured of ₹50 lakh and lacks modern features, such as premium breaks, wellness benefits, instant partial claim payouts, and zero-cost options.
From an insurer perspective, its scale and customer-service metrics need closer comparison with larger and more established players. If you want broader features and stronger insurer credentials, explore the best term insurance plans.
Frequently Asked Questions
Last updated on: