

Overview
If you are looking for the PNB MetLife Income Protection Plan today, you may come across conflicting information about whether it is still available. That can be confusing, especially if you are considering buying the plan or already hold an existing policy. So, it is important to understand the plan’s current status first.
This guide walks you through a PNB MetLife Income Protection Plan review, covering its benefits, maturity payout, surrender options, and suitability for existing policyholders.
What Is the PNB MetLife Income Protection Plan?
The Income Protection Plan (UIN: 117N103V02) by PNB MetLife was an individual, non-linked, non-participating savings life insurance plan that combined life insurance protection with savings and maturity benefits. The plan now features in the insurer’s withdrawn plans list.
Note: This article covers PNB MetLife Income Protection Plan (UIN: 117N103V02), not the separate Income Protection Scheme (UIN: 117N101V01).
Should You Continue, Make It Paid-Up, Surrender It, or Revive a PNB MetLife Income Protection Plan You Own?
The right choice depends on how long you have held the policy, the benefits you would retain, and whether you still need the life cover.
- Continue: If you still need the cover and can afford the remaining premiums, continuing may help you retain the policy benefits until maturity.
- Make It Paid-Up: After paying premiums for at least two consecutive policy years, you can stop future premiums and retain reduced death and maturity benefits.
- Surrender: Once the policy has acquired surrender value, you can exit and receive the applicable guaranteed or special surrender value. You can ask PNB MetLife for the exact surrender quote.
- Revive: If the policy has lapsed or become paid-up, you may be able to revive it within five years from the first unpaid premium, subject to applicable conditions.
Ditto's Take: Do not continue simply because you have already paid premiums. Compare the future premiums with the surrender value, paid-up benefits, and life cover you would retain. If your existing cover is inadequate, consider separate pure term insurance before exiting.
Talk to an expert
today and
find
the right
insurance for you.
How Does the PNB MetLife Income Protection Plan Work?
Choose Your Options
Applicants had to select a Return of Premium (ROP) option of 100%, 110%, 130%, or 150% on survival. They could also choose a lump sum or monthly income death payout and select their preferred premium payment mode.
Death Benefit
If the life assured dies during the policy term, the nominee receives the applicable benefit as either a lump sum or monthly income for 10 years, based on the option selected at inception.
Maturity Benefit
If the life assured survives until maturity, 100%, 110%, 130%, or 150% of total premiums paid is payable, based on the selected RoP option and policy terms.
Step-Up Cover
The basic sum assured started at 10 times the annualized premium in the first policy year. From the second year, it increased based on the selected plan option, premium payment term, policy term, and entry age.
PNB MetLife Income Protection: Eligibility
Eligibility Criteria
Features & Riders Under PNB MetLife Income Protection Plan
- Flexible Premium Payments: Applicants had the option to choose yearly, half-yearly, or monthly premium payment modes based on their preference.
- Maximum Basic Sum Assured: The plan offered a maximum basic sum assured of ₹10 lakh. While this may provide some financial support, it may not be sufficient for individuals looking to secure their family’s long-term financial needs. Base the required life cover on factors such as annual income, existing liabilities, dependents, and future goals. Many buyers typically consider crore-level term insurance covers to create adequate financial protection.
- Death Payout Options: The plan offered a choice between a lump sum payout or monthly income for the nominee.
- High Premium Benefit: Based on the premium amount you pay, you could receive an additional sum assured multiplier from the second policy year onward, subject to the applicable terms.
- Maturity Benefit: If the life assured survives until the maturity date and all due premiums have been paid, the applicable sum assured on maturity is paid. The policy terminates once the maturity benefit is paid. The money returned excludes any underwriting costs.
Note: The PNB MetLife Income Protection Plan did not offer any riders. When evaluating riders in term insurance, consider options such as Waiver of Premium (WOP) and Critical Illness (CI), which can provide additional financial protection in specific situations.
PNB MetLife: Performance Metrics
Note: The table figures represent the insurer's performance across products. The data is sourced from PNB MetLife public disclosures and IRDAI annual reports. You can explore the Ditto Data Lab for more insurer performance data.
PNB MetLife Income Protection vs. Personal Term Insurance
Why Choose Ditto for Life Insurance?
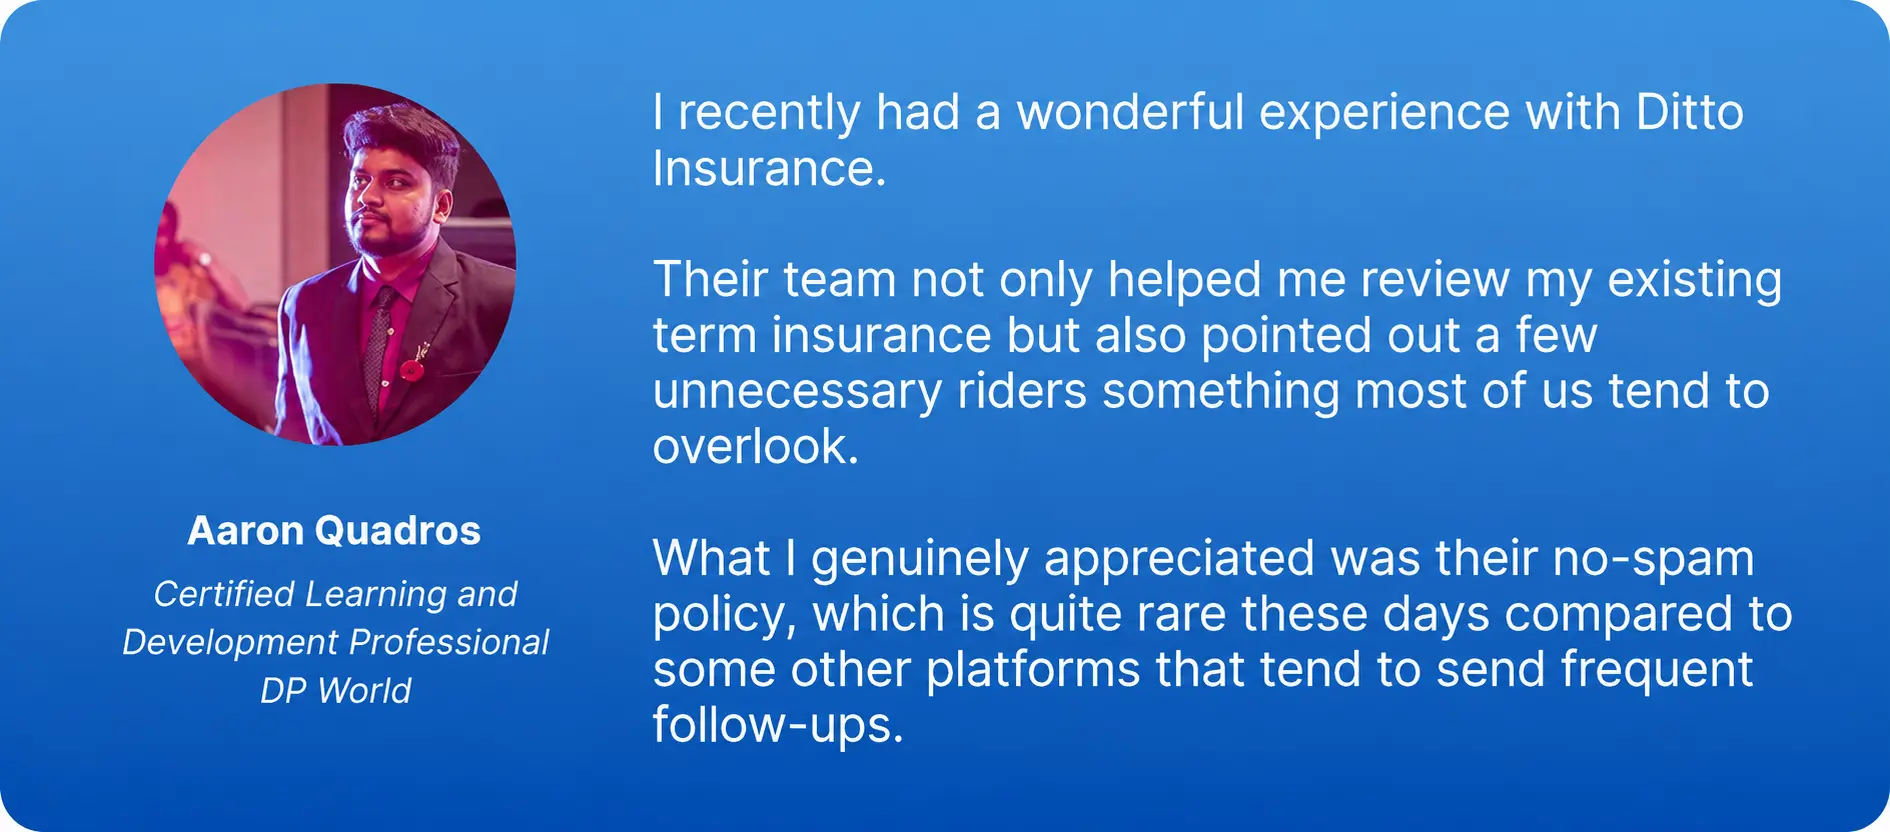
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
The PNB MetLife Income Protection Plan is currently not available for fresh purchase, but existing policyholders can continue their policies. For someone exploring PNB MetLife term insurance, plans like PNB MetLife DigiProtect and Mera Term Plan Plus offer dedicated life protection.
Despite its name, PNB MetLife Income Protection Plan was not an income-replacement policy for illness, disability, or unemployment. It was a savings life insurance plan. The “income” feature referred to the option for nominees to receive the death benefit as monthly payments over 10 years after the life assured’s death.
If you are interested in term plans from established insurers, we recommend the best term insurance plans.
Frequently Asked Questions
Last updated on: