Health Insurance

Niva Bupa Heartbeat Plan Review: Features & Premiums

Ann Tresa Jais

Written by Ann Tresa Jais

Insurance Writer

Gaurav Bhat

Reviewed by Gaurav Bhat

IRDAI-Certified Expert at Ditto

SP0738578124

Certified
Niva Bupa Heartbeat Plan Review: Features & Premiums

Overview

The Niva Bupa HeartBeat health insurance plan is available as an individual plan, a family floater, or Family First coverage. Family First combines individual and shared coverage.

Key Features and Coverages

  • Sum Insured Range: Gold offers ₹5 lakh to ₹50 lakh, while Platinum offers ₹15 lakh to ₹1 crore for standard policies.
  • In-Patient and Day-Care: Covers eligible hospitalization, day-care, and modern treatments, subject to limits.
  • Pre- and Post-Hospitalization: Covers expenses for 60 days before and 90 days after hospitalization.
  • Maternity and Newborn Cover: Includes maternity expenses, newborn coverage, and vaccinations, subject to limits.
  • Refill Benefit: Restores up to 100% of base sum insured once annually for subsequent claims, excluding Family First.
  • Loyalty Additions: Increases base coverage by 10% annually, subject to variant-specific caps.
  • Optional Add-Ons: Include hospital cash, personal accident, critical illness, and e-consultations.

What if your health insurance gave every family member their own coverage, along with an additional shared cover?

That's what Niva Bupa HeartBeat plan's Family First option does. Unlike a regular family floater, where everyone shares one sum insured, Family First gives each member an individual cover along with a shared family cover. 

You can even include extended family members like parents, siblings, and in-laws. However, these benefits have restrictions.

In this review, we'll examine HeartBeat's eligibility, features, premiums, insurer performance, and pros and cons to help you decide whether it's worth considering.

Eligibility Criteria for Niva Bupa HeartBeat Plan

Niva Bupa HeartBeat is a health insurance plan from Niva Bupa Health Insurance, available as an individual policy, a family floater, or through the Family First option.

Family first covers extended family members, including parents, siblings, and in-laws. Each member gets an individual base sum insured and access to an additional shared family cover.

For example, if four members each have ₹2 lakh individual coverage and a ₹5 lakh shared floater, a member who exhausts their individual cover can use the shared ₹5 lakh for eligible expenses. Others retain their individual coverage.

Here are the plan's eligibility criteria:

CriteriaDetails
Plan TypeIndividual, family floater, and family first 
Adult Entry Age18 to 65 years 
Child Entry Age91 days to 21 years (family floater) 
Family Floater StructureUp to 2 adults and 4 dependent children 
Family First EligibilityExtended family members across 19 eligible relationships 
Policy Tenure1 or 2 years 
RenewabilityLifetime

Niva Bupa HeartBeat Variants: Key Features and Riders Compared

Niva Bupa HeartBeat comes in three variants, Silver, Gold, and Platinum, with different coverage limits and benefits. 

Note: Silver is available only for renewals under individual and family floater policies.

Key Features of Niva Bupa HeartBeat
Background Image

01

Inpatient Hospitalization

Covers eligible hospitalization expenses up to the available sum insured.

02

Pre- and Post-Hospitalization

Covers medical expenses for 60 days before and 90 days after hospitalization.

03

Domiciliary, AYUSH, Modern Treatments, and Day-Care Treatments

Covers eligible treatments, subject to applicable sum insured limits, sublimits, and policy conditions.

04

Emergency Ambulance Cover

Covers eligible transportation expenses up to the sum insured for network hospitals and ₹2,000 per event for non-network hospitals.

05

Newborn Baby Coverage and Vaccinations

Covers eligible newborns until the end of the policy year and specified vaccinations until they turn one, subject to maternity benefit conditions.

06

Disease-Wise Sub-Limits

The plan has specific coverage limits for certain conditions across all variants. HIV/AIDS treatment is subject to a ₹50,000 limit, while certain mental health conditions have a ₹50,000 sub-limit.

07

Refill Benefit

Restores up to 100% of the base sum insured once per policy year for subsequent eligible claims, including the same or different illnesses. The refill cannot increase the payout for the claim that triggers it and is unavailable under Family First.

08

Loyalty Additions

Increases the base sum insured by 10% after each completed policy year, irrespective of claims made. The maximum increase is 50% under Silver and 100% under Gold and Platinum. Under Family First, the bonus applies separately to each member's individual base sum insured, excluding the shared family cover.

Niva Bupa HeartBeat Gold vs. Platinum vs. Silver

FeatureGold (Individual / Family Floater / Family First)Platinum (Individual / Family Floater / Family First)Silver (Only Family First)
Sum Insured (SI) Options ₹5 lakh to ₹50 lakh ₹15 lakh to₹1 crore ₹2 lakh, ₹3 lakh (renewal only) 
Room Rent Covered up to SI for any rooms except suites or higherAny room up to SI₹3,000 per day or shared room 
Waiting Periods30-day initial waiting period (except for covered accidents), 24 months for pre-existing diseases, and 24 months for specified diseases if entry age is above 45 years. 30-day initial waiting period (except for covered accidents), 24 months for pre-existing diseases, and 24 months for specified diseases if entry age is above 45 years. 30-day initial waiting period (except for covered accidents), 36 months for pre-existing diseases, and 24 months for specified diseases if entry age is above 45 years.
Geographical Co-Payment 20% co-payment applies to treatment in specified cities if Zone 2 is selectedNo geographical co-payment20% co-payment applies to treatment in specified cities if Zone 2 is selected 
Maternity CoverageFamily Floater: ₹40,000 to ₹1 lakh. Family First: Up to ₹50,000 Family Floater: ₹1.2 lakh to ₹2 lakh. Family First: Up to ₹1 lakh Family First: Up to ₹35,000 
Annual Health Check-Up Annually, up to ₹2,500 per person, depending on SI Annually, up to ₹5,000 per person, depending on SI Specified tests once every 2 years, subject to SI-based limits 
Outpatient Department (OPD) Treatment and Diagnostics Not available Covers ₹15,000 to ₹50,000 under Individual/Family Floater and up to ₹35,000 under Family First, depending on the SI. Not available

Note: Maternity coverage limits depend on the selected SI and policy variant. A 24-month waiting period and other policy conditions apply. Additionally, a 20% geographical co-payment applies under Gold and Silver for treatment in Mumbai (including Navi Mumbai and Thane), Delhi NCR, Kolkata, and Gujarat when Zone 2 pricing is selected. 

Optional Riders in Niva Bupa HeartBeat

    • Hospital Cash: Pays ₹1,500 per day under Silver, ₹3,000 under Gold, and ₹6,000 under Platinum for eligible hospitalizations lasting at least 48 hours, subject to a maximum of 30 days per policy year.
    • Personal Accident Cover: Pays a lump sum for accidental death or specified permanent disabilities, with coverage up to five times the base sum insured, capped at ₹1 crore.
    • Critical Illness Cover: Pays a lump sum upon diagnosis of a covered critical illness, subject to policy conditions and applicable coverage limits.
    • Optional Co-Payment: Allows policyholders to choose a 10% or 20% co-payment in exchange for a premium discount. The selected percentage must be paid by the policyholder on applicable claims.

Note: This is not an exhaustive list of optional benefits. For other riders, eligibility, coverage limits, and conditions, refer to the official Niva Bupa HeartBeat plan brochure.

Talk to an expert
today and find
the right
insurance for you.
Ditto Advisor

Sample Premiums by Age

Niva Bupa HeartBeat premiums vary depending on the coverage selected. To give you an idea of the costs, here's a breakdown based on the official Niva Bupa HeartBeat premium rate chart.

ProfilesGoldPlatinum
(Individual Plan): Age 25₹29,615₹44,953
(Family Floater, 2A): Ages (31, 32)₹54,019₹65,769
(Family Floater, 2A 1C): Ages (35, 34, 5)₹67,400₹88,184
(Family Floater, 2A): Ages (62, 63)₹1,78,956₹2,13,493

Note: Here, A stands for adult and C for child. These are indicative annual premiums for a Delhi resident (PIN code 110010), with ₹15 lakh sum insured under zone 1. The figures exclude optional add-ons, discounts, and applicable taxes. Actual premiums may vary based on age, medical history, location, underwriting, and selected benefits. 

Niva Bupa: Performance Metrics

Metrics (Average FY 2024-26)Niva BupaIndustry Average
Claim Settlement Ratio (CSR) 92.92%92.02% 
Incurred Claims Ratio (ICR) (Average FY 2023–25) 58.10%81.88% 
Complaints Received per 10,000 Claims 37.1329.35
Annual Business - Total Health (In Crore) ₹6,985.24₹4,504.48
Network Hospitals 10,000+10,000+ (Benchmark)

Source: This information comes from IRDAI annual reports and Niva Bupa public disclosures. These metrics reflect Niva Bupa’s overall business performance and are not specific to this plan. For more data on other insurers, explore Ditto Data Lab.

Pros and Cons of Niva Bupa HeartBeat

Pros of Niva Bupa HeartBeat

    • Convenient Extended Family Coverage: Family First makes it easier to insure multiple generations under one policy. Individual covers ensure that one member's claims don't exhaust another member's base coverage.
    • Inbuilt Maternity and Newborn Benefits: Maternity coverage and newborn benefits are included without requiring additional riders. 
    • OPD and International Coverage: Platinum includes OPD benefits and specified international hospitalization coverage without additional riders, making it useful for those who need these benefits.

Cons of Niva Bupa HeartBeat

    • Limited Refill Benefit: The sum insured is restored only once per policy year for subsequent eligible claims. Family First doesn't offer this benefit, increasing the risk of exhausting coverage after multiple hospitalizations.
    • Room Rent and Disease-Wise Restrictions: Gold excludes suites and higher room categories, while Silver Family First restricts room eligibility to a shared room or ₹3,000 per day. Certain treatments also have sublimits, which could increase out-of-pocket expenses.
    • Relatively Expensive Premiums: Premiums can be high, particularly for older applicants and those choosing Platinum. 
    • Higher Complaint Volume: Niva Bupa recorded an average of 37.13 complaints per 10,000 claims during FY 2023–24 to FY 2025–26, above the cross-insurer average of 29.35.

Why Choose Ditto for Health Insurance?

At Ditto, we’ve assisted over 12,00,000 customers choose the right insurance policy. Why customers like Pallavi love us:
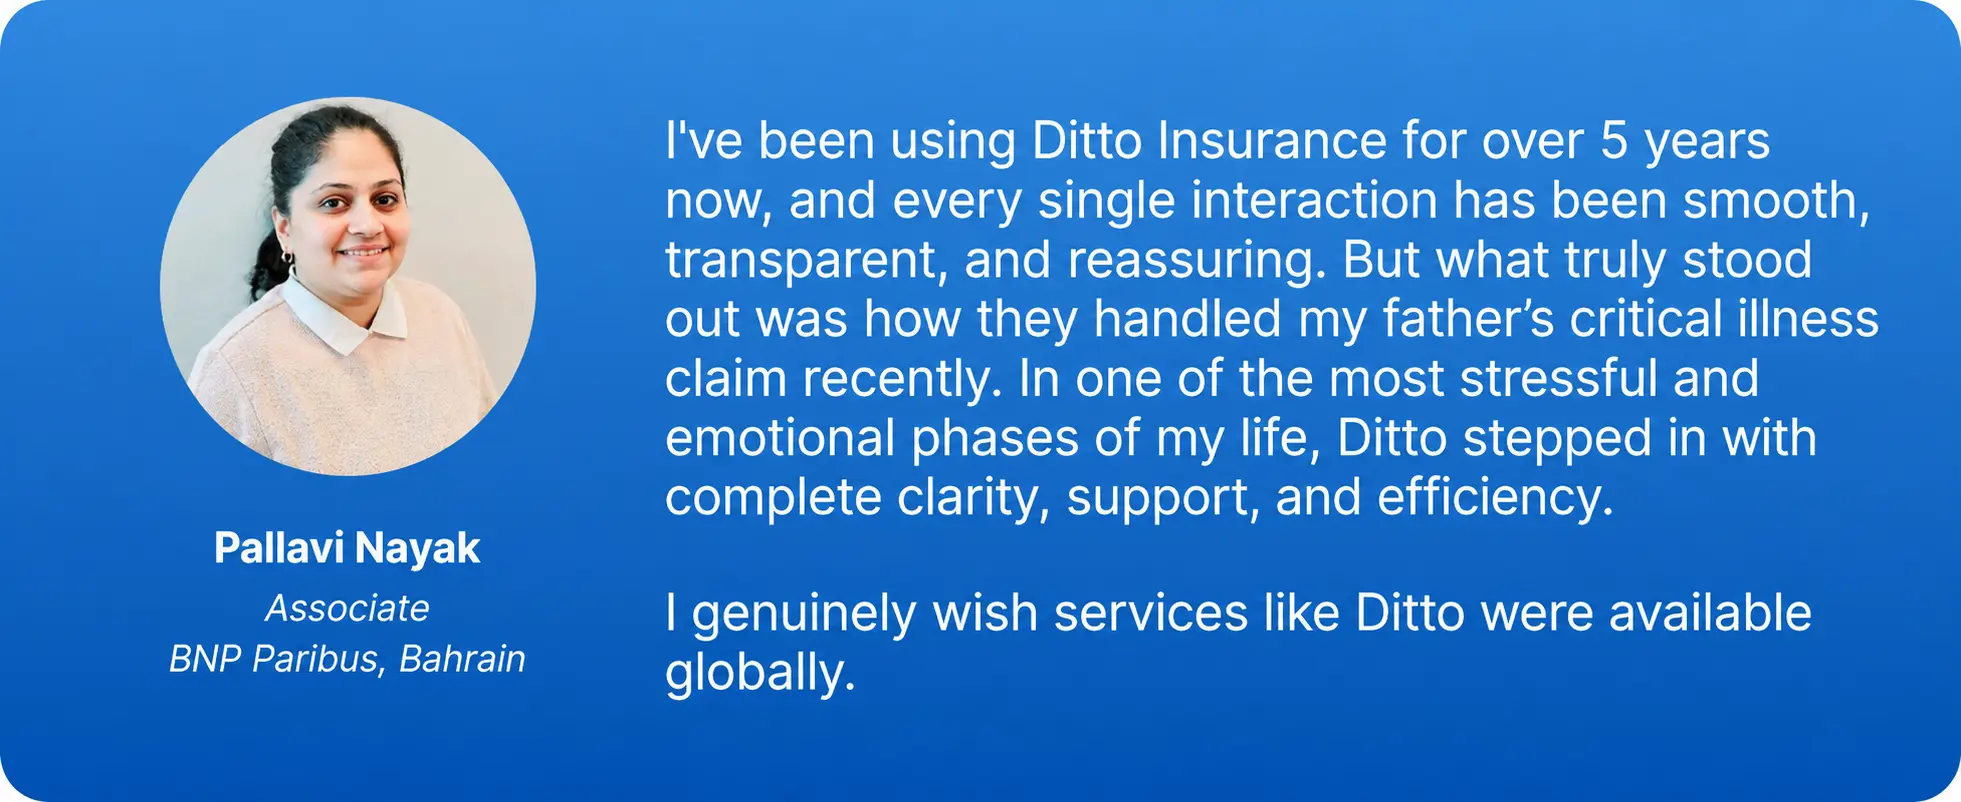
Pallavi Nayak LinkedIn Customer Testimonial
    • 100% Free Consultation
    • No Spam. No Sales Pressure.
    • Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
    • Backed by Zerodha
    • Dedicated Claim Support Team
    • Compare Plans and Premiums with a Trusted Insurance Advisor

Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!

Conclusion

Niva Bupa HeartBeat offers useful benefits, especially its Family First option, which lets extended family members have individual coverage along with a shared floater. Inbuilt maternity benefits and Platinum's OPD and international coverage also add to its appeal.

However, the limited refill benefit, room rent restrictions, and relatively high premiums make it less attractive for a fresh purchase.

If you're buying a new health insurance policy, we'd recommend considering Niva Bupa's newer plans, such as ReAssure 3.0, Aspire, and ReAssure 2.0. These are worth comparing for their coverage features, restoration benefits, and overall value. You can also explore our guide to the best health insurance plans in India to compare options from other insurers.

Frequently Asked Questions

Can Niva Bupa HeartBeat reject a claim for a pre-existing disease disclosed at policy inception?

Yes, Niva Bupa HeartBeat can reject a claim for a disclosed pre-existing disease if the applicable waiting period hasn't been completed. Gold and Platinum have a 24-month waiting period, while Silver has 36 months. Once the waiting period ends, the policy covers eligible treatment expenses according to its terms. Disclosing your condition during purchase is essential, but disclosure alone doesn't guarantee immediate coverage or payment of every claim.

Does Niva Bupa HeartBeat Gold cover maternity and what is the waiting period?

Yes, Niva Bupa HeartBeat Gold covers maternity after a 24-month waiting period under eligible family floater and Family First policies. For Family Floater coverage, both spouses must be insured. Individual policies don't include maternity coverage. The benefit ranges from ₹40,000 to ₹1 lakh for Family Floaters, depending on the sum insured, and goes up to ₹50,000 under Family First. It covers up to two eligible pregnancies or terminations, subject to policy conditions.

What should I do if Niva Bupa HeartBeat rejects my health insurance claim?

First, contact Niva Bupa customer care for a written explanation citing the policy clause behind the rejection. Check it against your medical records and waiting-period conditions. If the rejection seems incorrect, file a complaint with the insurer's grievance redressal officer and attach supporting documents. If you're dissatisfied or the complaint remains unresolved within the prescribed period, escalate it through IRDAI's Bima Bharosa or the Insurance Ombudsman.

Can I cover extended family members under Niva Bupa HeartBeat Family First?

Yes, Family First allows you to include eligible extended family members, such as parents, siblings, and in-laws, under one health insurance policy. The plan recognizes 19 relationship categories. Each insured member receives an individual base sum insured, along with access to an additional shared floater cover. Once someone exhausts their individual coverage, they can use the remaining shared cover for eligible claims. Other members retain their own individual base coverage.

Does Niva Bupa HeartBeat restore the sum insured after I use it up in a year?

Yes, HeartBeat has a refill benefit that restores up to 100% of the base sum insured once per policy year. The restored amount is available for subsequent eligible claims involving the same or different illnesses. However, it cannot increase the payout for the claim that triggers the refill. The benefit is also unavailable under Family First. 

Can I port my existing health insurance policy to Niva Bupa HeartBeat without losing my waiting-period benefits?

Yes, IRDAI's portability rules let you transfer accumulated waiting-period credits for pre-existing diseases, specified treatments, and the moratorium period, subject to coverage limits. However, acceptance into HeartBeat isn't guaranteed, as Niva Bupa can assess your application through medical underwriting. Apply before your current policy expires and maintain continuous coverage to preserve your accumulated credits.

What is the renewal age limit for the Niva Bupa HeartBeat plan?

Niva Bupa HeartBeat provides lifetime renewability, so there is no maximum age at which you must stop renewing your policy. Although the reviewed product documents specify an adult entry age of 18 to 65 years, this doesn't mean coverage ends at 65. Renewals remain subject to policy terms, timely premium payment, and applicable regulations. The insurer cannot refuse renewal simply because you've grown older or made claims.

How does the loyalty bonus work in Niva Bupa HeartBeat if I do not claim?

HeartBeat increases your base sum insured by 10% after each completed policy year, even if you've made a claim. The maximum addition is 100% under Gold and Platinum and 50% under Silver. Under Family First, the increase applies to each member's individual base cover, rather than the shared floater. Since the bonus doesn't depend on remaining claim-free, you don't have to avoid eligible claims to accumulate additional coverage.

Last updated on: