

Health Policy
Medical costs have surged, and serious illnesses like diabetes and heart disease are becoming more common due to changing lifestyles. Without proper health insurance, families risk financial strain, even one hospital visit can be extremely expensive.
You buy a health insurance policy with ₹10 lakh coverage at an affordable premium. A few years later, you're hospitalized, only to discover that your policy has a room rent limit, a 20% co-payment, or other restrictions that leave you paying a large part of the bill yourself.
That's probably the last thing you'd want from your health insurance, right?
The problem is that health insurance plans can look quite similar when you're comparing premiums and coverage amounts. But the actual benefits, restrictions, and claim conditions can vary considerably.
So, how do you choose health insurance that protects you when you need it most?
In this guide, we'll explain what to look for when choosing a health insurance policy, how to evaluate insurers, compare coverage and premiums, and avoid common mistakes before buying a plan.
Best Health Insurance Plans
When browsing health insurance plans, you’re bound to feel confused about what policy to choose due to the many options available in the market. Fortunately, by focusing on plans that offer comprehensive coverage, affordability, and valuable benefits, you can make a more informed decision. Here’s a look at the best health insurance plans:
Individual Health Insurance Plans
An individual health insurance plan covers one person and allows coverage tailored to their medical needs. However, buying separate policies for family members can increase overall premiums.
Family Floater Plans
A family floater plan covers multiple family members under one shared sum insured. It's affordable and easier to manage, but multiple claims in the same year can exhaust the available coverage.
Senior Citizen Health Insurance
Designed for individuals aged 60 and above, these plans cover hospitalization, surgeries, accidents, domiciliary care, and AYUSH treatments, subject to policy terms. However, premiums are typically higher, and insurers can require medical tests or stricter underwriting.
Top-Up and Super Top-Up Plans
Both plans increase coverage beyond a specified deductible, but they work differently.
- Top-Up Plans: Cover eligible expenses when a single hospital bill exceeds the deductible. For example, with a ₹5 lakh deductible, a ₹6 lakh bill triggers ₹1 lakh in coverage, while a ₹4.5 lakh bill doesn't qualify.
- Super Top-Up Plans: Consider cumulative eligible medical expenses during the policy year. With a ₹5 lakh deductible, two bills of ₹3 lakh and ₹4 lakh can trigger ₹2 lakh in coverage.
Super top-up plans are particularly useful for people with recurring medical expenses or multiple hospitalizations.
How to Choose Health Insurance
Claim Settlement Ratio (CSR)
The CSR indicates the percentage of claims an insurer successfully settles compared to the total number of claims filed. A higher CSR shows that the insurer is dependable and more likely to honor your claims quickly and efficiently. A higher CSR (ideally above 95%) means more claims are successfully paid.
Incurred Claim Ratio (ICR)
The ICR represents the ratio of the amount of claims paid by the insurer to the total premiums earned in a year. It reflects how much of the premium the company uses to settle claims. A balanced ICR (typically between 50-80%) suggests the insurer is managing claims well, neither underpaying nor facing financial strain.
Average Complaints
It is the number of complaints per 10,000 claims raised by policyholders. It reflects customer satisfaction. Fewer complaints indicate smoother customer service and claims handling.
Annual Business Income and Financial Strength
An insurer’s financial health reflects their ability to pay claims and sustain operations. Companies with strong annual business income and good financial ratings provide more security and confidence that your claims will be honored in the long run.
Network Hospitals
This indicates whether an insurer has a wide network of hospitals, preferably near you, for cashless treatment options. A larger network means easier access to quality healthcare without upfront payments during emergencies.
Factors to Consider While Choosing Health Insurance
Assessing Your Health Needs and Medical History
Evaluate your medical history and existing health conditions before choosing a plan. Look for coverage of pre-existing diseases with shorter waiting periods. Depending on your needs, consider benefits such as international treatment, outpatient department (OPD) coverage, or maternity care.
Understanding Your Family Structure
Your family size and medical needs influence the type of coverage you need. Individual plans suit single people or seniors with pre-existing conditions, while family floaters allow multiple members, including children and elderly parents, to share one sum insured. Compare coverage and affordability before deciding.
Considering Future Healthcare Needs
Consider your lifestyle and future medical expenses. If you expect frequent doctor visits, OPD coverage can be useful. Similarly, couples planning to have children should consider maternity benefits.
Key Features to Look For in a Health Insurance Policy
When choosing health insurance, prioritize features that provide adequate coverage and reduce out-of-pocket expenses.
- Sum Insured: Consider ₹10 lakh in smaller cities and ₹15 lakh to ₹25 lakh in metros. For higher coverage, explore super top-ups, bonuses, and restoration benefits.
- Daycare Coverage: Choose plans covering procedures like cataract surgery, chemotherapy, and dialysis without requiring 24-hour hospitalization.
- Pre- and Post-Hospitalization: Look for 30–60 days of pre-hospitalization and 60–180 days of post-hospitalization coverage.
- Domiciliary Hospitalization: Covers treatment at home when hospitalization isn't possible due to medical conditions or bed shortages.
- AYUSH Coverage: Covers eligible Ayurveda, Yoga and Naturopathy, Unani, Siddha, and Homeopathy treatments.
- Restoration Benefit: Prefer unlimited restoration of the sum insured, including for the same illness, without cooling-off periods.
- Bonus: A No Claim Bonus increases coverage during claim-free years, while loyalty bonuses apply on renewal regardless of claims.
- Emergency Ambulance: Look for road and air ambulance coverage without restrictive limits.
- Annual Health Checkup: Prefer free yearly checkups for all insured members without affecting the No Claim Bonus.
Add-Ons in Health Insurance to Maximize Benefits
Add-ons provide additional coverage based on your healthcare needs.
- Consumables Cover: Covers non-payable items like gloves, masks, personal protective equipment (PPE) kits, and syringes.
- Outpatient Department (OPD) Coverage: Covers consultations, dental treatments, diagnostic tests, and minor procedures without hospitalization. Useful for frequent doctor visits, but compare the additional premium against expected expenses.
- Maternity and Newborn Coverage: Covers eligible childbirth, newborn care, and vaccination expenses. Useful for couples planning a family.
Talk to an expert
today and
find
the right
insurance for you.
Sample Premiums by Age and Sum Insured
Note: Here, "A" stands for adult, and "C" denotes children. These are indicative premiums for a Delhi resident (PIN code: 110010) with a ₹15 lakh sum insured, including mandatory and recommended add-ons. Your premium can change based on age, city, medical history, plan varant, added discounts, and chosen add-ons.
Things to Avoid When Choosing a Health Insurance Plan
- Co-Payment: Requires you to pay a percentage of an admissible claim. For example, a 20% co-payment on ₹1 lakh means paying ₹20,000 yourself. Common in senior citizen policies and certain treatments, co-payments can reduce premiums but increase claim expenses.
- Disease-Wise Sub-Limits: Restrict payouts for specific treatments. For example, a ₹5 lakh policy could limit cataract surgery to ₹50,000 or heart surgery to ₹2 lakh, leaving you to pay additional expenses.
- Room Rent Restrictions: Limit eligible room charges, such as ₹5,000 daily or 1% of the sum insured. Exceeding the limit can trigger proportionate deductions on other hospital expenses. Prefer policies without room rent limits or those allowing a single private room without a monetary cap.
What Tools Can Help You Choose the Right Health Insurance Plan?
If you are unsure how to choose health insurance, using digital tools can make the process easier, faster, and more accurate.
Insurance Premium Calculator
An insurance calculator helps you estimate how much premium you will pay based on factors like:
- Age
- Sum insured
- Family size
- Add-ons chosen
Ditto’s Health Insurance Tools
This tool helps you decode any health insurance policy in minutes. All you have to do is enter the insurer's name and the policy name, and you will instantly get:
- Complete policy wording
- Key benefits and inclusions
- Limitations, exclusions, and waiting periods
- Available add-ons and optional covers
- Ditto’s expert review on whether the policy is worth considering
Ditto’s Compare Health Policies tool lets you:
- Compare plans from different insurers or even two plans from the same insurer.
- Get a side-by-side view of key features, add-ons, coverage, premiums, exclusions, and benefits.
- Understand the pros and cons of each policy in plain language.
With expert-backed guidance, Ditto also helps you understand policy documents and choose a plan that actually works when you need it most.
Key Factors to Compare Before You Buy Health Insurance
Before buying, compare these factors to ensure adequate coverage and value for money.
- Claim Settlement Ratio (CSR): Prefer insurers with a CSR of 90% or higher, alongside a strong claims record.
- Plan Flexibility: Check options to increase coverage, add family members, or switch to a family floater.
- Online Quote Comparison: Compare premiums, exclusions, waiting periods, co-payments, sublimits, room rent restrictions, network hospitals, and add-ons.
- Insurer Track Record: Review customer feedback, complaint ratios, and grievance resolution.
- Cost vs. Value: Choose affordable coverage with sufficient benefits rather than simply selecting the cheapest policy.
Why Choose Ditto for Health Insurance?
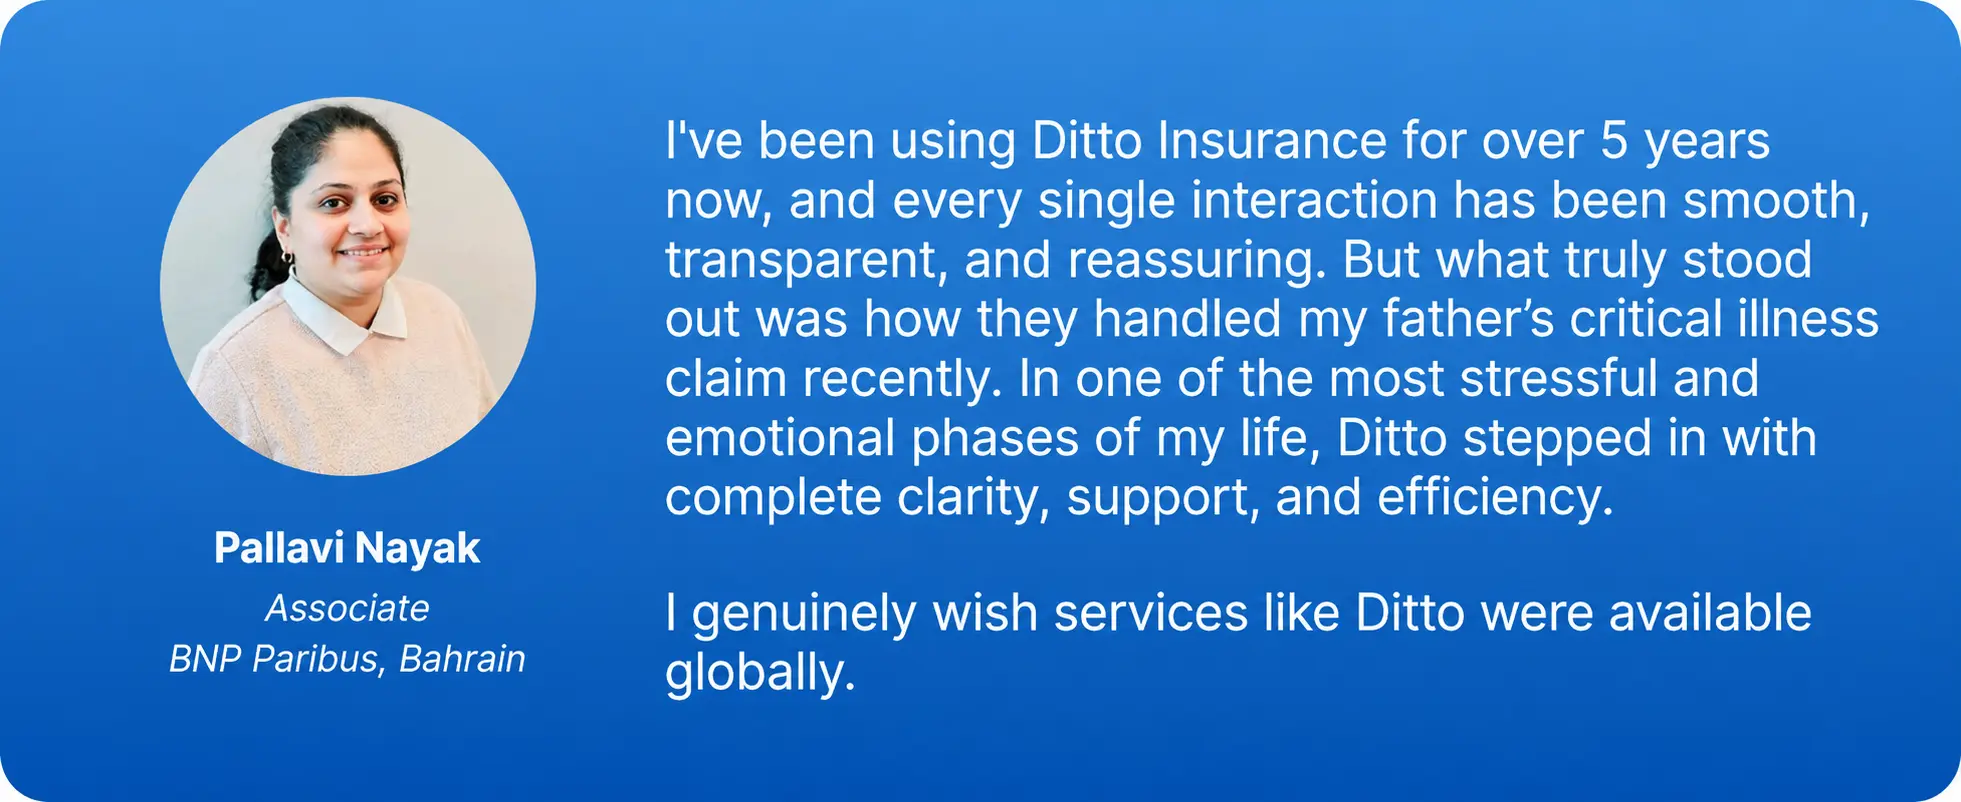
At Ditto, we’ve assisted over 12,00,000 customers choose the right insurance policy. Why customers like Pallavi love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
How to Choose Health Insurance: Ditto’s Take
Health insurance may seem like an added expense when you are young and in the prime of your health. However, the correct way to think about health insurance is to consider it as a safety net that is there to catch you during a financial fall.
How to choose health insurance involves checking the insurer's metrics, reputation, and the policy's features and exclusions while avoiding common mistakes like opting for an inadequate sum insured or ignoring the policy wording. Health insurance should offer you one thing above all: peace of mind. So, choose a policy that truly has your back.
Frequently Asked Questions
Last updated on: