Care Supreme Heart is a modified version of Care Supreme, intended for applicants with pre-existing cardiac conditions who cannot qualify for regular coverage. Often offered as a counteroffer after medical underwriting, it provides sum insured options of ₹5 lakh, ₹10 lakh, and ₹15 lakh.
Key Features & Benefits
Room Rent Limits: Eligible room expenses are covered up to the sum insured without a separate room-category restriction.
Co-Payment: A mandatory 20% co-payment applies to every admissible claim.
No Restoration Benefit: The plan does not offer a restoration benefit.
Waiting Periods for Pre-Existing Diseases (PED): A 24-month waiting period applies to PEDs.
Disease-Wise Sub-Limits: Cardiovascular diseases and other specified treatments are capped at ₹3 lakh or ₹4 lakh, depending on the sum insured.
Cumulative Bonus: Adds 50% of the base sum insured annually, up to 100%, regardless of claims.
Heart-related conditions are becoming increasingly common. According to aTimes of India report citing National Statistical Office (NSO) survey data, reported cardiovascular ailments rose nearly threefold, from 1,333 per lakh population in 2017–18 to 3,891 in 2025.
While health insurance is particularly important for people with cardiac conditions, getting comprehensive coverage can be difficult if you already have a history of heart disease.
This is where Care Supreme Heart comes in. Instead of rejecting your application for regular Care Supreme outright, Care Health may offer this modified coverage arrangement after assessing your medical history.
In this review, we'll examine the plan’s eligibility criteria, key features, premiums, restrictions, and whether it's worth considering.
Care Supreme Heart is a modified variant ofCare Health Insurance's comprehensive Care Supreme plan, designed for people with pre-existing cardiac conditions who may struggle to qualify for regular coverage.
While it retains several benefits of the original plan, it adds restrictions, including co-payments and disease-specific sub-limits. Your eligibility and final policy terms depend on the insurer's assessment of your medical history.
Here are the plan's eligibility criteria:
Criteria
Details
Plan Type
Individual and family floater
Adult Entry Age
18 years to no limit
Child Entry Age
90 days to 24 years
Sum Insured (SI)
₹5 lakh, ₹10 lakh, ₹15 lakh
Family Floater Structure
Up to 2 adults and 2 children
Individual Policy Structure
Maximum 6 insured members
Policy Tenure
1,2, or 3 years
Note
Meeting these criteria does not guarantee approval. Care Health evaluates each application individually and may request additional details and medical reports or tests before making a final decision.
Key Features and Riders of Care Supreme Heart
Key Details of Care Supreme Heart
Parameter
Details
Disease-Wise Sub-Limits
Cardiovascular diseases, cancer, and kidney treatments are capped at ₹3 lakh for SI below ₹10 lakh and ₹4 lakh for SI of ₹10 lakh to ₹15 lakh.
Room Rent
Covered up to SI
Co-Payment
20% per admissible claim
Waiting Periods
30 days initially (except accidents), 24 months for specified illnesses, and 24 months for pre-existing diseases
Pre- and Post-Hospitalization
Eligible expenses covered for 60 days before hospitalization and 180 days after discharge
Ambulance Coverage
Road ambulance: Up to ₹10,000 for coverage below ₹15 lakh and up to the sum insured for ₹15 lakh coverage. Air ambulance: Up to ₹5 lakh per year through an optional benefit.
Domiciliary, AYUSH, Modern Treatments and Day-Care Treatments
Covered up to SI
Key Features of Care Supreme Heart
01
Cumulative Bonus
Your base sum insured increases by 50% every policy year, up to an additional 100%, irrespective of claims. For example, ₹15 lakh in base coverage can grow to ₹30 lakh after two years. However, the bonus does not override treatment-specific limits.
02
No Unlimited Automatic Recharge
Unlike regular Care Supreme, this arrangement removes the unlimited automatic recharge benefit through the Special Care add-on. This means you cannot rely on repeated restoration of your sum insured after claims in the same year.
03
Unlimited E-Consultations
You can access unlimited online consultations with general physicians in Care Health's empaneled network.
04
Welcome Discount
New policyholders can receive a 7.5% discount in the first year and 5% in the second year, subject to the insurer's conditions.
Riders of Care Supreme Heart
Care Supreme Heart may be offered with additional benefits selected by the insurer. Some of these benefits carry an additional premium. Check the final counteroffer to see which benefits are included and what you will pay.
Annual Health Check-Up: Provides one health check-up every policy year through a pre-added benefit available at an additional premium.
Wellness Benefit: Offers up to a 30% discount on renewal premiums based on your physical activity. For example, recording at least 10,000 steps on 120 qualifying days earns a 10% discount, while 270 qualifying days can earn a 30% discount. This benefit is pre-added at an additional premium.
Disease Management Program (DMP): Available through the Instant Care add-on, this benefit helps manage hypertension by covering up to four consultations annually (₹750 each), pharmacy expenses up to ₹6,000 per year, and specified diagnostic tests, including 2D echocardiography.
Talk to an expert today and find the right insurance for you.
Sample Premiums by Age and Sum Insured
Profiles
₹10 Lakh SI
₹15 Lakh SI
(Individual Plan): Age 25
₹14,948
₹16,962
(Family Floater, 2A): Ages (31, 32)
₹23,205
₹27,026
(Family Floater, 2A 1C): Ages (35, 34, 5)
₹26,564
₹31,453
(Family Floater, 2A): Ages (62, 63)
₹63,253
₹75,530
Note: Here, A stands for adult and C for child. These are indicative premiums for a Delhi resident (PIN code: 110010) for ₹10 lakh and ₹15 lakh cover and include compulsory add-ons and discounts. Your premium can change based on age, city, medical history, plan variant, added discounts, and chosen add-ons.
Care Health: Performance Metrics
When evaluating Care Health insurance reviews, look beyond the plan’s features and consider the insurer's overall performance.
Coverage for Cardiac Patients: Care Supreme Heart offers modified coverage to applicants with cardiac conditions who may not qualify for comprehensive plans, subject to underwriting.
Shorter PED Waiting Period: The plan has a 24-month waiting period, compared to Care Supreme's 36 months, although sub-limits and exclusions apply.
No Loading Charges: The insurer typically accepts or rejects applications without imposing additional premiums based on medical history.
Offered by a Strong Insurer: Care Health recorded a 95.45% average claim settlement ratio (vs. 92.02% industry average), ₹8,405 crore in average annual business during FY 2024–26, and has 11,400+ cashless network hospitals across India.
Cons of Care Supreme Heart
Disease-Wise Sub-Limits: Cardiovascular diseases, cancer, kidney diseases, and long-bone fractures have ₹3 to ₹4 lakh limits. Separate limits apply to hernia, kidney stones, cataracts, and knee replacements.
Mandatory Co-Payment: Policyholders must pay 20% of every admissible claim, alongside expenses exceeding disease-wise limits.
No Unlimited Restoration: Unlike regular Care Supreme, this plan excludes unlimited automatic recharge after coverage exhaustion.
Limited Consumables and OPD Coverage: Comprehensive consumables and routine OPD expenses aren't covered, although select e-consultations and hypertension management benefits are available.
High Complaint Volume: Care Health recorded 42.67 complaints per 10,000 claims during FY 2024–26, exceeding the industry average of 29.35.
Why Choose Ditto for Health Insurance?
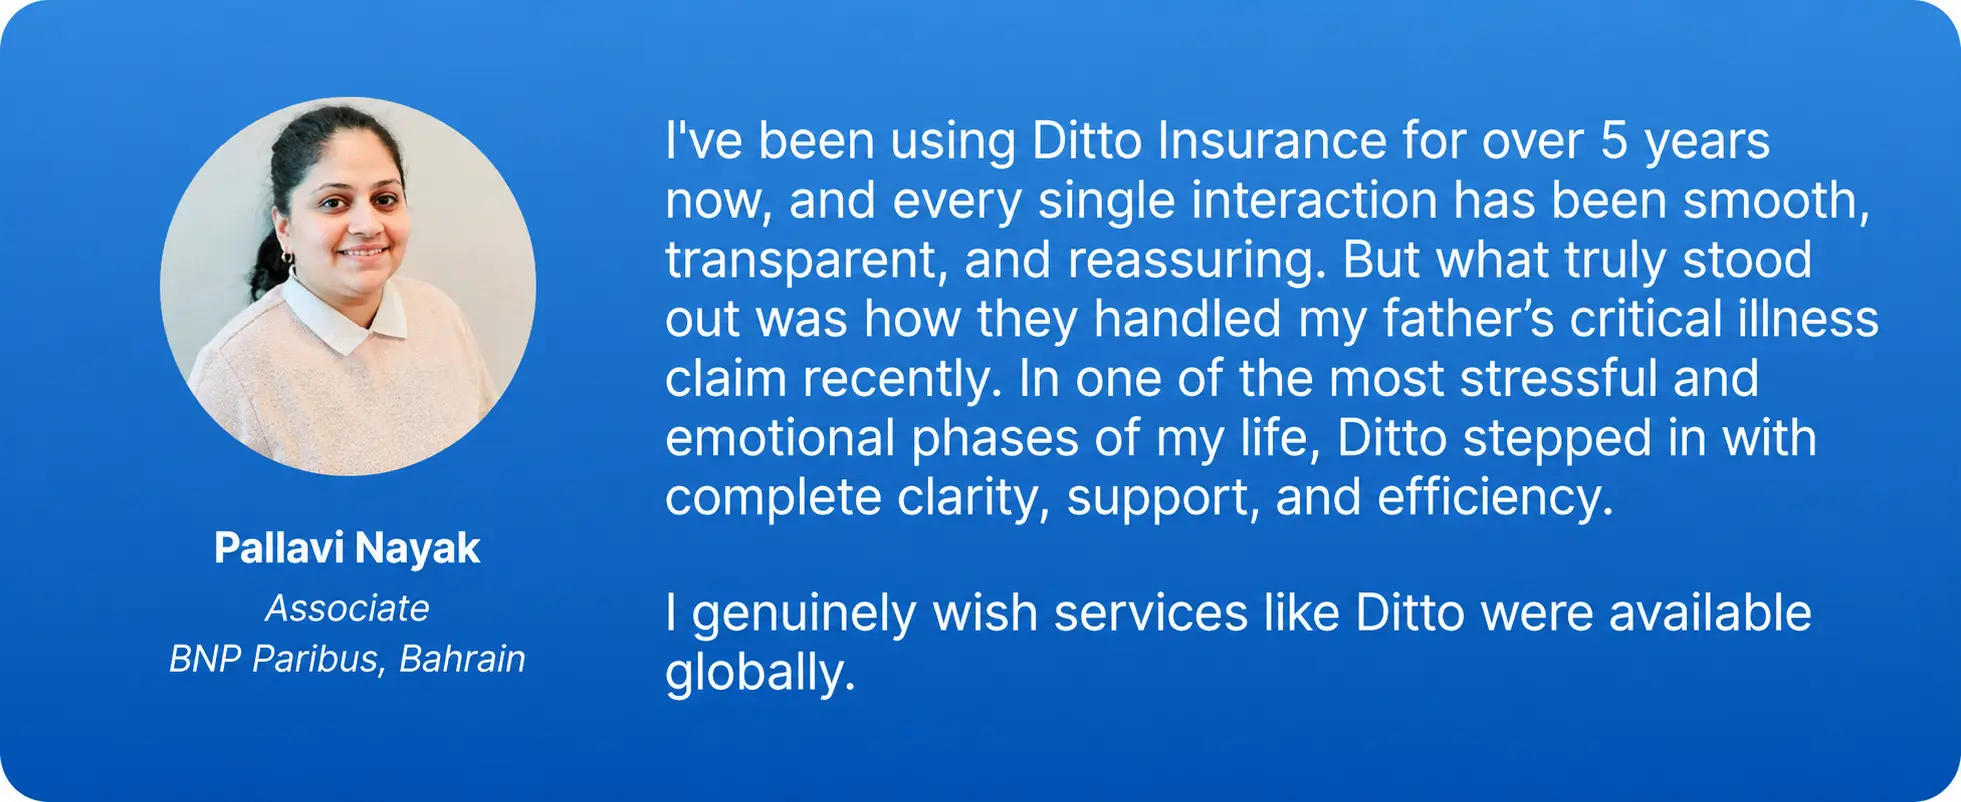
At Ditto, we’ve assisted over 12,00,000 customers choose the right insurance policy. Why customers like Pallavi love us:
100% Free Consultation
No Spam. No Sales Pressure.
Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
Backed by Zerodha
Dedicated Claim Support Team
Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Care Supreme Heart is worth considering if your cardiac history makes it difficult to qualify for regular comprehensive health insurance. As the successor to Care Heart, also designed for people with pre-existing cardiac conditions, it offers an alternative for applicants who would otherwise struggle to get covered.
While its disease-wise sub-limits, mandatory 20% co-payment, possibility of permanent exclusions, and lack of unlimited restoration are significant drawbacks, it can still provide valuable coverage when other options aren't available.
Ditto's Take: We'd recommend exploringcomprehensive health insurance plans first and considering Care Supreme Heart only if better coverage isn't available. Before accepting the counteroffer, carefully review the cardiac treatment limits, premiums, and exclusions to understand how much protection you're actually getting.
Frequently Asked Questions
Is Care Supreme Heart different from Care Supreme health insurance?
Yes. Care Supreme Heart is a modified version of Care Supreme, intended for applicants with pre-existing cardiac conditions who cannot qualify for regular coverage. Unlike regular Care Supreme, it includes a mandatory 20% co-payment, disease-wise sub-limits, and no unlimited automatic recharge. Care Supreme Heart is usually offered as a counteroffer following medical underwriting rather than as a separate, independently purchased comprehensive plan.
Can I buy Care Supreme Heart for my parents?
Yes. Care Supreme Heart allows parents to be insured and has no maximum entry age for adults. You can choose individual coverage or a family floater, subject to the plan's eligibility rules. However, approval depends on your parents' medical history, existing cardiac conditions, and overall health. Care Health assesses each application individually and can request additional medical reports before deciding whether to offer coverage and under what terms.
Does Care Supreme Heart require a medical test before policy issuance?
Care Supreme Heart requires medical underwriting, but physical medical tests aren't automatically required for every applicant. Care Health can assess existing medical records and request additional tests depending on your cardiac history, age, and overall health. These can include ECGs, echocardiograms, and other cardiac investigations. The insurer uses this information to decide whether to approve the application, impose additional restrictions like a permanent exclusion for the pre-existing condition, or decline coverage. The exact requirements depend on your medical profile.
Can Care Supreme Heart be purchased without any pre-existing disease?
Yes. You can buy Care Supreme Heart even if you don't have a pre-existing cardiac condition. However, we wouldn't recommend it for someone who qualifies for regular comprehensive health insurance. The plan comes with restrictions such as disease-wise sub-limits, a mandatory 20% co-payment, and no restoration benefit. If you have no pre-existing conditions, Care Supreme is a better option to consider because it offers more comprehensive coverage with fewer restrictions.
Does Care Supreme Heart cover heart conditions diagnosed after buying the policy?
Yes. Eligible cardiac conditions diagnosed after purchasing Care Supreme Heart are covered, subject to policy conditions. However, the plan includes a 30-day initial waiting period, applicable disease-specific waiting periods, a mandatory 20% co-payment, and cardiovascular treatment sub-limits. Care Health assesses the medical records and applicable exclusions before settling a claim.
Can I port my existing health insurance policy to Care Supreme Heart?
You can request portability from another insurer at renewal, but Care Supreme Heart must accept you under its underwriting rules. Under IRDAI regulations, eligible portability credits for waiting periods, accrued bonuses, and the moratorium period are protected to the applicable extent. However, portability does not guarantee approval of this particular plan.
Does Care Supreme Heart offer lifelong renewability?
Yes. Care Supreme Heart has no maximum exit age for adults, allowing lifelong coverage through renewals. Under IRDAI regulations, an insurer cannot refuse renewal solely because you have made claims or developed new medical conditions. However, renewal remains subject to applicable policy conditions, including timely premium payments. If the product is withdrawn, the insurer must provide suitable migration options. Lifelong renewability also does not guarantee fixed premiums or unrestricted coverage.
Can I increase my sum insured under Care Supreme Heart at renewal?
You can request an increase in your sum insured at renewal, subject to Care Health's available coverage options and underwriting approval. The plan offers ₹5 lakh, ₹10 lakh, and ₹15 lakh sum insured options. Under IRDAI regulations, the insurer can assess the additional risk associated with the increased coverage. Fresh waiting periods can apply to the enhanced portion, while continuity benefits remain protected for your existing sum insured.
Does Care Supreme Heart have a separate UIN from Care Supreme?
No. Care Supreme Heart is a modified version of Care Supreme and does not have a separate Unique Identification Number (UIN). It uses the base plan's UIN, while add-ons such as Special Care, Extra Care, and Instant Care have their own UINs. These add-ons modify certain benefits, introduce disease-specific limits, or provide additional coverage. The exact combination of add-ons and restrictions depends on the insurer's final underwriting offer.
What is the difference between Care Heart and Care Supreme Heart?
Care Heart is a separate health insurance plan designed for people with pre-existing cardiac conditions, offering coverage between ₹3 lakh and ₹10 lakh. Care Supreme Heart, its successor, is a modified version of Care Supreme and offers ₹5 lakh, ₹10 lakh, and ₹15 lakh coverage. While Care Heart has age-based co-payments and room rent restrictions, Care Supreme Heart has a flat 20% co-payment, disease-wise sub-limits, and no restoration benefit. Both plans have a 24-month waiting period for pre-existing diseases.
What is the Care Health Insurance claim settlement ratio?
The Care Health Insurance claim settlement ratio averaged 95.45% between FY 2024–26, compared to the industry average of 92.02%. This indicates a strong claim settlement record. However, the insurer also recorded 42.67 complaints per 10,000 claims, exceeding the industry average of 29.35. These figures reflect Care Health's overall performance, not Care Supreme Heart specifically. You should also consider the plan's co-payments, disease-wise sub-limits, and exclusions before purchasing it.
How can I contact Care Health Insurance customer care?
You can contact Care Health Insurance customer care at 1800-102-4488 for policy servicing and claim-related queries or reach them via WhatsApp at 8860402452. You can also email customerfirst@careinsurance.com or use the insurer's website, mobile app, or self-help portal to track claims, manage policies, and submit requests. For new policy inquiries, call 1800-102-4499. Visit the official Care Health contact page for further assistance.