Health Insurance

Aditya Birla Activ One Maternity vs. Niva Bupa Aspire Compared

Aaryaa Nagpal Jambhulkar

Written by Aaryaa Nagpal Jambhulkar

Insurance Writer

Gaurav Bhat

Reviewed by Gaurav Bhat

IRDAI-Certified Expert at Ditto

SP0738578124

Certified
Aditya Birla Activ One Maternity vs. Niva Bupa Aspire Compared

Overview

Aditya Birla Activ One Maternity and Niva Bupa Aspire are both comprehensive health plans that include maternity options, but they approach it very differently.

Key Differences:

  • Room Rent: No restrictions under either plan.
  • Maternity Cover: Aditya Birla offers it via a combination package of a base plan, super top-up, and maternity rider. Niva Bupa Aspire includes it through the built-in M-iracle benefit.
  • Restoration: Activ One NXT (base plan under Activ One Maternity) gives 2x from day 1 with unlimited refills later, while Aspire triggers ReAssure Forever after the first claim, with refills up to the base sum insured.
  • Pre-Hospitalization: 90 days (Activ One NXT) vs. 60 days (Niva Bupa Aspire).
  • Spouse Coverage: Standard in Aditya Birla, and Aspire allows future spouse inclusion with a waiting period credit option, subject to policy terms.

Aditya Birla Activ One Maternity: Better suited if you want a package plan where maternity benefit is part of the combination.

Niva Bupa Aspire: Designed as a bundled plan with wider maternity and newborn-related benefits.

Choosing a maternity health insurance plan often involves a trade-off between shorter waiting periods and wider coverage. Plans that offer faster access may come with lower maternity limits, while plans with broader maternity and newborn benefits usually require longer waiting periods.

That's exactly the choice between Aditya Birla Activ One Maternity vs. Niva Bupa Aspire. Aditya Birla's plan gets you covered in just 3 months, but caps your payout at a certain limit. The Niva Bupa Aspire plan takes longer to build up maternity cover, but covers much more, including In-Vitro Fertilization (IVF), adoption, and your newborn's medical costs from day one.

In this guide, we compare both plans on maternity limits, waiting periods, newborn coverage, and premiums, so you can decide which one fits your timeline and needs.

Aditya Birla Activ One Maternity vs. Niva Bupa Aspire: Insurer Comparison

Aditya Birla Health Insurance is a standalone health insurer under the Aditya Birla Capital group. Its products are built around modular plans, wellness-linked benefits, and combinations of base policies with super top-ups and add-ons.

Niva Bupa Health Insurance is also a standalone insurer backed by global healthcare company Bupa. Its plans focus on comprehensive coverage, restoration benefits, and life-stage features like maternity and child care.

Maternity Coverage: Aditya Birla Activ One Maternity vs. Niva Bupa Aspire

FeatureAditya Birla Activ One MaternityNiva Bupa Aspire
Plan Structure₹15 lakh base plan (Activ One NXT) + ₹85 lakh super top-up (Aditya Birla Super Health Plus) + maternity rider Comprehensive base plan offering sum insured options from ₹3 lakh to ₹1 crore
Maternity Sub-Limit₹30,000 to ₹1.5 lakh limit (normal and C-section) as per chosen optionVariant & Sum Insured (SI) dependent, ranging from ₹4,000 to ₹25,000
Maternity Waiting Period3 months9 months (Platinum+/Titanium+), 24 months (Diamond+), 48 months (Gold+)
IVF, Infertility, Legal Adoption and SurrogacyIVF is covered under the maternity benefit, while other assisted reproduction techniques are typically excludedCovered under M-iracle SI

Insight on Coverage Structure:

Aditya Birla Activ One Maternity Plan combines a base policy, a maternity rider (Health Enhance), and a super top-up. However, the maternity payout is capped at the fixed limit for both normal and C-section deliveries.

Niva Bupa Aspire offers maternity through its M-iracle benefit. For instance, on a ₹15 lakh base policy, the initial M-iracle limit is ₹15,000. However, any unused amount carries forward each year through the Booster+ feature, allowing the maternity pool to grow up to 10x over time, depending on the entry age and variant.

Newborn Baby Coverage and Pre- and Postnatal Benefits Compared

FeatureAditya Birla Activ One MaternityNiva Bupa Aspire
Newborn CareAdd-On: Choose from ₹50,000, ₹1 lakh, or ₹2 lakh coverCovered from day 1 up to the full base SI
Adding Child to PolicyMust be added separately after 90 daysMust be added separately after 90 days
Pre- & Postnatal ExpensesAdd-On: 9 months pre- and 90 days post-natal OPD cover with 2 in-person specialist visits + unlimited general practitioner teleconsultsAntenatal checkups and listed expenses like gynecologist consultation, sonogram, etc., are covered under M-iracle SI
VaccinationsMaternity-related vaccines are offered at discounted rates via the network/app under pre- and postnatal OPD add-on.Pre-natal mother vaccines are covered under M-iracle

Key Infant Benefits

This difference becomes important when comparing newborn protection. With Aditya Birla, any newborn treatment is an add-on and applies only if a valid maternity claim is triggered. It excludes congenital anomalies, and you need to add the newborn to the policy after 90 days.

With Niva Bupa Aspire, the newborn is covered from day 1 up to the full base SI. So if you need NICU (Neonatal Intensive Care Unit) care or congenital treatment, you can claim it up to your main cover.

Ditto’s Take

We usually recommend maternity benefits only when newborn coverage is the priority. That’s because most standard health insurance plans don’t cover a baby from day 1.

And if complications arise, costs can escalate quickly. For example, NICU care in India can cost about ₹5,000 to ₹10,000 per day or more, depending on the level of care.

So the real value of maternity in retail policies is the financial protection for the newborn in those first few days, when both risk and costs are the highest.

Activ One Maternity vs. Niva Bupa Aspire Sample Premium Comparison

Activ One Maternity Premium Table

Profiles for ₹1 Crore SI ₹50,000 Maternity Limit₹75,000 Maternity Limit₹1 Lakh Maternity Limit
(Family Floater): Ages (24, 25)₹74,216₹99,141₹1,22,293
(Family Floater, 2 Adults): Ages (35, 36)₹88,058₹1,12,983₹1,36,135
(Family Floater, 2 Adults): Ages (40, 41)₹97,107₹1,22,032₹1,45,184

The premiums are illustrative and calculated for adults living in Delhi (pincode: 110010) for a 3-year tenure with Claim Protect add-on. Your final premium will depend on your age, medical history, cover amount, and discounts.

Niva Bupa Aspire Premium Table

Profiles for ₹15 Lakh SIGold+Diamond+Platinum+Titanium+
(Individual Plan): Age 25₹12,746₹15,159₹16,137₹16,484
(Family Floater, 2 Adults): Ages (31, 32)₹21,003₹23,766₹26,240₹26,872
(Family Floater, 2 Adults, 1 Child): Ages (36, 35, 5)₹30,494₹34,535₹36,407₹36,646
(Family Floater, 2 Adults): Ages (62, 63)₹72,577₹82,829₹84,735₹85,310

The premiums are illustrative and calculated for adults living in Delhi (pincode: 110010) for a 1-year tenure with the Safeguard+ add-on. Your final premium will depend on your age, medical history, cover amount, and discounts.

Talk to an expert
today and find
the right
insurance for you.
Ditto Advisor

Aditya Birla Health and Niva Bupa: Performance Metrics

Metric (Average FY 2024-26)Aditya Birla HealthNiva BupaIndustry Average
Claim Settlement Ratio (CSR)96.25%92.92%92.02%
Incurred Claims Ratio (ICR) (FY 2023-25)68.16%58.10%81.88%
Volume of Complaints per 10,000 Claims18.6737.1329.35
Network Hospitals16500+10000+10,000+ (recommended)
Gross Written Premium / Annual Business - Total Health (In Crore)₹4,920.43₹6,985.24₹4,504.48

Note: This information is for the insurer as a whole and is sourced from the IRDAI annual reports and Aditya Birla Health and Niva Bupa’s public disclosures. To explore more such data, please refer to Ditto Data Lab.

Pros and Cons of Aditya Birla Activ One Maternity and Niva Bupa Aspire

Aditya Birla Activ One Maternity

Pros:

    • Short 3-Month Waiting Period: Useful if you’re already early into pregnancy.
    • Strong Base Plan: No room rent limits and unlimited restoration for regular hospitalizations under Activ One NXT.

Cons:

    • Low Maternity Cap: Delivery cover is capped at ₹30,000 to ₹1.5 lakh. The lower end of this range can fall short in metro hospitals.
    • High Upfront Cost: Requires 3 years of premium payments for both spouses, often more than the benefit itself.
    • No Advanced Treatment Covered: Surrogacy and adoption expenses aren’t included.
    • Limited Newborn Cover: It has an add-on of ₹50,000 to ₹2 lakh.

Niva Bupa Aspire

Pros:

    • Wider Maternity Scope: Includes delivery, IVF, infertility treatments, surrogacy, and adoption.
    • Booster+ Benefit: Unused maternity limits roll over and can grow significantly over time, based on entry age and variant.
    • Premium Lock-In: Entry-age premium stays fixed (lock the clock feature) unless you make a claim.

Cons:

    • Lower Initial Limits: Maternity cover starts small and builds over time.
    • Waiting Periods Vary: Lower variants come with longer waits (up to 4 years).

Why Choose Ditto for Health Insurance?

At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Pallavi love us:
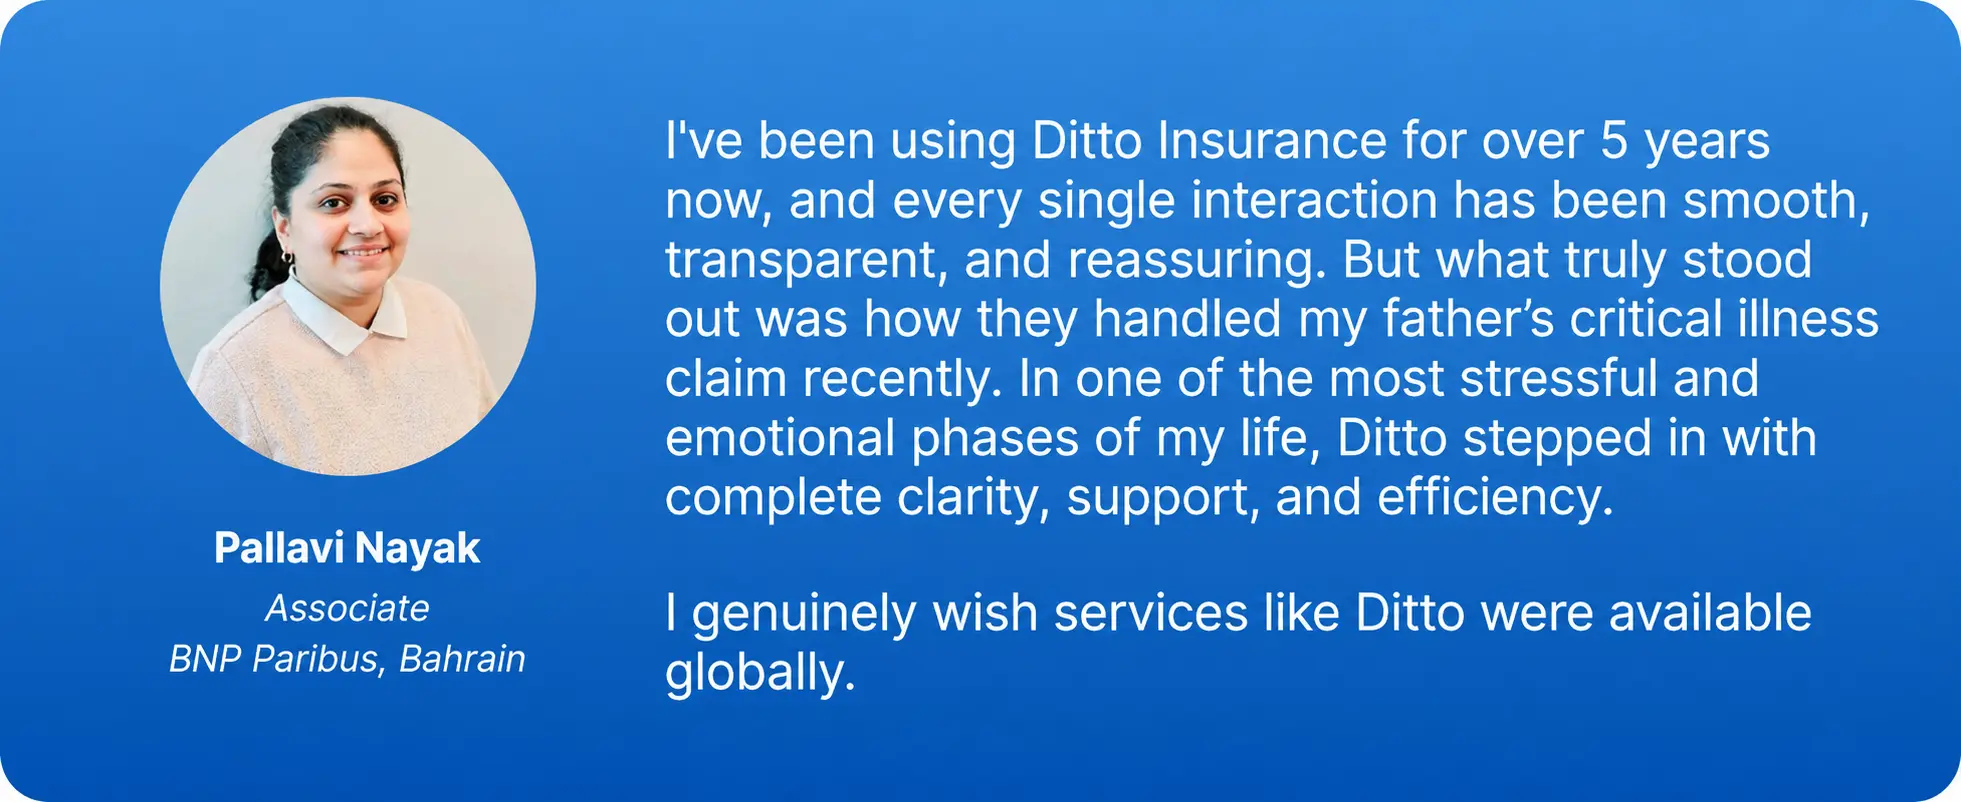
Pallavi Nayak LinkedIn Testimonial
    • 100% Free Consultation
    • No Spam. No Sales Pressure.
    • Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
    • Backed by Zerodha
    • Dedicated Claim Support Team
    • Compare Plans and Premiums with a Trusted Insurance Advisor

Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!

Conclusion

Activ One Maternity may suit buyers who need maternity benefits sooner, but its payouts are capped, especially for delivery and newborn care. Aspire, on the other hand, offers broader long-term maternity and newborn-related coverage.

Our Take: It’s better to start with a strong base health policy and treat maternity as a secondary decision. If you have employer coverage, that is usually a better place to look for maternity coverage since it comes without waiting periods or additional premiums. If maternity is a key requirement, first do a cost-benefit analysis of how much extra you pay in premiums versus the benefit you receive. Aspire tends to offer more meaningful coverage despite the wait.

For a better look at how maternity insurance works in India, check out our guide on maternity health insurance in India.

Disclaimer: This specific Activ One Maternity Plan combo is currently not available via Ditto and may be offered only via select aggregators. Please verify eligibility rules, tenure requirements, and do a quick cost vs. benefit check before opting.

Frequently Asked Questions

What is the maternity waiting period under Aditya Birla Activ One compared with Niva Bupa Aspire?

Under the Aditya Birla Activ One Maternity combo (via the rider), you can opt for a short 3-month waiting period, making it accessible if you’re planning a near-term delivery. In comparison, Niva Bupa Aspire has longer waiting periods that vary by variant, ranging from 9 months for Platinum+ and Titanium+ to 2 years for Diamond+ and up to 4 years for Gold+.

Which plan pays a higher maternity sub-limit for a normal delivery in a metro hospital?

Aditya Birla Activ One Maternity offers a fixed limit, regardless of the hospital location or whether it’s a normal or C-section delivery. Niva Bupa Aspire maternity coverage starts with a lower initial M-iracle limit (around ₹15,000 on a ₹15 lakh base policy). However, any unused amount carries forward each year and can grow significantly through the Booster+ feature, potentially reaching 10x over time if you make no claims, subject to entry age and variants.

Does Niva Bupa Aspire cover IVF and other assisted reproduction treatments?

Yes. The M-iracle benefit under Niva Bupa Aspire covers IVF and other infertility-related treatments. It also extends to surrogacy and legal adoption expenses. All of these are covered up to the available M-iracle limit, which can increase over time if you carry forward unused amounts through the Booster+ feature.

Is the newborn baby covered from day one under Activ One maternity or only after 90 days?

Under Aditya Birla Activ One Maternity, newborn medical expenses during hospitalization are covered, but only with an add-on of ₹50,000, ₹1 lakh, and ₹2 lakh. After 90 days, you need to add the baby to the policy separately with an additional premium. In contrast, Niva Bupa Aspire covers the newborn from day 1, and expenses are payable up to the full base sum insured you choose, offering significantly wider protection if complications arise.

Which Niva Bupa Aspire variant, Gold+ or Titanium+, should I pick for maternity cover?

If maternity is a near-term priority, Titanium+ is the better choice, as it has a shorter 9-month waiting period. This makes it practical if you’re planning a pregnancy within the next year or so. Gold+, on the other hand, has a much longer 4-year waiting period, which can delay access to maternity benefits.

Can I port an existing policy into either plan and carry forward my maternity waiting period?

Yes, you can port your policy under IRDAI guidelines. However, you can transfer maternity waiting period credit only if your existing plan already includes maternity benefits, subject to the new plan’s underwriting. Your completed waiting period is carried forward, but if the new plan has a longer waiting period, you must serve the remaining duration. For example, if you’ve completed 2 years in a plan with a 2-year wait and move to one with a 3-year wait, you’ll still need to complete 1 more year.

Should I buy a maternity plan two years before planning a baby or pay out of pocket instead?

If you’re planning a pregnancy in the next couple of years, buying a plan like Niva Bupa Aspire early can make sense. It allows you to complete the waiting period in time while gradually building your M-iracle limit. More importantly, it ensures newborn coverage, which can be valuable if complications arise. That said, if you're focused only on delivery costs, paying out of pocket is often simpler since maternity caps are limited. Also check if your or your spouse’s employer policy already includes maternity benefits.

Last updated on: