

GIFT City Insurance is gaining traction as more businesses and individuals explore insurance solutions linked to global markets. According to IFSCA’s dashboard, insurance entities at GIFT IFSC, including IIOs and Insurance Intermediary Offices (IIIOs), transacted over USD 546 million in premiums during April to June 2026, the first quarter of FY2026-27.
But what is driving this growth, and are these policies a good fit for you?
This guide explains how GIFT City Insurance works, who can buy it, its potential tax benefits, and the types of insurance policies offered.
What Is GIFT City Insurance?
“GIFT City Insurance” is not a specific product or category recognized by IRDAI. It refers to insurance issued through an IIO within GIFT City IFSC in Gandhinagar. These offices operate under the regulation of the International Financial Services Centres Authority (IFSCA).
IFSCA permits registered IIOs to offer life, general, health, and reinsurance business, subject to their approved classes of business. IIOs must transact insurance business in freely convertible foreign currencies other than Indian rupees. They may write direct insurance from the IFSC, other Special Economic Zones (SEZs), and outside India, subject to applicable regulations.
Did You Know?
Talk to an expert
today and
find
the right
insurance for you.
Who Can Buy GIFT City Insurance and How to Buy It?
Life and health insurance policies issued by an IFSC Insurance Office (IIO) are available to eligible buyers across several residency and business categories. Eligibility depends on the applicable IFSCA rules and, for Indian residents, RBI’s Liberalised Remittance Scheme (LRS) limits.
Indian Residents
May purchase eligible policies if total remittances, including premiums, remain within the RBI’s prescribed LRS limits.
Non-Resident Indians (NRIs)
Can purchase eligible life and health insurance policies.
IFSC-Based Units
Businesses or units located in an International Financial Services Centre can qualify.
SEZ-Based Units
Units located in a Special Economic Zone may purchase eligible policies.
Other Overseas Residents
Individuals who reside outside India may also qualify.
How Do You Buy GIFT City Insurance?
- Verify the Insurer: Check the IFSCA Directory to confirm that the insurer is authorized to operate through an IFSC insurance office. However, registration alone does not mean the insurer currently offers every type of retail insurance product.
- Verify the Product: Review the product brochure and policy wording before you buy. Check the IIO's IFSCA registration and the product's UIN, premiums, charges, benefits, policy currency, and country-specific eligibility requirements.
- Complete KYC and Tax Checks: Prepare your passport, overseas address, residency details, PAN if applicable, and tax identification number. You may also need to submit Foreign Account Tax Compliance Act (FATCA) or Common Reporting Standard (CRS) declarations, source-of-funds details, occupation, income, and net worth information.
- Complete Underwriting: Depending on the plan and coverage amount, the insurer may request a medical self-declaration, telemedical assessment, or medical examination. It may also assess your income, financial profile, and source of wealth before deciding whether to approve your application.
- Pay in the Permitted Currency: Pay premiums in an eligible foreign currency. NRIs may use permitted overseas banking channels or eligible NRE/FCNR funding arrangements. Indian residents must follow the RBI’s LRS requirements.
- Receive and Review Your Policy: Once the insurer approves your application and receives the premium, it issues the policy. Review the policy document carefully and confirm the coverage, exclusions, payment schedule, currency, and servicing options. Check how to contact the insurer from your country of residence.
What Insurance Products Are Offered Under GIFT City Insurance?
- Pure Term Life Insurance: GIFT City insurers offer USD-denominated term life insurance that protects beneficiaries after the policyholder’s death, if it occurs during the policy term. GIFT City life insurance plans like ICICI Life Global Life Protect suit people with foreign-currency income or family expenses, subject to eligibility and policy terms.
- Investment-Linked Life Insurance: GIFT City offers investment-linked life insurance plans like ICICI Life Global Wealth Multiplier and LIC Wealth Builder Plus that combine life cover with market-linked investment options. Depending on the product, policyholders can access international funds and build long-term wealth in foreign currency, subject to investment risk and policy charges.
- Education-Focused Insurance: Some GIFT City plans, like the HDFC Life US Dollar Global Education Plan, combine life insurance with investment options to help families build an education fund in foreign currency. These plans suit parents who expect future education expenses abroad, but returns and benefits depend on the product terms.
- International Health Insurance: GIFT City insurers offer international health insurance, such as HDFC Life Insignia Global Health, for individuals and families who need medical coverage outside India.
Tax Benefits of GIFT City Life Insurance for NRIs
- Tax Exemption on High-Premium Policies: According to Business Today, from FY 2025-26, qualifying life policies issued by an IFSC Insurance Office are exempt from the ₹2.5 lakh ULIP and ₹5 lakh non-ULIP premium caps under Section 11 (Schedule II), previously Section 10(10D).
- The 10% Sum Assured Condition Remains: The annual premium must not exceed 10% of the actual capital sum assured for maturity proceeds to qualify for exemption, subject to statutory exceptions.
- NRI Tax Residency Matters: Indian tax treatment may differ from the rules in your country of residence. Check local taxation, Double Taxation Avoidance Agreement (DTAA), and reporting requirements before purchasing a policy.
- Death Benefit Taxation: Death benefits are generally tax-exempt for beneficiaries in India, subject to applicable tax laws. If nominees reside overseas, additional tax rules may apply. Consult a qualified tax professional for guidance.
Note: GIFT City Insurance itself is not exempt from capital gains tax. That exemption applies to specific eligible transactions and entities, not all insurance investments.
GIFT City Insurance vs. Indian Insurance: Key Differences
Why Choose Ditto for Insurance?
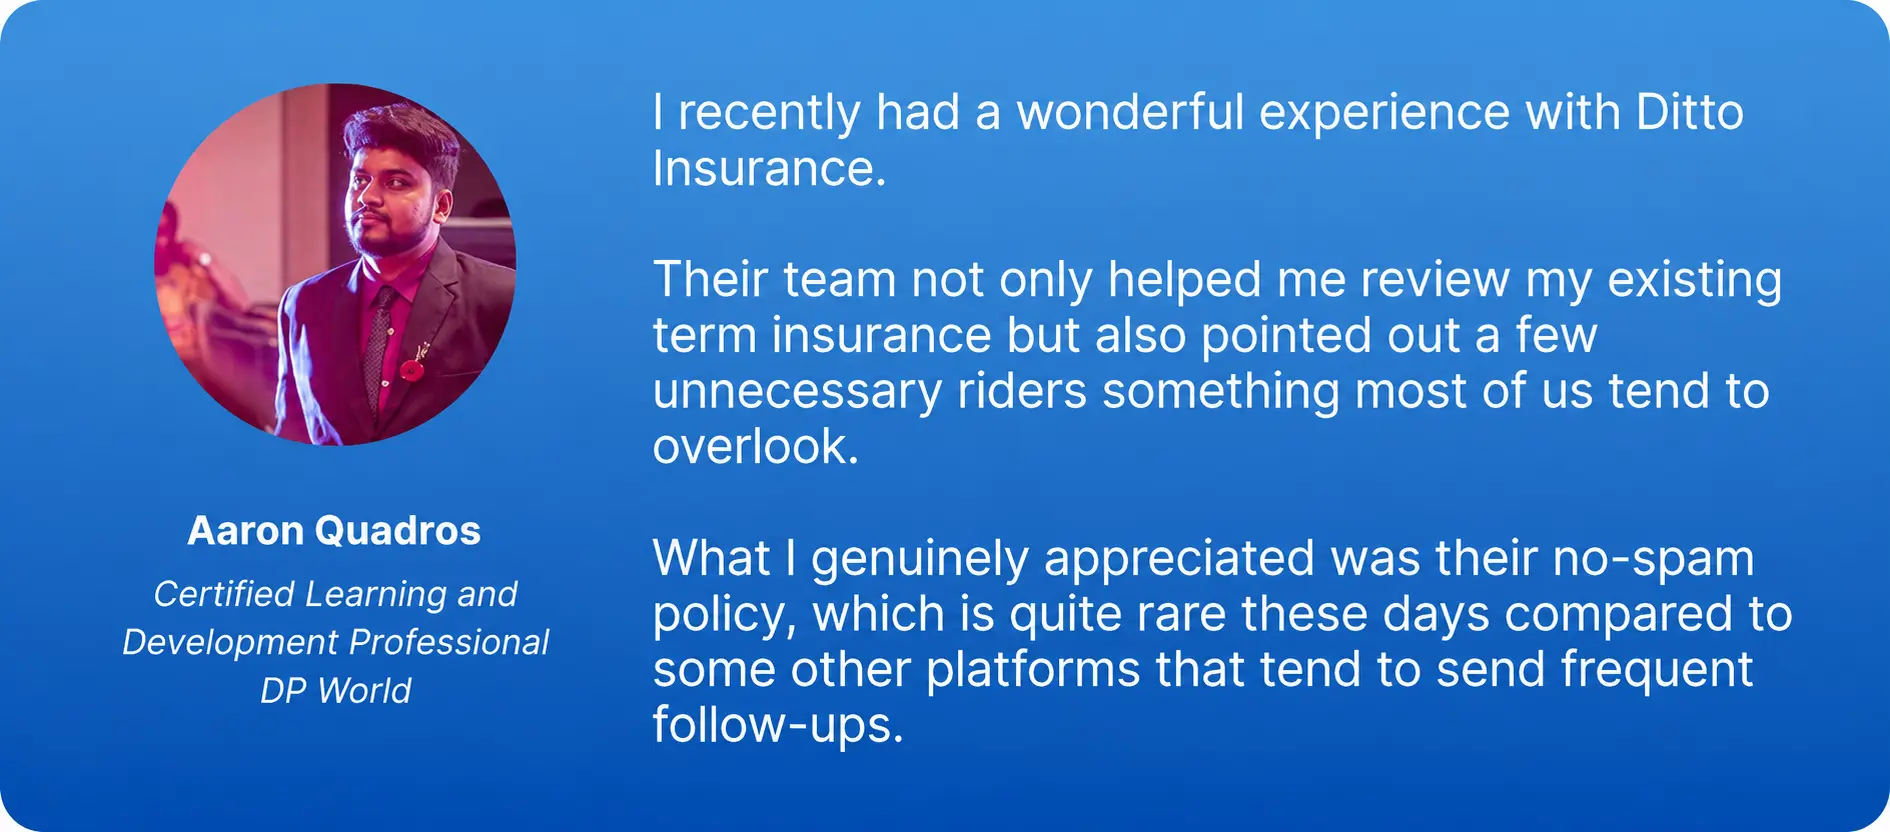
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
GIFT City Insurance can suit you if your income or future expenses involve foreign currencies. For medical expenses in India, compare the best health insurance plans. For family income protection, explore the best term insurance plans based on your coverage needs and budget.
Note: Ditto currently does not operate in the GIFT City Insurance segment. Our services are focused on conventional health insurance and term life insurance. For guidance on GIFT City Insurance products, consult a qualified expert advisor.
Frequently Asked Questions
Last updated on: