

Overview
India Post offers several life insurance options, including Postal Life Insurance (PLI), Rural Postal Life Insurance (RPLI), and Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY). However, these schemes differ in eligibility, coverage, and benefits, and most do not offer pure term insurance.
How Does Post Office Life Insurance Work?
Under Postal Life Insurance (PLI) and Rural Postal Life Insurance (RPLI), you pay premiums for life cover and savings benefits. If the policyholder dies during the policy term, their nominee receives the sum assured and applicable bonuses.
If you survive an eligible endowment or money-back policy, you receive the maturity benefits as per its terms.
Although backed by the Government of India, PLI and RPLI do not offer standalone pure term insurance. Their premiums cover both life insurance and savings benefits.
A pure term plan, in contrast, provides life cover for a specified period without a savings component. It offers higher coverage at a lower premium but pays no maturity benefit if you survive the policy term. Therefore, PLI and RPLI may not be suitable substitutes for pure term insurance if your primary goal is protecting your family's financial future.
Post Office Insurance Schemes: Available Plans and Their Features
1) Term Plans Sold Through India Post Payments Bank (IPPB)
India Post Payments Bank (IPPB), a corporate insurance agent registered with IRDAI (CA0574), distributes insurance policies issued by partner insurers. The insurer underwrites the policy and settles claims under the applicable terms and regulations.
IPPB's official term insurance page displays partner insurers, including HDFC Life, SBI Life, Axis Max Life, Bajaj Life, and PNB MetLife. Plans, eligibility criteria, and policy terms may vary, so check the official portal for the latest offerings before purchasing. You can also read our guide to India Post Payments Bank to learn more about its services.
2) Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY)
The Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY) is a government-backed, annually renewable life insurance scheme that provides ₹2 lakh in life cover for an annual premium of ₹436, generally auto-debited from the linked bank account.
Individuals aged 18 to 50 can enroll in the Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY), subject to the scheme's eligibility requirements and coverage limits. The policy can be renewed annually until age 55, subject to the applicable conditions. However, the ₹2 lakh life cover may not be enough to replace your family's income or meet significant financial obligations. Consider PMJJBY as supplementary protection rather than a substitute for adequate term insurance. Use Ditto's cover calculator to estimate how much life cover your family may need.
3) Postal Life Insurance (PLI)
Postal Life Insurance (PLI) was established in 1884 and provides life insurance to eligible employees and specified professional categories. It offers six principal plans, with a maximum sum assured on death of ₹50 lakh, subject to the applicable plan and eligibility conditions.
These plans offer different combinations of life cover, savings, and maturity benefits. However, PLI does not offer a standalone pure term insurance plan.
4) Rural Postal Life Insurance (RPLI)
Rural Postal Life Insurance (RPLI) was launched in 1995 to extend life insurance coverage to eligible rural residents. It offers several plans with a maximum sum assured of ₹10 lakh, subject to the applicable policy conditions:
- Gram Suraksha
- Gram Santosh
- Gram Suvidha
- Gram Sumangal
- Gram Priya
- Children's Policy (Bal Jeevan Bima)
PLI and RPLI offer flexible premium payment options, including monthly, quarterly, half-yearly, and annual payments, with rebates available for advance payments on eligible plans. Most plans offer bonuses and surrender value, subject to policy conditions. Policyholders may also access loans against eligible policies after a specified period. Policy servicing facilities also include nomination changes and policy transfers between post offices, subject to applicable rules.
Eligibility Criteria for Post Office Term Insurance
- Postal Life Insurance (PLI): Available to specified categories, including government and public sector undertaking (PSU) employees, defense personnel, eligible bank and educational-institution employees, professionals, employees of NSE/BSE-listed companies, and graduates or diploma holders from recognized institutions, subject to applicable eligibility rules.
- Rural Postal Life Insurance (RPLI): Initially designed for rural residents, RPLI expanded its eligibility criteria from August 14, 2026, to include applicants who maintain an operative savings account with a Post Office Savings Bank or any scheduled bank. Other policy conditions and underwriting requirements continue to apply.
- Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY): Open to eligible bank account holders aged 18 to 50 years.
- IPPB-Distributed Term Plans: Available to applicants who meet the partner insurer's eligibility (age, income, education, occupation, lifestyle) and underwriting requirements. Entry age is usually between 18 and 60/65 years, with coverage offered till ages 85 to 99/100 years
- Entry Age for PLI and RPLI: Generally starts at 19 years, with the maximum entry age ranging from approximately 40 to 55 years, depending on the plan.
- Medical Tests: May be required depending on the applicant's age, health profile, and sum assured.
Talk to an expert
today and
find
the right
insurance for you.
Tax Benefits on Post Office Term Insurance
Tax benefits on post office insurance depend on the policy type, the applicable tax provisions, and the tax regime you choose.
- Tax Deductions: From Tax Year 2026–27, eligible life insurance premiums may qualify for a deduction under Section 123 read with Schedule XV of the Income Tax Act, 2025 (earlier Section 80C) in the old tax regime, subject to the aggregate limit of ₹1.5 lakh and applicable conditions.
- Maturity Benefits: Maturity proceeds are exempt from tax only if the conditions under Schedule II are met, including the applicable premium-to-sum-assured rules and the ₹5 lakh annual premium threshold for eligible non-ULIP policies.
- Death Benefits: Death proceeds are exempt from the premium thresholds applicable to maturity benefits, subject to the relevant tax provisions. They are tax-exempt in the hands of the nominees.
Note: Earlier tax years: for periods before Tax Year 2026–27, the corresponding provisions of the Income Tax Act, 1961, apply. These deductions are subject to eligibility requirements and the applicable tax regime. Verify the latest rules before claiming a benefit.
Post Office Term Insurance vs. Private Term Insurance: Which Is Better?
How to Buy Post Office Term Insurance?
The application process depends on whether you want Postal Life Insurance (PLI), Rural Postal Life Insurance (RPLI), or a term insurance plan distributed through India Post Payments Bank (IPPB).
How to Apply for PLI or RPLI?
You can apply for PLI or RPLI through a post office that offers these services.
1) Visit a Post Office: Go to a Head Post Office or sub-post office that provides PLI or RPLI services.
2) Choose a Plan: Review the available policies and select one that meets your needs and eligibility requirements.
3) Complete the Application: Fill in the proposal form with your personal, professional, and nominee details.
4) Submit Documents: Provide the required identity, address, and age proofs. A medical examination may be necessary, depending on the policy.
5) Pay the Premium: Complete the payment process and retain your receipt and policy documents.
You can also explore the official Postal Life Insurance customer portal for online services.
Why Choose Ditto for Term Insurance?
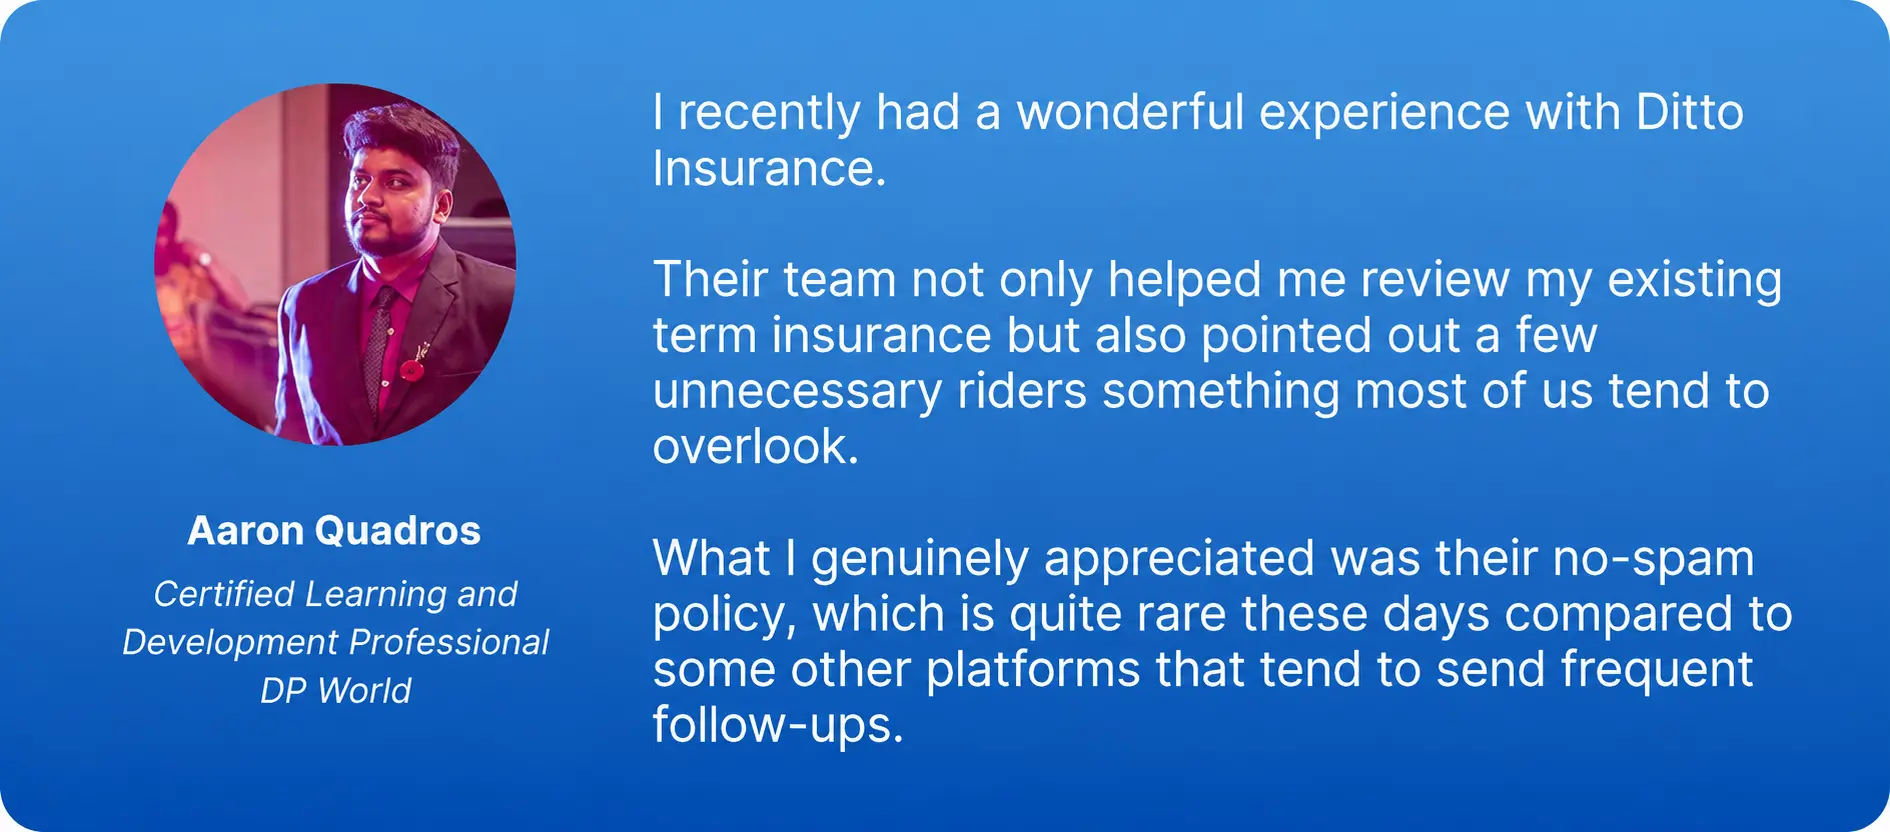
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Post office schemes are safe and government-backed, but PLI and RPLI are savings-oriented plans, and PMJJBY gives only ₹2 lakh. None of them substitute for comprehensive pure term insurance. To protect your family properly, choose a pure term plan from a reputed life insurer, and buy it with a trusted advisor who will support you after the sale and help your nominees with claims when something unfortunate happens. Explore our guide to the best term insurance plans in India to compare your options.
Disclosure: Ditto does not distribute PLI, PMJJY, or RPLI and has no commercial relationship with these schemes. Plans and insurers named here are for educational purposes only, sourced from publicly available information. Ditto, similar to IPPB, is an IRDAI-licensed Corporate Agent (CA0738).
Frequently Asked Questions
Last updated on: