

Overview
Digit Life and Axis Max Life take different approaches to term insurance. Digit Life Insurance focuses on a newer, digital-first experience, while Axis Max Life Insurance brings a longer track record and broader product features.
In this guide, we compare both insurers across factors, including plans, sample premiums, features, and insurer track record, so you can assess which option better aligns with your long-term protection needs.
Digit Life Insurance vs. Axis Max Life Insurance: Quick Comparison
Digit Glow Plus vs. Axis Max Life Smart Term Plan Plus: Coverage and Features Comparison
Coverage Offered
Digit’s official website states that Glow Plus (UIN: 165N007V03) offers a minimum sum assured of ₹2.25 lakh. However, during the actual purchase process, the minimum available cover is ₹25 lakh. We recommend confirming the applicable minimum cover before purchasing.
Axis Max Life Smart Term Plan Plus (UIN: 104N132V01) starts with a minimum sum assured of ₹25 lakh. The plan does not specify an upper limit, although the final cover remains subject to the insurer’s underwriting and applicable policy terms.
Note: The right coverage depends on your income, existing liabilities, future financial goals, and your family’s financial needs. Use the Ditto cover calculator to estimate the level of protection you may need.
Talk to an expert
today and
find
the right
insurance for you.
Built-In Features
Premium Break
Digit Glow Plus includes a premium break option through the Pay Later Option, where you can defer premium payments for up to 12 months. Smart Term Plan Plus also offers this feature through the Cover Continuance Benefit. Both plans offer the option after completing three policy years, subject to the policy terms and conditions.
Instant Payout Benefit
Unlike Glow Plus, Smart Term Plan Plus offers an accelerated payout from the base sum assured within one working day of claim registration, provided you submit the mandatory documents. After a one-year waiting period, eligible nominees may receive ₹25,000 for ₹25–₹50 lakh cover, ₹1 lakh for ₹50 lakh–₹1 crore, or ₹2 lakh for ₹1 crore and above. The remaining benefit is paid after the claim is approved. If the claim is rejected, you must refund the advance.
Smart Exit
Both plans offer a feature that lets you exit the plan and receive an amount equal to the total premiums paid. Under Smart Term Plan Plus, the option can be used after 25 policy years (but not during the final 4 policy years), while under Glow Plus, the option can be exercised after 29 policy years (but not during the last 5 policy years).
Terminal Illness Benefit
Both plans offer an accelerated terminal illness benefit. Smart Term Plan Plus pays 100% of the death benefit up to ₹1 crore, with waiver of premium on the remaining cover. Glow Plus pays up to ₹2 crore. If the death benefit exceeds ₹2 crore, future premiums are waived, and the remaining cover continues, subject to policy terms.
Wellness Benefit
Both plans offer wellness benefits that encourage policyholders to maintain a healthy and active lifestyle through preventive care and fitness services. However, the availability and features of these benefits may change based on the insurer's service providers and program terms.
Riders Available
- Waiver of Premium Rider: Glow Plus does not offer a waiver of premium rider. Smart Term Plan Plus offers a waiver of premium rider covering 11 listed critical illnesses and 4 total and permanent disability conditions. The rider can run for up to 30 years, with a 90-day waiting period and a 30-day survival period for critical illness claims.
- Critical Illness Rider: Unlike Glow Plus, Smart Term Plan Plus offers a critical illness rider covering 64 illnesses for up to 30 years. The rider provides an additional benefit of up to ₹50 lakh over the base cover, with a 14-day survival period.
- Accidental Death Benefit Rider: Both Glow Plus and Smart Term Plan Plus offer additional accidental death protection via a lump sum payout through the rider. The benefit is payable if the policyholder passes away within 180 days of an accident.
- Accidental Total and Permanent Disability (ATPD) Benefit: Both plans offer disability protection. Smart Term Plan Plus provides the benefit through its Critical Illness and Disability Rider, payable for either a covered critical illness or disability. Glow Plus offers a lump sum payout for total and permanent disability caused by an accident, subject to policy terms.
Note: At Ditto, we recommend riders such as Waiver of Premium (WOP) and Critical Illness (CI) when they address a genuine financial risk. WOP can help keep your policy active if you meet the rider’s specified conditions, while CI can provide an additional payout after a covered diagnosis.
Digit Life vs. Axis Max Life Sample Premium Comparison by Age and Cover
This illustration assumes a healthy, salaried, non-smoking male from Delhi (pincode: 110010) seeking ₹2 crore level term coverage until age 65, without first-year discounts. Actual premiums may vary based on underwriting, medical history, and other individual factors.
Insight: Smart Term Plan Plus costs more than Glow Plus, but the higher premium reflects its broader feature set, more useful rider options, and Axis Max Life's longer track record.
For buyers who value comprehensive protection and insurer experience, the price difference may be worth considering. For rough estimates of Smart Term Plan Plus, explore Ditto’s term premium calculator.
Digit Life vs. Axis Max Life: Performance Metrics Compared
Note: The data are sourced from IRDAI Annual Reports and Axis Max Life's public disclosures. For more insurer metrics, explore the Ditto Data Lab.
At Ditto, we use a 3-year average to reduce the impact of single-year anomalies and assess long-term consistency. However, Digit Life is a relatively new insurer, so it does not yet have enough data for us to reliably assess its long-term claims track record.
Digit Life reported ₹1,472.50 crore in business in FY 2026, compared with ₹14,503.29 crore reported by Axis Max Life during the same period. Additionally, Digit reported 20 complaints per 10,000 claims in 2026, compared with just 2 complaints per 10,000 claims for Axis Max Life.
Did You Know?
Pros & Cons of Digit Life and Axis Max Life Insurance
Pros of Digit Life
- Digital-First Experience: Digit offers a technology-led buying and servicing experience, with online applications, digital documentation, and app-based policy management.
- Simple Protection Structure: Glow Plus keeps the core structure straightforward, with two variants: Term Insurance and Term Insurance with Return of Premium. At Ditto, we do not recommend return of premium options as they cost 60% to 100% more than pure term plans and do not earn any interest on the base premiums returned.
- Established General Insurance Promoters: Digit Life benefits from the broader experience of Go Digit General Insurance, which has an established presence across motor and health insurance.
Cons of Digit Life
- Limited Track Record: Digit Life received its IRDAI registration in 2023, so it does not yet have long-term metrics to assess.
- Fewer Rider Options: Its term plans currently do not offer critical illness or waiver of premium riders.
- Newer Life Insurance Business: Its retail life insurance portfolio and track record are still more limited than established insurers such as HDFC Life, ICICI Prudential Life, and Axis Max Life.
- Higher Complaint Volume: Digit Life reported more complaints than Axis Max Life in FY 2026. This difference matters when assessing the insurer’s claims-servicing experience.
- Declining Solvency Ratio: Digit Life’s solvency ratio fell from 3.85x in 2025 to 1.84x in 2026. While 1.84x remains above the regulatory minimum of 1.5x, the sharp decline is worth monitoring as the insurer scales its life insurance business.
Pros of Axis Max Life
- Established Life Insurer: Axis Max Life has a longer operating history, established distribution network, and extensive experience in life insurance. This supports its long-term positioning.
- Strong Rider Ecosystem: The plan offers several rider options, including accident cover, waiver of premium, critical illness and disability, and accidental death and dismemberment protection.
Cons of Axis Max Life
- Complex Product Structure: The multiple variants and customization options can make Smart Term Plan Plus harder to understand and compare, especially for first-time buyers.
- Higher Premium: Smart Term Plan Plus costs more than Digit Glow Plus for comparable coverage, depending on the applicant profile and policy structure.
Why Choose Ditto for Term Insurance?
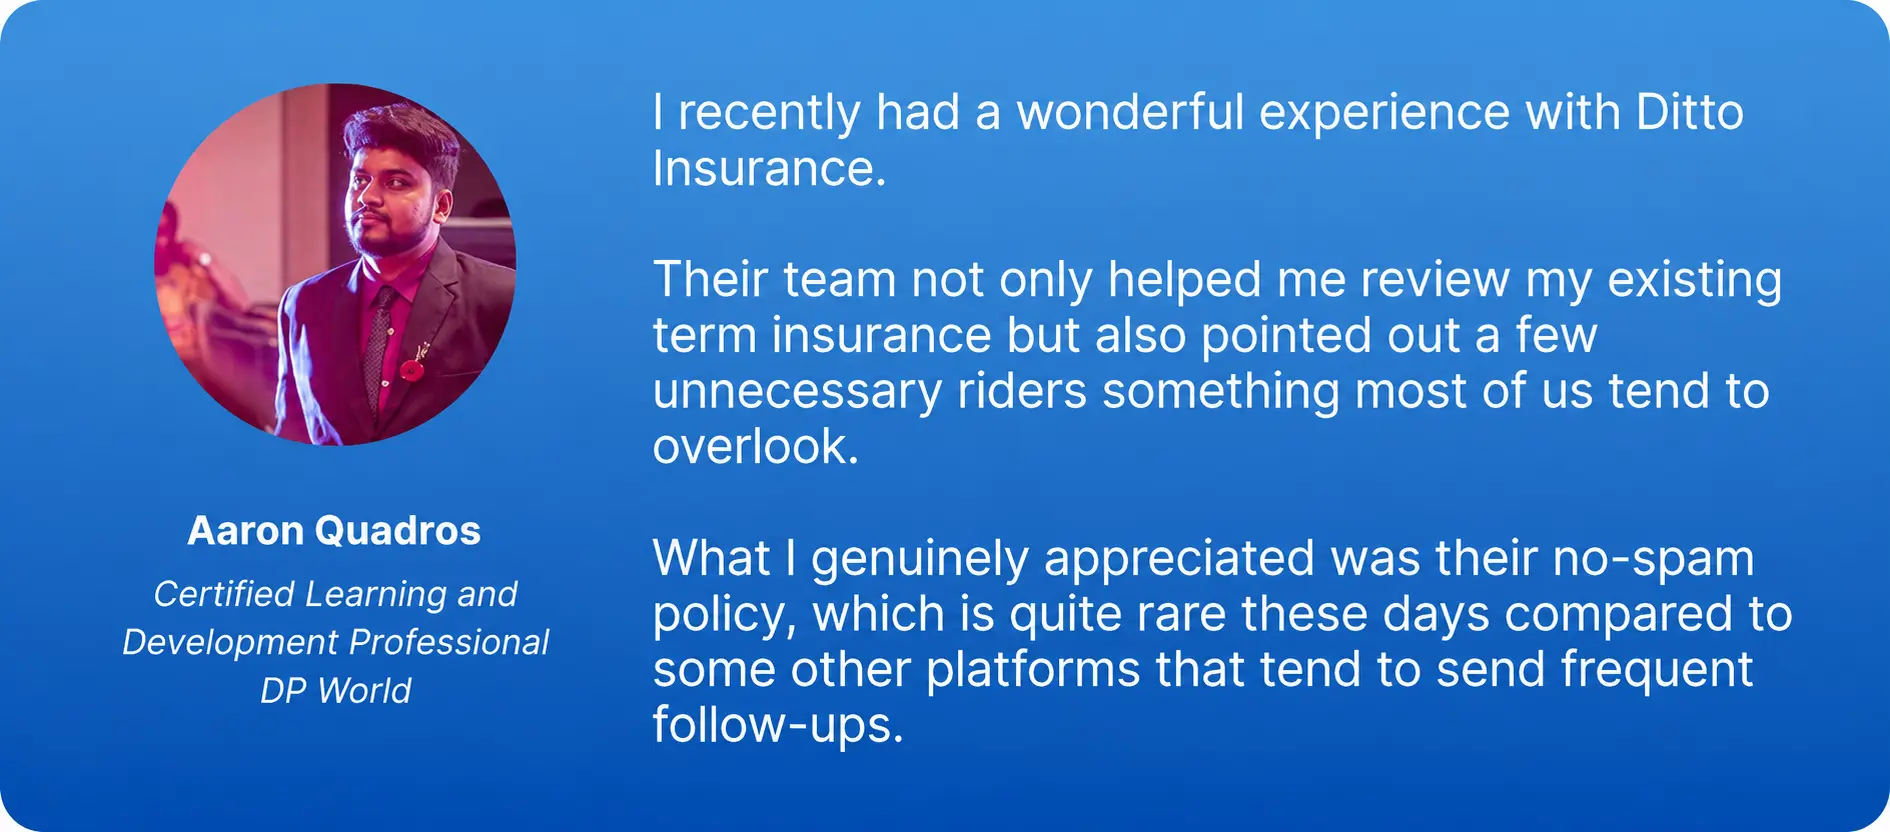
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Digit Life is a newer, digital-first insurer with a shorter track record and smaller scale. Axis Max Life offers stronger settlement metrics, established scale, and broader product features.
If you prefer Axis Max Life, explore plans like Smart Term Plan Plus, which also feature in our best term insurance plans list.
Frequently Asked Questions
Last updated on: