A ₹1 crore term insurance plan in India typically costs between ₹10,000 and ₹12,000 a year for a non-smoking male in his early 20s. However, the exact ₹1 crore term insurance premium can depend on your age, gender, tobacco use, riders, and the chosen plan.
Key Factors That Affect Your Premium
Age: Buying early can lock in a lower premium for the entire policy term.
Tenure: Cover till 85 or whole life (99/100) costs more than cover till 60 or 70.
Smoking: Smokers usually pay 60% to 100% more.
Riders: Optional add-ons that increase the total premium payable but may add valuable protection depending on the rider selected.
Return of Premium: Refunds eligible premiums if you outlive the term, but costs 60% to 100% more, sometimes even more.
Pre-Existing Conditions: Conditions like diabetes or high blood pressure can lead to a loading charge(an extra premium).
The cost of a ₹1 crore term plan can vary significantly depending on the insurer, your age, and personal profile. With premiums varying from one quote to another, it can be hard to know what you should pay and whether you’re getting a fair deal.
Understanding what influences your ₹1 crore term insurance premium can make this easier. Factors such as age, gender, and health profile all play a role, with buying early generally helping you secure a lower premium.
In this guide, we break down sample premiums by age and gender, the key factors that affect the cost, how premiums change after 60, and whether a Return of Premium plan is worth paying more for than pure term insurance.
Sample Premiums for ₹1 Crore Term Insurance by Age and Gender
Here are sample illustrative premiums for ₹1 crore of cover for healthy, salaried, non-smoking men and women in Delhi (pincode: 110010), covered till 65, excluding first-year discounts.
Note: Doubling your cover doesn’t double your premium. A ₹2 crore policy usually costs less than twice a ₹1 crore policy, because insurers price bigger covers lower per lakh. For example, a 25-year-old healthy, salaried male, covered till 65 under Smart Term Plan Plus pays ₹17,222 a year. However, the exact gap depends on the insurer and your profile.
Talk to an expert today and find the right insurance for you.
Factors Affecting ₹1 Crore Term Insurance Premium
The premium for ₹1 crore term insurance can differ a lot between two people buying the same cover.
01
Age
Your premium is set at the age you buy and stays fixed for the entire policy period. Every year you wait increases it.
02
Gender
Women generally pay lower premiums than men for comparable coverage because of lower average mortality risk. Premiums can be about 5% to 20% lower, depending on the insurer and entry age.
03
Smoking and Tobacco Use
Smokers and tobacco users can pay substantially higher premiums, around 60% to 100% more. For more details, you can refer to our guide on term insurance for smokers.
04
Health and Medical History
Existing medical conditions like diabetes, high blood pressure, or any past surgeries can lead to a loading (an extra premium) based on their severity and the insurer’s underwriting assessment. The loading range could be around 10%-40% or sometimes even higher depending on the case.
05
Cover Until Age
The longer your term insurance coverage continues, the higher the premium generally becomes because the insurer covers mortality risk over a longer period. At Ditto, we usually recommend cover until age 65 to 70. By then, your dependents are financially independent, your major loans are paid off, and you’ve built enough savings to support your family.
06
Occupation
Hazardous jobs, like mining, certain aviation roles, or construction-site work, and risky hobbies like skydiving or scuba diving may attract a higher premium or extra underwriting, depending on the insurer.
07
Pincode
Some insurers price or underwrite by location. For example, HDFC Life Click 2 Protect Supreme Plus can quote different premiums by pincode, though not all insurers do this.
08
Riders
Optional selected add-ons increase the total premium. So, select riders thoughtfully. At Ditto, we recommend Critical Illness and Waiver of Premium riders given their practical benefits, while generally advising against riders such as Accidental Death Benefit.
09
Premium Payment Term
You can pay for the whole term (regular pay), for fewer years (limited pay), or just once (single pay). Limited and single pay cost more each year, since the full premium is paid in fewer installments, but your cover continues after you stop paying.
10
Premium Payment Frequency
Paying monthly, quarterly, or half-yearly costs more than paying annually, because insurers add a modal loading charge.
Does ₹1 Crore Term Insurance Cost More if Bought After Age 60?
On HDFC Life Click 2 Protect Supreme Plus, a healthy 60-year-old non-smoking male pays about ₹81,440 a year for ₹1 crore of cover until 75. At 65, the same cover until 80 costs about ₹1,44,329, nearly 1.8 times as much.
However, cost isn't the only hurdle after 60:
Fewer Plans: Axis Max Life and ICICI Life accept buyers only up to 60. HDFC Life, Bajaj Life, and Aditya Birla Sun Life go up to 65.
Tougher Medical Checks: More detailed medical underwriting. Insurers may require blood tests, HbA1c, liver and kidney function tests, an ECG, or additional cardiac investigations such as a TMT or 2D Echo, depending on age, medical history, and other details.
Income Proof: Insurers look for active income from salary, business, or profession to assess eligibility. Pension and fixed deposit interest usually don't count, making fresh ₹1 crore cover difficult for fully retired applicants.
If you're over 60, check whether you need cover at all. Our guide onlife insurance for senior citizens explains when it makes sense and what to consider instead.
Return of Premium vs. Pure Term Insurance: Which Costs More for ₹1 Crore Cover?
A ₹1 crore term insurance with return of premium refunds the eligible premiums you've paid (as per the plan’s terms and conditions) if you outlive the policy period. But the refund comes without interest, and the plan costs about 60%-100% higher or sometimes even more than a pure term plan, based on your age.
Here's how the two compare on HDFC Life Click 2 Protect Supreme Plus. The figures below are illustrative annual premiums for ₹1 crore of cover until age 65 for healthy, salaried, non-smoking men and women in Delhi (pincode: 110010), excluding first-year discounts.
Age & Gender
Pure Term Premium
With Return of Premium (TROP)
25, Male
₹9,294
₹20,932 (125% increase)
25, Female
₹7,900
₹17,792 (125% increase)
30, Male
₹12,093
₹30,317 (151% increase)
30, Female
₹10,279
₹25,769 (151% increase)
35, Male
₹14,773
₹42,036 (185% increase)
35, Female
₹12,557
₹35,730 (185% increase)
40, Male
₹18,948
₹62,824 (232% increase)
40, Female
₹16,106
₹53,400 (232% increase)
Note: At Ditto, we recommend pure term insurance. Take the 30-year-old male in the table: TROP costs him ₹18,224 more a year. If he invests that amount each year instead in the Public Provident Fund (PPF), National Pension System (NPS), mutual funds, or Fixed Deposits (FDs), it could grow to about ₹20 lakh by age 65 at 6% per year. Actual returns will vary with the investment chosen.
Why Choose Ditto for Term Insurance?
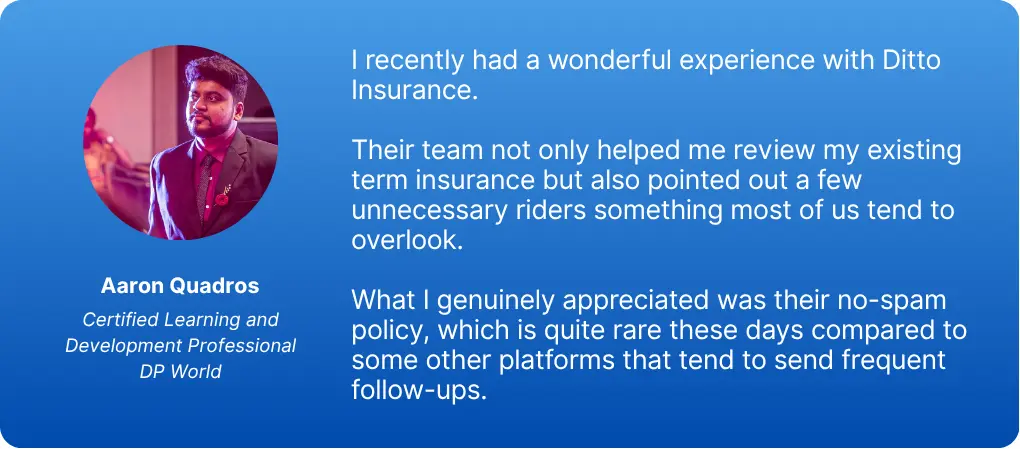
At Ditto, we’ve assisted over 12,00,000 people with choosing the right insurance policy. Why customers like Aaron below love us:
100% Free Consultation
No Spam. No Sales Pressure.
Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
Backed by Zerodha
Dedicated Claim Support Team
Compare Plans and Premiums with a Trusted Insurance Advisor
You can book a FREE consultation. Slots are running out, so make sure you book a call or chat on WhatsApp now!
Conclusion
The premium for ₹1 crore term insurance depends on your age, health, lifestyle, and the coverage options you choose. Buying early can help you secure a lower premium, but it's equally important to choose a cover amount that meets your family's financial needs.
₹1 crore may be enough for some families, while others may need more. Before comparing premiums, use Ditto's term insurance cover calculator to estimate how much protection you actually need. You can then compare plans and premiums to find an option that fits your budget.
Frequently Asked Questions
Do smokers pay more premium than non-smokers for ₹1 crore term insurance?
Yes, usually 60% to 100% more, because smoking raises the risk of heart disease, cancer, and other illnesses. Insurers count any tobacco use, including cigarettes, bidis, gutka, or chewing tobacco. To be treated as a non-smoker, you usually need to have been tobacco-free for 12 to 24 months, depending on the insurer. For example, on HDFC Life Click 2 Protect Supreme Plus, a healthy, salaried 25-year-old man in Delhi pays about ₹9,294 a year for ₹1 crore of cover till 65 as a non-smoker, and about ₹16,264 as a smoker, nearly 75% more.
Can two people of the same age pay different premiums for ₹1 crore term insurance?
Yes. Age is only one factor. Two 30-year-olds can pay different amounts if one is a woman, smokes, has a health condition, or works in a risky job. Their choices matter too, such as cover till 85 instead of 60, limited instead of regular pay, monthly instead of annual payments, or added riders. Some plans also price by pincode, and some offer first-year discounts to salaried buyers, such as 15% on Axis Max Life and 12.5% for regular pay or 15% for limited pay on ICICI Life. Finally, each insurer prices differently, so the same profile can get different quotes.
Is GST applicable to ₹1 crore term insurance premiums?
No. Since September 22, 2025, all individual life insurance policies, including term plans, are exempt from GST. Before that, term insurance premiums attracted 18% GST, so the same ₹1 crore cover now costs less. The exemption covers only individual policies. Group term insurance, such as the cover your employer provides, and group credit life policies linked to loans still attract 18% GST. If an older quote you received included GST, ask the insurer for a fresh one to see the current premium.
Does the premium for ₹1 crore term insurance stay the same every year?
Generally, yes. In a standard level-premium term plan, the contracted premium stays fixed throughout the premium-payment term and doesn't automatically increase as you age or develop a medical condition after purchase. However, your payable amount may differ if a first-year discount expires or if you make permitted changes to your coverage, payment mode, or premium-payment structure. For example, Limited Pay lets you finish paying premiums over fewer years than the total coverage period, usually with higher annual installments than Regular Pay. Always compare both first-year and subsequent-year premiums before buying.
Can I pay the premium for ₹1 crore term insurance monthly instead of annually?
Yes. Most insurers let you pay monthly, quarterly, half-yearly, or yearly. Monthly payments spread the cost and may suit a monthly salary, but the total you pay over a year is usually around 5% higher than a single annual premium. The grace period also differs: you get 15 days to pay a missed monthly premium and 30 days for other modes. If you miss the grace period, the policy lapses, though you can usually revive it within five years by clearing past dues and meeting the insurer's conditions.
Does my occupation affect the premium for ₹1 crore term insurance?
Yes, if your job carries a higher risk of accidents or health problems. People working in mining, aviation, or construction, for example, may pay a loading as per the insurer’s underwriting assessment if they choose to issue the policy. Insurers may also send an occupation questionnaire to understand the risks involved. Desk jobs usually get standard rates. Always describe your work accurately, including any travel or hazardous duties, because an incorrect occupation detail can lead to a claim being questioned later. If your job changes after you buy, your premium stays the same.
Is the ₹1 crore term insurance premium different for women?
Yes. Women usually pay 5% to 20% less than men for the same ₹1 crore cover, because they tend to live longer. On Axis Max Life, HDFC Life, and ICICI Life, women pay 15% less at every age in our sample table. Bajaj Life’s gap varies more with age, from about 5% at 25 to 20% at 40. The exact difference also depends on your health, lifestyle, and the insurer you choose, so compare quotes from a few insurers before you buy.