

Overview
Long-term insurance products can look attractive on paper, but the real value depends on how the benefits compare with the premiums, liquidity, and alternatives available to you. With a commitment that can stretch over several years, understanding actual cash flows matters more than focusing only on headline benefits.
This guide examines the newly launched LIC Bima Platinum in detail, including its premium structure, return potential, surrender and paid-up provisions, loan facility, tax considerations, and how it compares with other ways of building long-term wealth.
If you are researching an LIC new plan for 2026 or looking for a LIC new policy for 2026, this review covers the key details you should consider before buying.
What Is the LIC Bima Platinum Plan 770?
Life Insurance Corporation of India’s (LIC’s) Bima Platinum (UIN: 512N397V01), also known as LIC Plan 770, is a non-linked, non-participating, limited-premium individual savings plan that combines life insurance with guaranteed benefits. The policyholder pays premiums for a selected Premium Paying Term (PPT), while the policy continues for the longer policy term.
The plan provides a death benefit if the life assured dies during the policy term. If the life assured survives, the policy provides regular income benefits, a one-time booster income benefit, and a maturity benefit, depending on the selected PPT and policy term.
Bima Platinum is available through LIC's distribution channels, including agents, brokers, and Point of Sales Person-Life Insurance (POSP-LI), as well as through LIC's online purchase platform.
LIC Bima Platinum: Guaranteed Additions, Booster Income, and Regular Income Benefit
LIC Bima Platinum offers three key guaranteed benefits during the policy term. This makes it relevant for buyers specifically looking for an LIC guaranteed income plan with structured payouts.
- Guaranteed Additions (GA): Guaranteed Additions accrue at the end of each policy year during the PPT at the base rate of ₹70 per ₹1,000 of total annualized premiums paid. The rate can be higher if the policyholder qualifies for applicable incentives, such as those for a higher basic sum assured, online purchase, or existing LIC policyholder status. No further guaranteed additions accrue after the PPT.
- Regular Income Benefit: If the policyholder survives to the end of the PPT, the policy pays 10% of the basic sum assured. The first payment is made at the end of the PPT, followed by annual payments until the policy anniversary immediately before maturity, provided the policy remains in force and the life assured survives.
- Booster Income Benefit: A one-time benefit equal to 70% of the basic sum assured is payable on the specified policy anniversary, depending on the selected PPT.
Deferral of Income Benefits
Policyholders can choose to defer future regular income benefits and/or the booster income benefit until the date of maturity, subject to the policy conditions. Submit the request at least three months before the relevant benefit's due date, and ensure no policy loan is outstanding when exercising the deferral option.
For benefits falling due between May 1, 2026, and April 30, 2027, the applicable accumulation rate for deferred benefits is 5.78% per annum. This rate is fixed for each deferred benefit from its due date until withdrawal or policy termination, whichever is earlier.
Key Features, Riders, and Eligibility of the LIC Bima Platinum Plan
Note: The plan offers five optional riders, subject to eligibility and additional premiums. However, riders are not available for policies purchased through Point of Sale Person – Life Insurance (POSP-LI) or Corporate Point of Sale Person – Special Purpose Vehicle (CPSC-SPV) channels.
Optional Riders
- LIC’s Accidental Death and Disability Benefit Rider: Provides an additional lump-sum benefit on accidental death and financial support through monthly installments in case of qualifying accidental permanent disability.
- LIC’s Accident Benefit Rider: The policyholder may choose either the accidental death and disability benefit rider or the accident benefit rider, subject to the applicable terms and conditions.
- LIC’s New Term Assurance Rider: Provides additional term insurance cover, with the rider sum assured payable on the life assured’s death during the rider term.
- LIC’s Premium Waiver Benefit Rider: If the proposer dies while the rider is active on a minor's policy, future premiums on the base policy are waived for the applicable rider term.
- LIC’s Critical Illness Health Rider: Covers either 15 or 40 specified critical illnesses. The 40-illness option also includes an assisted living benefit, which provides monthly payouts for specified illnesses.
Ditto’s Take: Riders can provide useful additional protection, but choose them based on your specific coverage needs. A separate term or health insurance policy may offer more comprehensive protection than relying solely on riders.
Incentives on Guaranteed Additions
The base guaranteed addition rate of ₹70 per ₹1,000 of total annualized premiums paid can increase through specified incentives.
- High Basic Sum Assured: An additional ₹3 to ₹15 per ₹1,000 is available depending on the BSA and PPT, with the maximum incentive of ₹15 applicable to a BSA of ₹10 lakh or more under an 18-year PPT.
- Online Purchase: An additional ₹20 to ₹30 per ₹1,000 is available depending on the PPT.
- Existing LIC Policyholders and Eligible Nominees/Beneficiaries: An additional ₹1 to ₹2 per ₹1,000 is available depending on the PPT.
The plan also allows you to receive the maturity and death benefits in installments over 5, 10, or 15 years. A policy loan is also available subject to the policy's loan provisions.
LIC Bima Platinum Sample Premium and Returns Illustration
LIC’s Bima Platinum brochure provides sample annual premiums for a ₹3 lakh basic sum assured and a 30-year policy term for a standard life under the offline sales channel. The premium varies based on the policyholder’s age and selected Premium Paying Term (PPT). Buyers comparing an LIC best plan for savings should look beyond the premium and assess the actual cash flows and effective return.
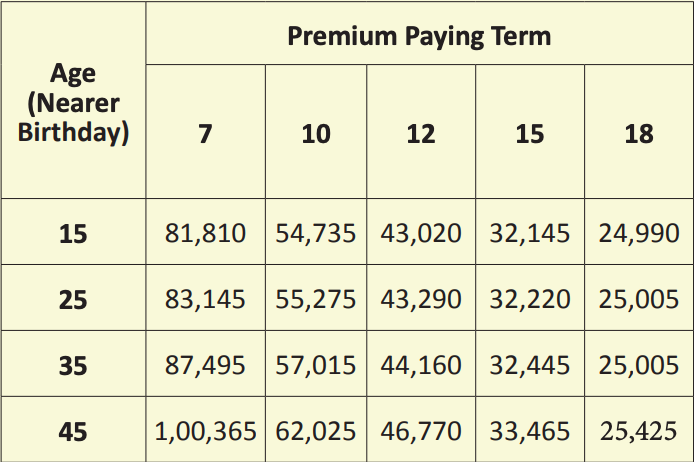
Note: The figures are annual premiums and are illustrative.
Returns Illustration
LIC's benefit illustration for a 35-year-old with a ₹10 lakh basic sum assured, 25-year policy term, and 12-year PPT assumes an annual premium of ₹1,46,650. The total premiums paid over 12 years are ₹17,59,800.
Note: Based on the timing of these cash flows, the effective annual return is approximately 5.27%. However, you should not treat the tax treatment as tax-free solely because the annual premium is below ₹5 lakh. Section 10(10D) has additional conditions that must be met. Buying the same plan online can increase the guaranteed addition rate and potentially push the effective return to around 5.6%.
Talk to an expert
today and
find
the right
insurance for you.
LIC Bima Platinum Guaranteed Additions Rate
LIC Bima Platinum offers guaranteed additions at a base rate of ₹70 per ₹1,000 of total annualized premiums paid during the premium-paying term. The rate can increase if the policyholder qualifies for applicable incentives.
Note: All figures are per ₹1,000 of total annualized premiums for premiums paid. The High Basic Sum Assured (BSA) incentive varies by the basic sum assured. The maximum shown applies to a BSA of ₹10 lakh or more.
Example: For an 18-year PPT with a basic sum assured of ₹10 lakh or more, an eligible online buyer can receive a maximum GA rate of ₹105 per ₹1,000 before considering the existing-policyholder incentive (₹70 base + ₹15 high-BSA incentive + ₹20 online incentive).
LIC: Performance Metrics
Note: The above metrics reflect LIC's overall performance and are not limited to any particular product. The data is sourced from IRDAI Annual Reports and LIC’s public disclosures. For more data like this, explore the Ditto Data Lab.
Pros & Cons of the LIC Bima Platinum Plan
Pros
- Guaranteed Benefits: Guaranteed additions and the plan’s income benefits are fixed under the policy and do not depend on LIC declaring bonuses or sharing its surplus.
- Multiple Payout Options: Policyholders can receive regular income and booster income benefits, defer these benefits subject to conditions, and choose to receive the maturity or death benefit in installments.
- Guaranteed Addition Incentives: Eligible policyholders can receive higher addition rates based on the basic sum assured, online purchase, and existing-policyholder or eligible nominee status.
- Built-In Liquidity: A policy loan facility is available, subject to the applicable terms and surrender value.
- Long-Term Income Structure: The plan provides an annual regular income benefit after the premium-paying term, potentially creating a predictable income stream during the Pay-out Period.
Cons
- Moderate Return Potential: The illustrated cash flows indicate an effective return of around 5.27% p.a. before taxes, which may be less attractive than some alternative fixed-income investments depending on prevailing rates and tax treatment.
- Early Exit Can Be Costly: While the policy can be surrendered for a surrender value, the guaranteed surrender value is limited in the initial years, making early surrender potentially unattractive.
- Limited Life-Cover Efficiency: The sum assured on death is the higher of 11 times the annualized premium or the basic sum assured, which may provide considerably less protection than a dedicated term insurance policy.
- Loan Comes at a Cost: The policy loan facility provides liquidity, but consider the applicable interest rate before using it as a borrowing option.
Why Choose Ditto for Life Insurance?
At Ditto, we’ve assisted over 12,00,000 customers choose the right insurance policy. Why customers like Vijay love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
LIC Bima Platinum is a savings-focused insurance plan that offers predictable, guaranteed payouts, but the trade-off is a relatively modest return and a long-term commitment. If you are evaluating this LIC new plan alongside other LIC savings products, focus on the effective return, liquidity, life cover, and tax treatment rather than guaranteed benefits alone.
If you are considering this plan, first make sure you have adequate term insurance. For long-term savings, compare Bima Platinum with options such as Public Provident Fund (PPF), Fixed Deposits (FDs), or debt mutual fund investments based on your return expectations, liquidity needs, and tax position.
In our view, Bima Platinum works better as a supplementary savings product for someone who values guarantees rather than as a replacement for term insurance or a dedicated investment portfolio. Before buying, compare the actual cash flows with a term plan plus separate investment for the same premium outlay.
Disclaimer: Ditto is not a SEBI-registered investment adviser. Consult a qualified financial and tax adviser before making investment decisions.
Frequently Asked Questions
Last updated on: