Life Insurance

What is the Free Look Period in Term Insurance?

Gargi Thakur

Written by Gargi Thakur

Editor

Ishita Jain

Reviewed by Ishita Jain

IRDAI-Certified Expert at Ditto

SP0738675913

Certified
What is the Free Look Period in Term Insurance?

Overview

The free look period is a 30-day window after you receive a new life insurance policy. During this time, you can review the terms and cancel the policy without paying a cancellation penalty. 

Key Features

  • Active Coverage: Your policy stays active during the window.
  • Protection: Guards you against mis-selling and terms you didn’t agree to.

Deductions On Refunds

  • Pro-rata risk premium for the days you were covered.
  • Medical exam costs (if any).
  • Stamp duty.

How To Cancel?

  • Send a cancellation request to your insurer or fill in its cancellation form.
  • Mention your policy number, reason for cancellation, and date of issuance.
  • Submit KYC or documents requested through your insurer's official cancellation process.
  • Once approved, the refund takes around 7 working days.

Mis-selling is one of the biggest problems in the Indian life insurance landscape. IRDAI's Annual Report FY 2024-25 recorded 26,667 grievances against life insurers under unfair business practices, up from 23,335 the year before. 

If your new insurance policy doesn't match what you were promised, the free look period lets you cancel it while getting most of your premium back.

In this guide, we break down how the free look period in insurance works, IRDAI’s rules, the cancellation steps, and what you’ll get back.

What Is the Free Look Period in Life Insurance? 

The free look period in life insurance is a 30-day window that starts when you receive your policy document, not when you pay the premium. During this time, you can review the policy in detail and decide whether it’s what you actually agreed to buy.

It protects you from mis-selling and getting stuck with unsuitable purchases. For example, let’s consider that someone enquired about pure term insurance, but the bank sold them a savings-linked life insurance plan instead. This is where the free look period comes in. It helps the person cancel the policy and get their premium back, minus a few permitted deductions.

Canceling isn’t your only option, though. During the free look period, you can request corrections, but changes to the sum assured, premium-payment term, or payment frequency depend on the plan's rules and insurer approval. These changes (if accepted) may take some time to process. You can still keep your cover without starting over.

The life insurance free look period applies to eligible new term plans, traditional savings plans, and Unit Linked Insurance Plans (ULIPs) with a policy term of at least one year. Only the refund calculation changes, which we cover below.

Insurers build this right into their process. For example, Axis Max Life has a dedicated free look cancellation form that policyholders can fill out to cancel a new policy within the window.

Free Look Period Rules by IRDAI for Life Insurance 

The IRDAI (Protection of Policyholders' Interests, Operations and Allied Matters of Insurers) Regulations, 2024, set the free look period at 30 days for policies bought through any mode. Before this, IRDAI's rules offered 15 days for policies bought offline and 30 days for policies bought online. That gap is no longer present. 

IRDAI's Master Circular on Protection of Policyholders' Interests, 2024 also states what the insurer must offer you once your policy is issued.

Insurer Must Inform About Free Look Period

Once the insurer accepts your proposal, it must share all the important policy documents with you within 15 days, at no extra cost. These include your policy document, covering letter, a copy of your proposal form, benefit illustration, and Customer Information Sheet (CIS), along with any other required documents, such as a needs-analysis report, wherever applicable.

Receiving Policy Document

Most policies are now issued electronically and digitally signed. The 30 days start when the e-policy reaches you, and you can still ask for a physical copy.

Refund Has a Deadline

The insurer must refund your eligible premium (minus applicable permitted deductions) within 7 days of receiving your request. In case of any delay, the insurer must pay interest at the bank rate + 2% on the refundable amount.

Insurer Will Ask for a Reason

Under IRDAI guidelines, insurers may ask for a reason to cancel the policy. But irrespective of the reason, they must accept the cancellation. 
Background Image

How to Cancel Your Policy During the Free Look Period: Step-by-Step Process

01

Check Your Dates

Note the date you received your policy document, then count 30 days from that date. Keep proof of receipt. Don’t leave your request to the last day.

02

Write to Your Insurer

Email customer support, use the insurer's app or website, or visit a branch to start the cancellation process.

03

Fill the Cancellation Form

Most insurers have a free look cancellation form. Mention your policy number, date of issue, and reason for cancellation.

04

Attach Your Documents

The original policy document, premium receipt, KYC documents, a canceled cheque for the refund, and any identity verification and bank details the insurer actually requires.

05

Track the Refund and Get Confirmation

Expect the applicable refund amount within 7 working days of your request. 

If the insurer delays or rejects a valid request, write to its Grievance Redressal Officer (GRO). You can then escalate through IRDAI's Bima Bharosa portal and, where eligible, the Insurance Ombudsman. 

Talk to an expert
today and find
the right
insurance for you.
Ditto Advisor

Refunds and Deductions: Free Look Period

DeductionWhat It CoversWhen It Applies
Pro-Rata Risk PremiumThe cost of cover for the days your policy was active.Only for the days your cover was active, counted from the risk start date on your policy document.
Medical Exam CostsTests the insurer arranged before issuing your policy.Only if you went through insurer-arranged medical tests.
Stamp DutyGovernment duty paid on the policy.Always. The amount depends on your sum assured.

Note: Deductions don't depend on your payment frequency. Irrespective of monthly, quarterly, or yearly payments, the deduction amount remains the same. If valid deductions exceed the amount paid so far, the net refund may be nil. Always ask for an itemized calculation.

According to our experience at Ditto, most insurers mandatorily deduct medical costs and stamp duty. Standard medical tests cost around ₹2,000 to ₹3,000. Stamp duty varies with your policy value. So, for a ₹1 crore cover, it’s around ₹3,000 to ₹4,000, and it increases as your coverage rises.

Common Mistakes to Avoid

Wrong Start Date

The 30 days start when you receive the policy document, not when you pay. If you miss this window, regular-pay pure term plans usually have no surrender value. Some single-premium and limited-pay term plans may return a surrender value or the premium for unused cover. What you get depends on your policy’s surrender and exit rules.

Canceling, Not Correcting

Depending on the insurer’s approval only, premium frequency, payment term, or sum assured can often be changed during the free look period. Canceling and reapplying means fresh medical tests and underwriting.

Not Checking Documents

Compare the policy schedule, Customer Information Sheet, benefit illustration, and proposal-form copy with what you agreed to buy. Check the product name, premium payment term, cover term, medical, lifestyle, and tobacco disclosures, extra premiums (if any), riders, and the payout option. Report any mismatch to the insurer in writing.

Canceling Too Early

If you are buying a new policy and canceling the old one, wait for the new plan to get approved before initiating the cancellation process. However, don't let underwriting delays on the new policy cause you to miss the existing policy's free-look deadline.

Why Choose Ditto for Term Insurance?

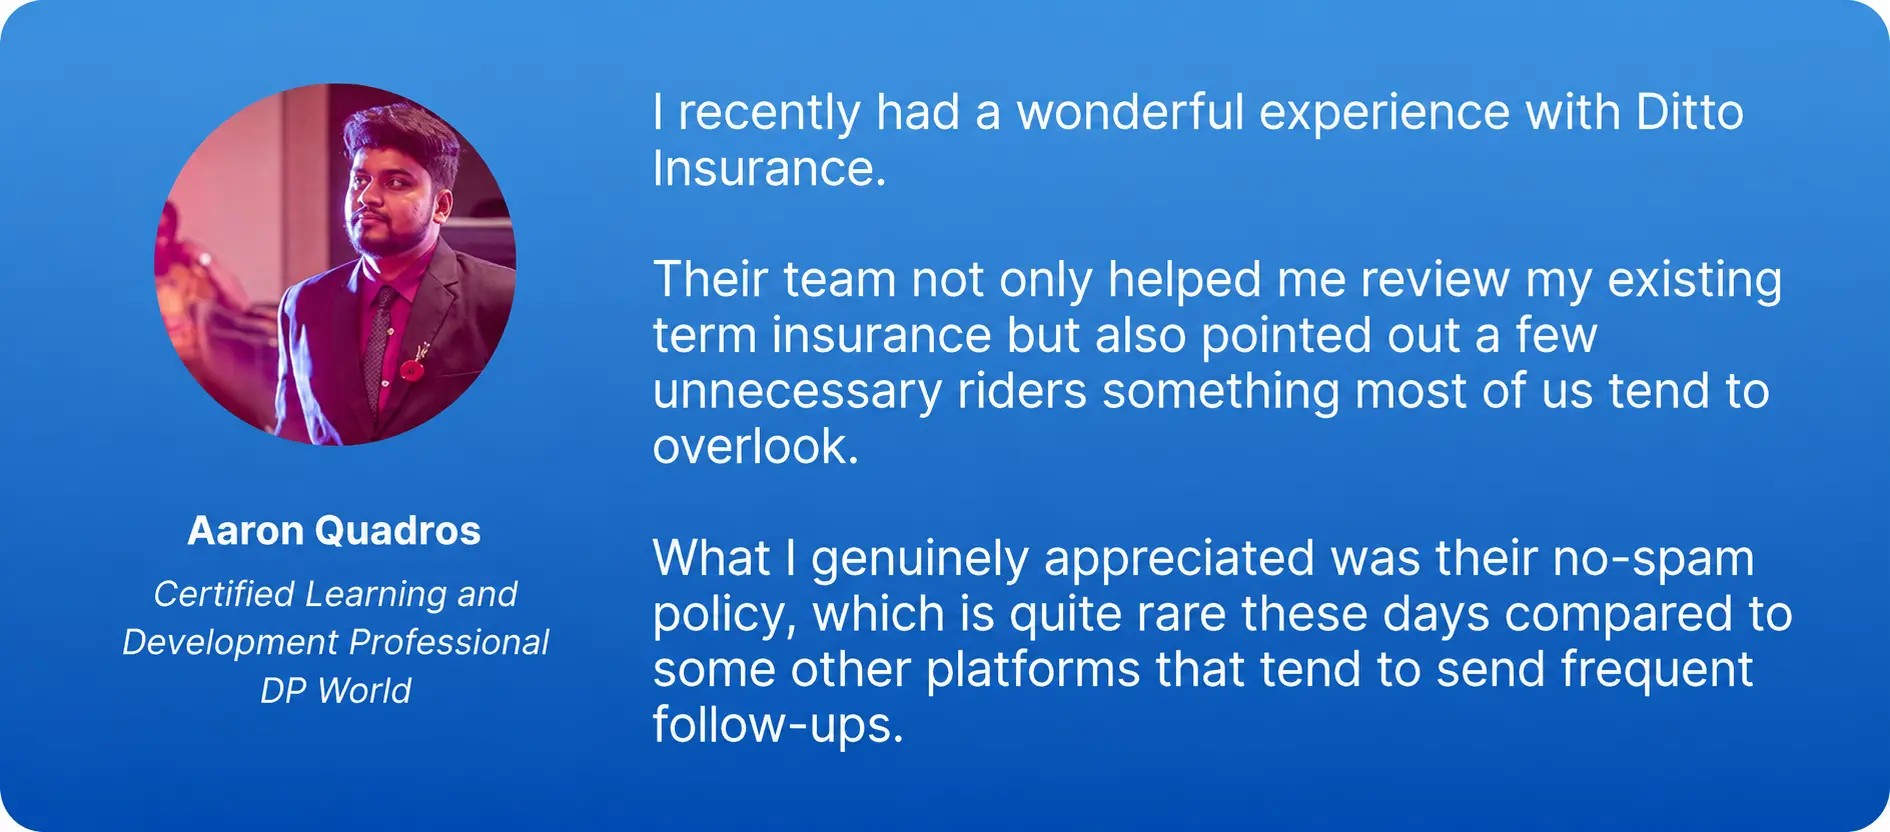
At Ditto, we’ve assisted over 8,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
Aaron Quadros LinkedIn Testimonial
    • Dedicated Claim Support Team
    • 100% Free Consultation
    • Backed by Zerodha
    • Rated 4.9/5 on Google Reviews by 15,000+ happy customers
    • No-Spam & No Salesmen

You can book a FREE consultation. Slots are running out, so make sure you book a call now or chat over WhatsApp with our advisors.

Conclusion

Think of the free look period as a safety net, not a substitute for choosing the right policy. Many issues can be avoided before purchase by understanding the policy terms and disclosing all your details honestly.

Once you receive your new life insurance policy, you have 30 days to review it. If the policy doesn't match what you were promised, you can cancel it and get your premium back, minus applicable deductions. However, if it's just a minor error, getting it corrected is usually better than canceling the entire policy.

Take some time to review your policy schedule, Customer Information Sheet (CIS), and proposal form. Compare these documents with what was explained to you when buying the policy. If you notice any discrepancies, contact your insurer in writing before the 30-day period ends.

Frequently Asked Questions

Does the free look period start from the date of purchase or the date I receive the policy document?

It starts from the date you receive the policy document, not the date you pay the premium. For e-policies, this is the date the insurer delivers the document to your email, SMS, WhatsApp, or portal, even if you open it later. So if you paid on the 1st and the policy reached your inbox on the 10th, your 30 days count from the 10th.

Can I cancel a term insurance policy bought online after the free look period?

Yes, but you usually won’t get your premiums back. Regular-pay pure term plans generally have no surrender value. Some single-pay and limited-pay plans may return the premium for the unused cover period, depending on your policy’s exit rules. If you stop paying, your cover continues through the grace period: 15 days for monthly premiums and 30 days for other modes. After that, the policy lapses.

Do I need to provide a reason for canceling my life insurance policy during the free look period?

Yes, you'll usually be asked to state one, such as terms you disagree with, hidden clauses, or a better alternative. But the reason doesn't decide the outcome. As long as your request reaches the insurer within the 30-day window, the insurer must accept it and refund your premium, minus the permitted deductions.

Will canceling a life insurance policy during the free look period affect my ability to buy another policy?

Canceling within the free look period is a right under IRDAI's rules. That said, frequent cancellations or lapsed policies can raise concerns with insurers when you apply again. Also remember that a new policy is priced on your age and health when you apply, and it may need fresh medical tests.

How long does it take to receive a refund after canceling a life insurance policy during the free look period?

The insurer must process your refund within 7 working days of receiving your cancellation request. If it is delayed, it must pay interest at the bank rate + 2% on the refundable amount.

Is the free look period in health insurance the same as in life insurance?

Mostly, yes. The health insurance free look period is also 30 days from the date you receive the policy document, for policies with a term of at least one year. One main difference is claims. If you make a claim during the window, you usually lose the right to a free look refund. For prepaid multi-year policies, though, you can still get a refund for future policy years that haven’t started. For renewals, portability, or migration, check your current policy document and the applicable rules.

Will I get a refund if I pay monthly premiums and cancel during the free look period?

Possibly not. Insurers can deduct the pro-rata risk premium, medical exam costs, and stamp duty from your refund. These charges don’t shrink just because you pay monthly or quarterly. So if the permitted deductions add up to more than the instalment you’ve paid, you may get little or nothing back. Before you cancel, ask your insurer for the exact refund calculation.

What should I check in my life insurance policy during the free look period?

Start by comparing the documents with what you agreed to buy. The policy schedule, the Customer Information Sheet, the benefit illustration, and your copy of the proposal form. Check that the product name, sum assured, cover term, and premium payment term are correct. Make sure your medical and tobacco disclosures were recorded accurately. Also look for any extra premium, the riders you chose, and the payout option.

Last updated on: