

Overview
Most health insurance plans come with a fairly fixed structure. Chola MS Flexi Health tries to give you more control, letting you customize parts of the cover based on what you actually need.
That flexibility can be useful, especially as healthcare costs rise. But the plan still comes with certain limits, exclusions, and waiting periods that can affect how much value you really get from it.
So, let’s break down how Chola MS Flexi Health works, what you can customise, where the plan stands out, and the fine print you should know before buying.
Not sure if a health plan from Chola MS General Insurance is the right fit for your medical needs? Book a free call or WhatsApp us and let our expert advisors help you.
What Is the Chola Flexi Health Policy?
Flexi Health by Cholamandalam Health Insurance is a customizable indemnity-based health insurance plan that covers hospitalization, day-care treatments, domiciliary care, and other medical expenses.
Note: This review covers Chola MS Flexi Health (UIN: CHOHLIP24145V062526) specifically. It should not be confused with other Chola MS health insurance products or plans with similar names like Flexi Supreme, as their features, benefits, and terms may differ.
Talk to an expert
today and
find
the right
insurance for you.
Chola Flexi Health: Eligibility and Sum Insured Options
Key Features and Riders of Chola Flexi Health
Inbuilt Features of Chola Flexi Health
Cumulative Bonus
Earn a 10% increase in sum insured for every claim-free year, up to a maximum of 50%. However, a 10% reduction applies to the accumulated bonus when you make a claim, subject to the policy terms. Emergency Ambulance Expenses: Covers emergency ambulance expenses up to 1% of the sum insured, capped at ₹2,000 per hospitalization.
Newborn Baby Cover
Coverage starts from day one if the mother has been continuously insured under the policy for at least 12 months, subject to policy terms. The coverage is subject to a limit of 10% of the sum insured, subject to a maximum of ₹50,000, whichever is less, within the Mother’s sum insured.
Pre- and Post-Hospitalization Expenses
Covers eligible medical expenses incurred up to 30 days before hospitalization and 60 days after discharge, subject to the policy’s terms, conditions, and applicable limits.
Room Rent Limit
Room rent is capped at ₹2,000 per day for policies with a sum insured of ₹50,000, ₹1 lakh, or ₹2 lakh, subject to the applicable policy terms. No room rent restriction for policies with a sum insured of more than ₹2 lakh.
Waiting Period
A 30-day waiting period applies for illnesses, except for eligible accidents. A 2-year waiting period applies to specified illnesses and treatments listed in the policy. Pre-existing diseases are covered after a 36-month waiting period, subject to policy terms.
Additional Riders Offered by Chola Flexi Health
- Sum Insured Restoration for Unrelated Claims: The plan can restore up to 100% of the sum insured when it is exhausted or insufficient due to unrelated claims. However, this benefit does not apply to claims arising from road traffic accidents. The restoration benefit applies to sum insured amounts of ₹3 lakh and above and is available once per policy year for individual or floater coverage, as applicable.
- Recharge Benefit for Related Claims: If your sum insured has already been used for a hospitalization claim, this benefit can provide additional sum insured for related claims up to ₹2 lakh, subject to defined limits. It does not apply to hospitalization arising from road traffic accidents and is applicable once during the policy year.
- Additional Sum Insured for Road Traffic Accidents (RTA): For hospitalization following a road traffic accident, the plan provides an additional sum insured of up to 25% of the base sum insured, capped at ₹3 lakh. This benefit is available once during the policy period.
- Daily Care Benefit: The Daily Care Benefit provides ₹500 per day toward the expenses of an accompanying person during hospitalization, subject to a maximum of 10 days per policy period. This can help cover incidental costs during longer hospital stays.
- Compassionate Travel: In a life-threatening medical emergency, an immediate family member can receive reimbursement of air travel expenses incurred to visit the hospitalized insured. The benefit is capped at ₹5,000 and applies subject to the policy terms.
- Repatriation of Mortal Remains: If the insured dies during the policy period, the plan can cover eligible expenses to transport the mortal remains, up to ₹3,000.
- Medical Second Opinion: The plan provides access to a specialist medical second opinion for an admissible claim up to ₹25,000. This can be useful when you want additional medical input before proceeding with major treatment decisions.
- Flexi OP Care Add-On: Policyholders can choose from four variants of Flexi OP Care by paying an additional premium. It covers eligible outpatient consultations, discounted medicines, and diagnostic expenses without hospitalization, subject to selected variant terms.
Chola Flexi Health: Sample Premium by Age & Cover
Note: The annual premiums shown are indicative quotes derived from the policy rate chart for a ₹15 lakh SI and exclude add-ons and applicable discounts. Actual premiums vary based on age, location, medical history, discounts, and selected add-ons.
You can refer to the policy rate chart for rough estimates of your premiums. However, premiums vary based on whether you live in a Tier 1 or Tier 2 location. Tier 1 includes Mumbai, Chennai, Bengaluru, Kolkata, New Delhi, Gurgaon, Hyderabad, and Ahmedabad. All other locations in India are classified as Tier 2, subject to the insurer's classification.
Chola MS: Performance Metrics
Note: This information is derived from the IRDAI annual reports and Chola MS public disclosures. To explore other insurer metrics, explore Ditto Data Lab.
Pros and Cons of the Chola Flexi Health Policy
Pros of Chola Flexi Health Policy
- Health Check-Ups: Get a health check-up once every two claim-free years.
- No Room Rent Limit Over ₹2 Lakh SI: Hospital room expenses are not capped by a specific room category, and the insured can choose any room.
- Large Hospital Network: Access to a wide network of partnered hospitals for cashless treatment.
- No Third-Party Administrator (TPA), Direct Settlement: Claims are handled directly without involving a separate third-party administrator.
Cons of Chola Flexi Health Policy
- 20% Co-payment: A 20% co-payment applies when you choose a Tier 1 hospital while paying premiums for Tier 2 coverage.
- No Consumables Cover: Consumables are not covered, unlike plans such as Activ One MAX, which include this benefit as a built-in cover.
- Limited Pre- and Post-Hospitalization: Coverage is limited, compared with longer coverage under some competitors. Plans like Optima Secure+ offer coverage that extends 60 days before hospital admission and 180 days after discharge.
- Limited Restoration: The restoration structure is more restrictive than many newer health plans. Chola separates additional protection into three buckets: 100% restoration once a year for future unrelated claims, a capped recharge for repeat or related claims, and a separate 25% RTA benefit. This is not equivalent to unlimited restoration, which can repeatedly replenish the full sum insured.
Why Choose Ditto for Health Insurance?
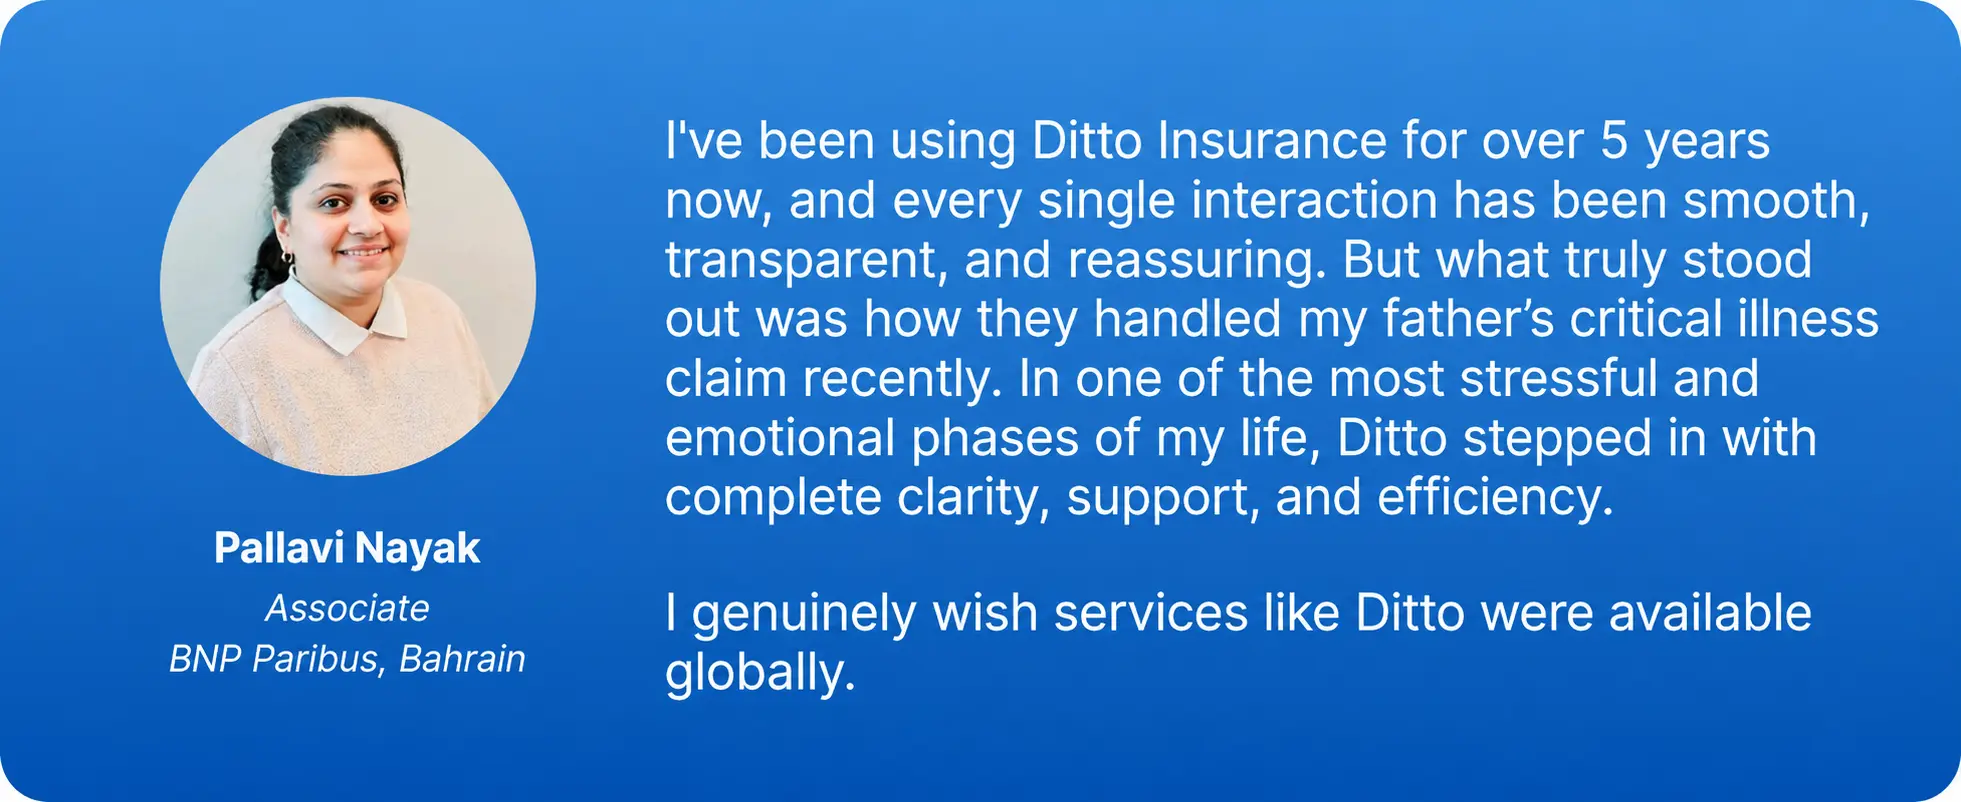
At Ditto, we’ve assisted over 12,00,000 customers choose the right insurance policy. Why customers like Pallavi love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Chola MS Flexi Health is a decent health insurance plan. However, it lacks some valuable features, including unlimited restoration and add-ons that can reduce waiting periods for pre-existing diseases.
The insurer operates with a fairly low claim settlement ratio, smaller scale, and limited market presence, which also raises concerns when compared with established insurers. Given the alternatives available today, we recommend exploring the best health insurance plans from established insurers before considering this plan.
Frequently Asked Questions
Last updated on: