Life Insurance

Top 10 Claim Settlement Ratio for Life insurance

Vasudev Pandey

Written by Vasudev Pandey

Insurance Writer

Gaurav Bhat

Reviewed by Gaurav Bhat

IRDAI-Certified Expert at Ditto

SP0738578124

Certified
Top 10 Claim Settlement Ratio for Life insurance

Overview

Top life insurers feature Claim Settlement Ratios (CSR) above 99% based on IRDAI data and insurer’s public disclosures. At Ditto, we assess the top 10 claim settlement ratio of life insurance companies using a 3-year average to smooth single-year anomalies and reflect long-term consistency.

Top 10 Life Insurers by CSR (Average (FY 2024-26))

  • Axis Max Life Insurance: 99.71%
  • HDFC Life Insurance: 99.66%
  • PNB MetLife Insurance: 99.53%
  • Canara HSBC Life Insurance: 99.42%
  • TATA AIA Life Insurance: 99.36%
  • Bajaj Life Insurance: 99.32%
  • Pramerica Life Insurance: 99.30%
  • ICICI Prudential Life Insurance: 99.30%
  • Edelweiss Life Insurance: 99.28%
  • Bandhan Life Insurance: 99.30%

Understanding Claim Settlement Ratio 

  • Definition: CSR is the percentage of death claims a company pays out compared to the total claims received in a year.
  • Decent Ratio: Anything above 97% is reliable.
  • Other Factors: Check the amount settlement ratio and complaints volume.

When it comes to term insurance, CSR is one of the most important factors. It gives a first impression of the insurer’s reliability when it comes to claims. But is it the only factor that you should consider? How reliable is this metric when it comes to real life reliability? What are the other factors you should consider?

In this article, we will learn about what a claim settlement ratio is, how it’s calculated, the top 10 term insurance claim settlement ratios, and how to choose the best one. 

What is the Claim Settlement Ratio of Life Insurance?

It is a percentage of the total number of claims settled by the insurer in a year to the total number of claims available to settle.

CSR = (Total claims settled / Total claims available to settle) X 100

Where

‘Total Claims Settled’ includes partly and fully settled claims.

‘Total claims available to settle’ = (Claims carried forward from the previous year) + (New claims reported) - (Claims closed without payment + Claims still pending at year's end)

Interpretation:

    • 97% and above: Excellent
    • 90% to below 97%: Good
    • Below 90%: Avoid

Take a look at the infographic for more clarity.
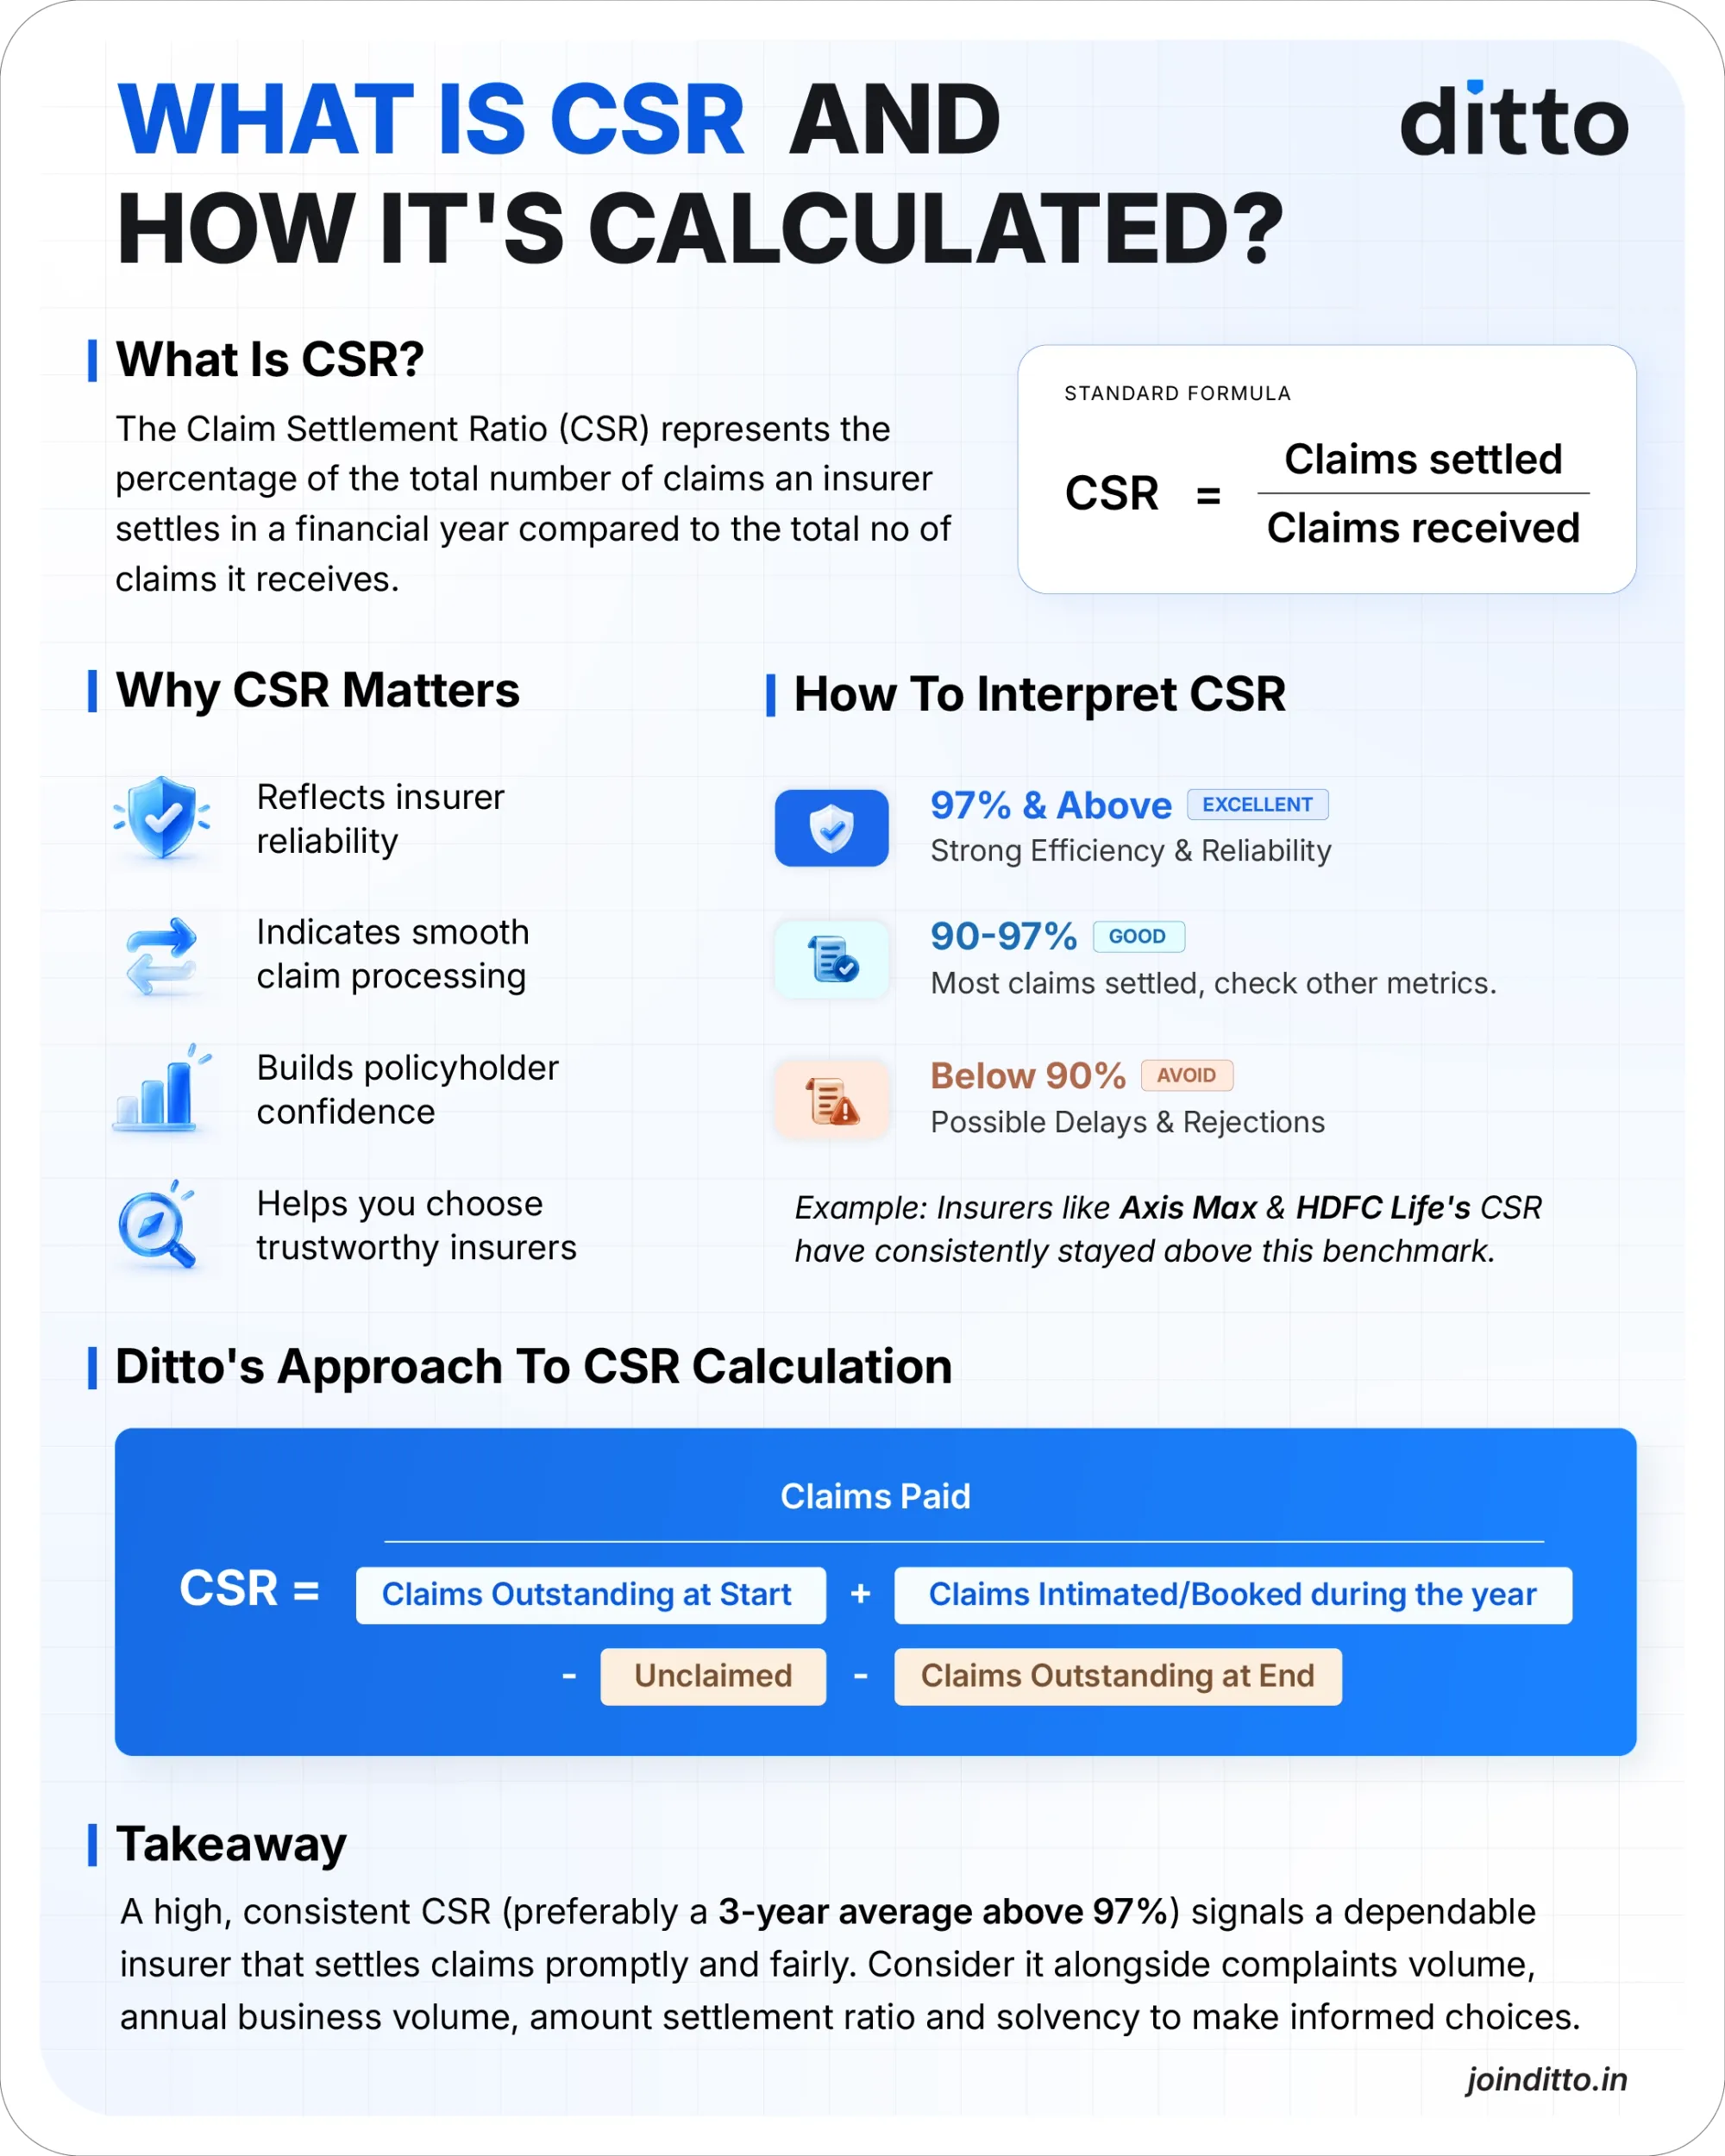
CSR measures claims settled versus received. Ditto uses a three-year average method and the CSR being 97% and above indicates a reliable insurer.

Talk to an expert
today and find
the right
insurance for you.
Ditto Advisor

Top 10 Life Insurance Companies in India by Claim Settlement Ratio

RankCompany NameCSR (FY 2023-24)CSR (FY 2024-25)CSR (FY 2025- 2026)Average (FY 2024-26)
1Axis Max Life Insurance99.65%99.70%99.78%99.71%
2HDFC Life Insurance99.54%99.71%99.72%99.66%
3PNB MetLife India Insurance99.20%99.57%99.81%99.53%
4Canara HSBC Life Insurance99.31%99.43%99.52%99.42%
5TATA AIA Life Insurance99.16%99.43%99.48%99.36%
6Bajaj Life Insurance99.26%99.32%99.38%99.32%
7Pramerica Life Insurance99.19%99.31%99.41%99.30%
8ICICI Prudential Life Insurance99.20%99.34%99.36%99.30%
9Edelweiss Life Insurance99.23%99.29%99.31%99.28%
10Bandhan Life Insurance99.66%99.73%98.15%99.18%

Note: The above figures have been sourced from public declarations from individual insurers under Form L-40.

If you want to explore insurer and IRDAI numbers in more detail, visit Ditto Data Lab. It brings together key term insurance data collected, verified, and carefully curated by our team over the years.

Why is The Claim Settlement Ratio Important?

    • Builds a Strong Reputation: CSR is not just a statistic. It plays a big role in how an insurer is perceived by customers. Since most buyers check CSR while comparing plans, a high CSR can significantly improve an insurer’s image. It signals that the company generally follows through on its promises, which makes it more attractive to new policyholders.
    • Gives You a Clear Picture: When choosing a term insurance provider, one of the most important things you want is confidence that your claim will be settled without hassle. This is where CSR helps. It gives you a quick snapshot of how dependable the insurer has been when it comes to settling claims.
    • Gives Peace of Mind to Policyholders: For someone buying insurance, a strong CSR instantly builds trust. It reassures them that the insurer has a proven history of paying claims, which can make an important and emotional financial decision feel far more secure.

How To Choose the Best Term Insurance Company in India?

While CSR is a key indicator of an insurer’s reliability, it should not be the only factor you consider. It is equally important to compare the policy’s amount settlement ratio, complaint figures, features, premiums, and overall customer service before making a final decision.

Other Factors to Consider

1) Complaint Volume: Look at complaints relative to claims received, not just the absolute number. When evaluating insurers, companies with fewer than 20 complaints per 10,000 claims are considered a strong indicator of smoother customer experience.

2) Amount Settlement Ratio: ASR shows how much money the insurer actually pays against the total claim amount filed. We consider 90% or above ideal, 80%–90% decent, and below 80% a concern.

3) Annual Business Income: Insurer scale can indicate an established customer base and operating track record. At Ditto, we use ₹5,000 crore or more in annual business income as a benchmark for insurers.

Here’s an infographic explaining it in detail:
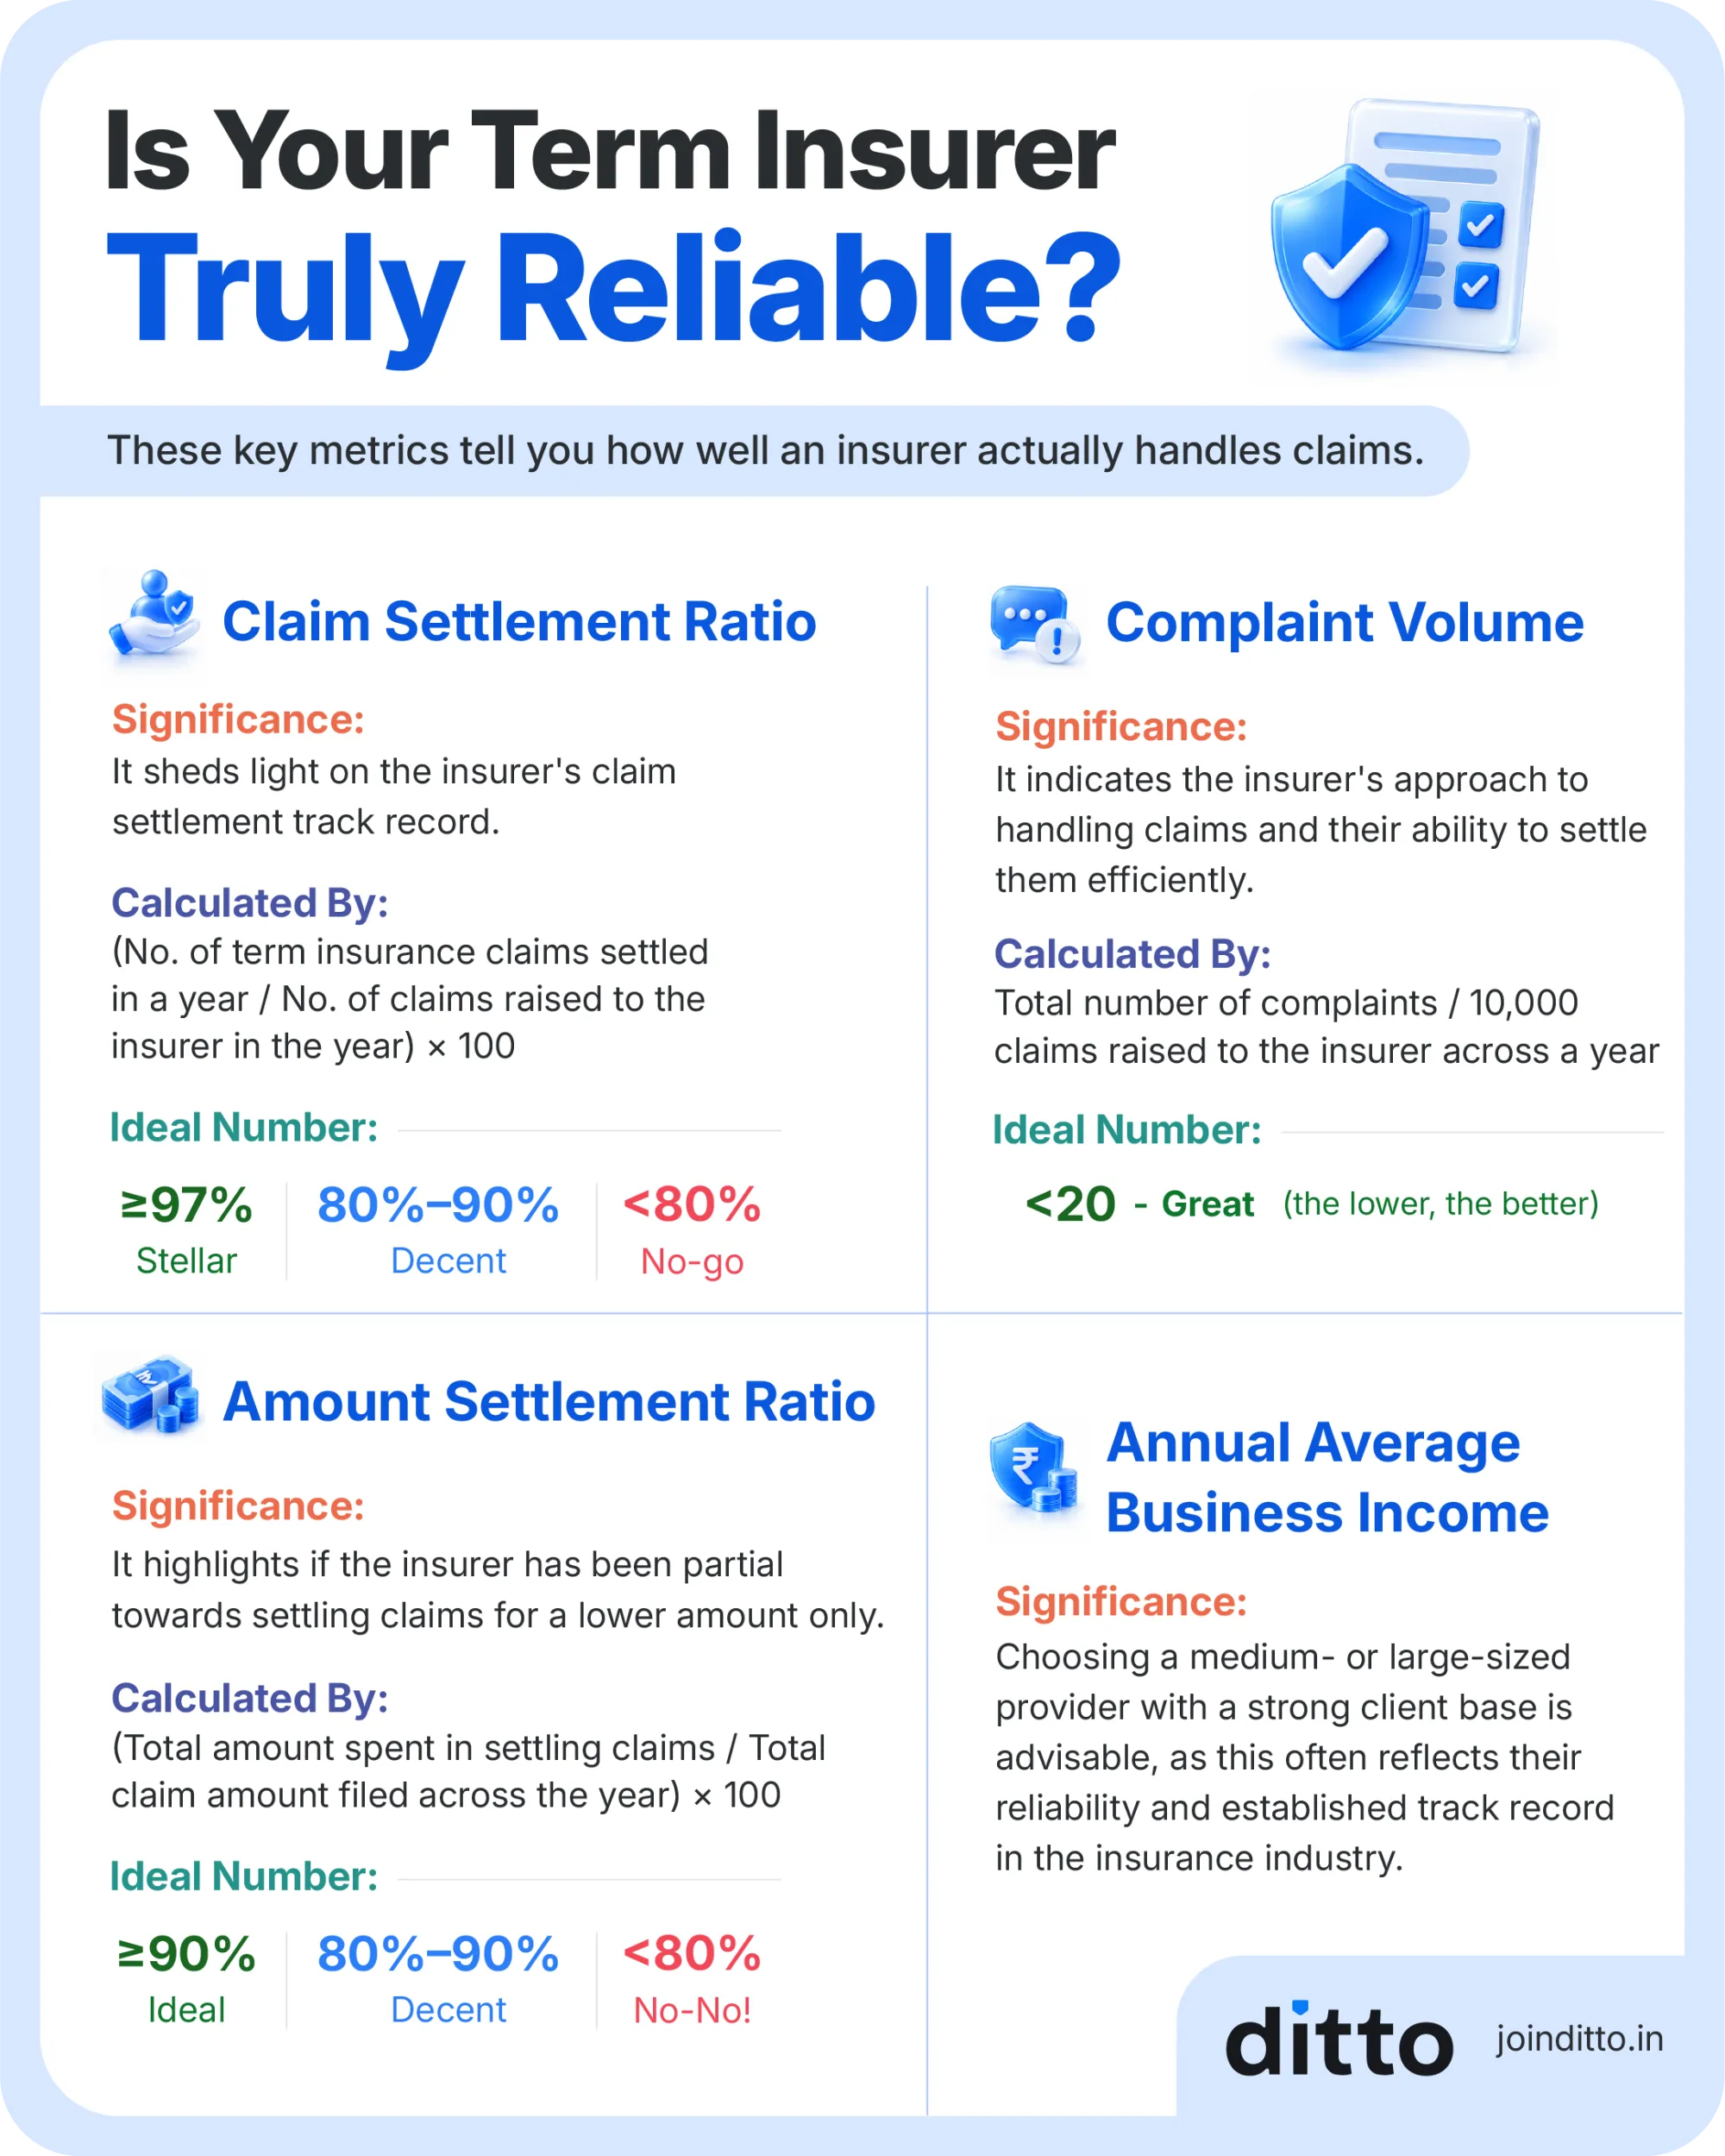
Term insurer reliability is assessed using claim settlement ratio, complaint volume, amount settlement ratio, and annual business income.

Why Choose Ditto for Life Insurance?

At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
Aaron Quadros LinkedIn Testimonial
    • 100% Free Consultation
    • No Spam. No Sales Pressure.
    • Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
    • Backed by Zerodha
    • Dedicated Claim Support Team
    • Compare Plans and Premiums with a Trusted Insurance Advisor

Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!

Conclusion

Selecting a term insurance company with a high claim settlement ratio is important to ensure your loved ones receive the promised benefits without hassle. While CSR is a key indicator of an insurer’s reliability, it shouldn’t be the only factor you look at. It’s just as important to compare policy Amount settlement ratio, Complaints figures, features, premiums, and customer service before making a final decision.

Always make sure to compare all the plan and insurer options, and read the terms of the plan carefully to make sure there are no surprises in the future.

Frequently Asked Questions

What is the claim settlement ratio in life insurance?

The claim settlement ratio is the percentage of death claims an insurer settles compared with the claims it receives during a specific period. For example, a 98% ratio means the insurer settled 98 out of every 100 claims received, subject to the reporting methodology. It helps assess claims experience but does not guarantee individual claim approval.

Which life insurers have the highest claim settlement ratio?

For the FY 2024–26 period, the top three life insurers by average claim settlement ratio are Axis Max Life Insurance at 99.71%, HDFC Life Insurance at 99.66%, and PNB MetLife Insurance at 99.53%. These figures reflect the average proportion of claims settled during the period and should be considered alongside other insurer evaluation metrics.

Why does Ditto use a three-year average claim settlement ratio?

At Ditto, we assess the top 10 life insurers using three-year average claim settlement ratios. This approach smooths out single-year anomalies and provides a more consistent view of an insurer's claims experience. However, the ratio is only one part of our evaluation and should be considered alongside insurer strength, complaints, and policy features.

Is a higher claim settlement ratio always better?

A higher claim settlement ratio indicates that an insurer settled a larger proportion of received claims. However, it does not automatically establish better service or financial strength. The ratio may not reflect claim amounts, settlement timelines, repudiations, or customer experience. Review multiple metrics and the insurer's policy terms before making a purchase decision.

What is the difference between claim settlement ratio and claim amount settlement ratio?

The claim settlement ratio measures the proportion of claims settled by count. The Amount Settlement Ratio (ASR) shows the proportion of the total claim amount an insurer paid, rather than simply measuring how many claims it settled. An insurer may have a high claim settlement ratio while handling some large claims differently. Reviewing both metrics offers a broader understanding of claims performance.

How long does it take to settle a term insurance claim?

Under IRDAI's 2024 policyholder protection framework, insurers must settle or repudiate a claim within 15 days of receiving all required documents if no investigation is needed. If an investigation is required, it must be completed within 45 days of claim intimation. Delays may attract interest at the bank rate plus 2%. A term insurance claim is a formal request by the nominee to receive the death benefit after the policyholder's death, provided the policy is active. The nominee must notify the insurer and submit documents such as the death certificate and bank details.

Can an insurer reject my death claim despite having a high claim settlement ratio?

Yes. A high claim settlement ratio does not guarantee approval of every claim. An insurer may reject a claim because of material misrepresentation, non-disclosure, exclusions, policy lapse, or other applicable policy conditions. Providing accurate information during the application and reviewing the policy terms can help reduce avoidable claim-related disputes.

What should I check besides the claim settlement ratio?

Besides the claim settlement ratio, review the claim amount settlement ratio, solvency ratio, complaint levels, financial strength, policy exclusions, and payout conditions. Consider whether the insurer offers suitable coverage and service support. A comprehensive evaluation helps you understand the insurer beyond a single percentage or ranking.

Last updated on: