Student health insurance in India protects students from unexpected medical expenses during their academic years, whether they are studying in India or abroad.
Types of Student Health Insurance
Domestic Plans: Students can stay covered under a parent’s family floater or buy an individual health insurance policy. College group plans may also provide basic coverage during the course.
Study-Abroad Plans: These are designed for students moving overseas and can cover medical emergencies, evacuation, repatriation, and other benefits required by universities or visa authorities.
Key Benefits
Cashless hospitalization at eligible network hospitals.
Coverage for hospitalization due to illnesses or accidents.
Restoration and bonus benefits in comprehensive retail plans.
Doctor consultations or consumables coverage in select plans or through add-ons.
Where to Buy
Ditto Insurance: Ditto helps students and parents compare health insurance plans, understand coverage gaps, choose suitable policies, and get support during purchase and claims.
If you’re a student and someone asks whether you have health insurance, you might say, “I think I’m covered under my parents’ policy.”
And you probably are. But for how long? Is the coverage enough? Will it still work if you move to another city for college? What if your university already provides its own insurance?
That’s where student health insurance can get a little confusing. In India, students can be covered in several ways, including a parent’s family floater, a college group policy, or an individual health plan. Students heading overseas have a different set of requirements altogether.
So before buying another policy, it helps to understand what cover you already have, where the gaps are, and when getting your own plan actually makes sense.
In this article, we will walk you through what student health insurance is, the best student health insurance plans in India, premiums, who should buy one and why, what it covers, and how to buy and claim.
Student health insurance is a health policy that covers medical expenses during your academic years, including hospitalizations and surgeries due to accidents or illnesses. The insurer pays the eligible bill, either directly to the hospital (cashless) or back to you (reimbursement), up to the sum insured you chose.
In India, "student health insurance" is not a separate product category defined by IRDAI with its own rules. It's a label for the different ways a student can be covered.
Family Floater Plan: The student is added to a parent's policy as a dependent.
Individual Plan: A health insurance plan bought in the student's own name.
College Plan: A group health insurance plan offered by the college or university, often bundled into fees.
International Plan: A study-abroad student plan designed to meet visa and university requirements overseas.
Best Student Health Insurance Plans in India [2026]
No plan is built only for students in India, so the best student health insurance plan is a regular health plan that suits a young, healthy buyer.
Optima Secure+ is our top pick for students. It combines comprehensive hospitalization cover with long-term flexibility at a young entry age. Adults can enter from age 18, and the base sum insured starts at ₹10 lakh.
HDFC ERGO Optima Secure+
4.6
Overall Rating
Insurer Rating
5.0/5
Feature Rating
4.6/5
Customer Service Rating
5.0/5
Premium Rating
3.0/5
Secure Benefit: Your base cover doubles from day one. Basically, a ₹10 lakh plan starts at ₹20 lakh.
Unlimited Restoration: Your cover is refilled up to 100% of the sum insured after every claim, no matter how many claims you make in a year.
Infinity Benefit: The sum insured increases by 100% each year with no upper cap, even if you claimed in the previous year.
No Restrictions: No room rent limits, no co-payment, and no disease-wise sub-limits.
Consumables Covered: The plan covers non-medical expenses such as gloves, masks, and syringes by default via the Protect Benefit.
Useful Add-Ons: Optima Wellbeing (doctor consultations and mental health counseling) and Limitless (one or two infinite value claims in the policy lifetime).
About the Insurer:HDFC ERGO reports one of the highest claim settlement ratios of 97.61% (3-year average, FY 2024 to FY 2026), has a network of 16,000+ hospitals, and records 8.87 complaints per 10,000 claims, well below the industry average.
Care Supreme is a good fit for students who want to customize their policy instead of settling for a one-size-fits-all plan. It offers a wide range of add-ons for benefits like consumables, health check-ups, wellness rewards, and higher bonus accumulation, while still remaining relatively affordable for younger buyers. Adults can enter from age 18, and the base sum insured starts at ₹5 lakh, subject to location-wise availability.
Care Supreme
4.5
Overall Rating
Insurer Rating
4.2/5
Feature Rating
4.5/5
Customer Service Rating
3.0/5
Premium Rating
5.0/5
No Restrictions: No room rent limits, no co-payment, and no disease-wise sub-limits.
Restoration: Unlimited restoration for related and unrelated claims up to 100% of the sum insured, by default.
Bonus: By default, cumulative bonus adds 50% of the sum insured each year up to 100% (irrespective of claims), with bonus extension up to 500% or unlimited accumulation through add-ons.
Fitness Discount: Based on the number of steps you take each month and year, Care offers wellness rewards with renewal discounts up to 30%.
About the Insurer:Care Health reports a 95.45% claim settlement ratio (3-year average, FY 2024 to FY 2026) and has 11,400+ network hospitals. However, its complaint volume is relatively high at 42.67 complaints per 10,000 claims, compared with the industry average of 29.35.
Activ Yuva is designed for students and young adults looking for comprehensive hospitalization coverage with wellness rewards. It combines strong coverage benefits with the flexibility to add OPD and maternity benefits as their needs change. Adults can enter from age 18, and the base sum insured starts at ₹5 lakh.
Aditya Birla Activ Yuva
4.4
Overall Rating
Insurer Rating
4.5/5
Feature Rating
4.3/5
Customer Service Rating
5.0/5
Premium Rating
5.0/5
No Restrictions: No room rent limits, no standard co-payment, and no disease-wise sub-limits under the base plan.
Yuva Reload: Doubles the base cover from day 1 and provides unlimited restoration of up to 100% of the base sum insured for related or unrelated illnesses.
Yuva Credit: Adds 100% of the base sum insured at every continuous renewal, up to 1,000%, regardless of claims. This means a ₹10 lakh base cover can grow to ₹1.1 crore after 10 renewals.
HealthReturns: Rewards healthy habits, including physical activity, nutrition, and sleep tracking, with rewards worth up to 100% of the eligible premium, subject to program conditions.
Consumables Covered: The built-in Claim Protect benefit covers specified non-medical expenses, such as gloves, masks, and syringes.
Useful Add-Ons: Optional OPD coverage, worldwide maternity benefits, and a reduced pre-existing disease waiting period from 2 years to 1 year.
About the Insurer:Aditya Birla Health reports a 96.25% claim settlement ratio (3-year average, FY 2024 to FY 2026), has a network of 16,500+ hospitals, and records 18.67 complaints per 10,000 claims, lower than the industry average.
Niva Bupa ReAssure 3.0 Black is the most comprehensive variant in the ReAssure 3.0 lineup, offering extensive hospitalization coverage and long-term benefits. Adults can enter from age 18, with sum insured options of ₹5 lakh, ₹10 lakh, and unlimited coverage.
Niva Bupa ReAssure 3.0 Black
4.1
Overall Rating
Insurer Rating
4.2/5
Feature Rating
4.4/5
Customer Service Rating
3.0/5
Premium Rating
3.0/5
No Restrictions: No room rent restrictions or disease-wise sub-limits, and no mandatory co-payment.
ReAssure Forever: For ₹5 lakh and ₹10 lakh cover options, the first paid claim activates unlimited restoration for subsequent claims, up to the base sum insured per claim, for the same or different illnesses.
Lock the Clock: Keeps premiums linked to your entry age until the first paid claim. However, insurer-wide repricing and medical inflation can still increase premiums.
Booster+: Carries forward unused base cover up to 10 times the original sum insured.
Consumables: The optional Claim Safeguard+ add-on covers non-payable items across Lists I, II, III, and IV.
Flexible Waiting Periods: The standard 3-year pre-existing disease waiting period can be reduced to 1 or 2 years through optional benefits. Day 1 coverage is also available for approved pre-existing conditions at an additional premium.
Children: Dependent children can enter a family floater up to age 30, with no fixed exit age on renewal, making it useful for students pursuing higher education.
About the Insurer:Niva Bupa reports a 92.92% claim settlement ratio (3-year average, FY 2024 to FY 2026) and has 10,000+ network hospitals. Its complaint volume is 37.13 complaints per 10,000 claims, above the industry average.
SBI Super Health Platinum Infinite is a good fit for students who want a feature-rich plan with several built-in benefits, instead of relying heavily on add-ons. It combines high coverage with OPD benefits, consumables cover, strong restoration, and relatively shorter waiting periods. Adults can enter from age 18, and the base sum insured starts at ₹50 lakh.
SBI Super Health Platinum Infinite
4.1
Overall Rating
Insurer Rating
3.8/5
Feature Rating
4.2/5
Customer Service Rating
3.0/5
Premium Rating
5.0/5
Restoration: Unlimited reinstatement of the sum insured, with up to 200% of the base cover available per claim.
OPD (Outpatient Department) Cover: Includes built-in OPD benefits, which can help cover eligible expenses beyond hospitalization.
Consumables Covered: Non-medical expenses such as gloves, masks, and syringes are covered by default.
Shorter Waiting Periods: A 1-year waiting period applies to specified illnesses, while pre-existing diseases have a 2-year waiting period.
Health Multiplier: Provides up to 3x the base sum insured once a year for listed critical illnesses.
About the Insurer: SBI General reports a 95.94% claim settlement ratio (3-year average, FY 2024 to FY 2026), has a network of 18,000+ hospitals, and records 14.04 complaints per 10,000 claims, comfortably below the industry average.
Note: If you'd like to explore the detailed figures reported by insurers and the IRDAI in their annual disclosures and public reports, visit Ditto Data Labs, our proprietary repository of health insurance data, meticulously compiled, verified, and maintained by our team over the years.
Student Health Insurance Plans for Studying Abroad
If you're moving overseas, you need cover that your university and visa authority will accept. Plans like HDFC ERGO Student Suraksha and Tata AIG Student Travel are designed for students studying abroad. They protect against medical emergencies, travel risks, and university-related requirements.
At Ditto, we often suggest a combined approach. An Indian health plan keeps you covered for treatment back home, and a separate plan from the country of study covers emergencies there. Before you buy anything, confirm the exact requirements with your university and check them against the visa guidelines.
Student Health Insurance Sample Premiums: How Much Does It Cost?
Here is an indicative premium for a ₹15 lakh sum insured for someone living in Delhi (110010), with recommended add-ons. Your actual premium may vary based on your age, location, medical history, underwriting, and add-on selection.
Plan
18 Years
20 Years
25 Years
HDFC ERGO Optima Secure+
₹12,353
₹12,669
₹13,459
Care Supreme
₹15,814
₹15,814
₹15,814
Aditya Birla Activ Yuva
₹11,597
₹11,597
₹11,597
What Decides Your Premium?
Age
Students are young and healthy, so premiums are relatively low.
City
Insurers price by zone, so your location changes the quote.
Sum Insured
A higher cover costs more, but only marginally.
Medical History and Lifestyle
Pre-existing conditions and medical history affect the premium based on severity.
Did You Know?
If your parents pay your health insurance premium, they can claim a tax deduction under Section 80D of the Income Tax Act (now Section 126), up to ₹25,000 a year for eligible family members, under the old tax regime.
Who Should Buy Student Health Insurance and Why?
Whether you should buy student health insurance or not depends on where you study and your financial dependency, not necessarily on the type of course. Here's a quick guide.
Your Situation
Recommended Coverage Route
What to Check?
Studying in India, dependent on parents
Parent's family floater
Dependent exit age and shared sum insured
Studying in India, living independently (working, freelancing, PhD, married)
Individual plan
Waiting periods and policy features (no room rent limits, co-payment or disease-wise sub-limits)
Studying abroad
University plan or overseas student plan, plus an Indian plan
Visa and university acceptance
Did You Know?
According to the Ministry of External Affairs, nearly 18.8 lakh Indian students were studying abroad across 153 countries, including about 12.5 lakh in universities and higher education institutions. That is a lot of families who need to get their student coverage right.
Why Should Students Buy Health Insurance?
01
Medical Emergencies Are Expensive
A plan covers emergency treatment and protects your family from sudden bills.
02
Student Life Is Active
Daily commutes, two-wheelers, sports, and outdoor trips raise the chance of accidents.
03
Continuity Benefits
Early cover helps preserve waiting period credits and accumulate bonuses, and it makes moving from a family floater to an individual policy smoother.
04
Mental Health Support
Academic pressure and social stress can affect well-being. Health plans cover mental illness hospitalization, though coverage for therapy sessions and psychologist visits varies by plan.
05
Valuable Abroad
International student plans can cover hospitalization, emergency treatment, study interruption, and sponsor protection.
06
Academic Continuity
A serious illness can disrupt studies and add costs for tuition, travel, or recovery.
Are College Health Insurance Plans Enough?
Many college health insurance policies look adequate based on the sum insured, but the fine print can change how much you are actually covered for.
Take the Indian Institute of Management Calcutta, for example.
As per the 2025-26 MBA student insurance structure, students get a medical cover of ₹3 lakh. However, normal room charges are capped at ₹6,000 per day, and ICU single-bed charges are limited to ₹12,000 per day.
At first glance, these limits seem reasonable. But in metro cities, many private hospitals charge much more for a room. Once you choose a room above the allowed limit, insurers apply proportionate deductions. So even if the total bill stays within ₹3 lakh, your family may still end up paying big out-of-pocket expenses. This is why, at Ditto, we treat university insurance as a support layer, not complete protection.
What Does Student Health Insurance Typically Cover?
A good student plan covers the major things that can derail a family's finances. Exact benefits vary by plan, so always read the policy wording, but here's what to expect.
What Is Usually Covered
Hospitalization: Room rent, ICU, doctor and surgeon fees, medicines, and tests during your stay.
Pre- and Post-Hospitalization Costs: Tests and medicines before and after admission, ideally 60 days before admission and 180 days after discharge.
Day-Care Procedures: Treatments needing less than 24 hours in hospital, like dialysis or minor surgeries.
Accidents: Hospitalization after an accident is covered from day 1.
Benefits That Make a Real Difference
Restoration Benefit: If you make a large claim and use up your cover, restoration can refill it for another hospitalization in the same year. This is especially useful if you are on a family floater where the sum insured is shared with your parents or siblings.
Bonus: Buying health insurance early can help your cover grow over time. If you go several years without making a claim, some plans can increase your available sum insured without requiring you to buy a much larger base cover upfront.
Consumables Cover: Hospital bills often include non-medical items such as gloves, masks, syringes, and other consumables that standard policies may not pay for. This benefit can reduce what you or your parents have to pay out of pocket after a claim.
Annual Health Check-Up: Students rarely think about preventive healthcare, but regular check-ups can help spot issues early. Some plans include these check-ups or let you add them without paying each time separately.
What Is Usually Not Covered
Waiting Periods: Some conditions are not covered immediately after you buy the policy. There is typically a 30-day initial waiting period for illnesses, while specific illnesses (usually 2 years) and pre-existing diseases can have longer waiting periods (maximum 3 years).
OPD Expenses: Standard hospitalization policies usually don't cover routine doctor consultations, medicines, or standalone diagnostic tests unless the plan includes OPD benefits or you purchase an add-on.
Professional Adventure Sports: Treatment arising from participation as a professional in hazardous or adventure sports can be excluded. So if you participate in such activities professionally, check the policy wording carefully.
Permanent Exclusions: Unlike a waiting period, which eventually ends, a permanent exclusion remains outside the policy for its entire term. Common standard exclusions can include expenses related to substance abuse, treatments undertaken purely for cosmetic purposes, infertility or sterilization, and certain other treatments specified in the policy.
What Is a Student Health Card?
Many students search for a "student health card" and wonder if it's a separate document they need to apply for. It isn't. IRDAI doesn't issue a special student health card for private insurance. Instead, the phrase can usually mean one of these:
Your insurer's e-health card, which shows your policy number and member details. You show it at the hospital's insurance desk to get cashless treatment.
A college or university health ID issued by your institution if it runs a campus clinic or offers a group plan.
Your ABHA health ID, which is a digital health record number under the Ayushman Bharat Digital Mission. It stores health records, but it is not an insurance policy.
In an emergency, the insurer's e-health card matters. Download it as soon as your policy is issued and save it on your phone
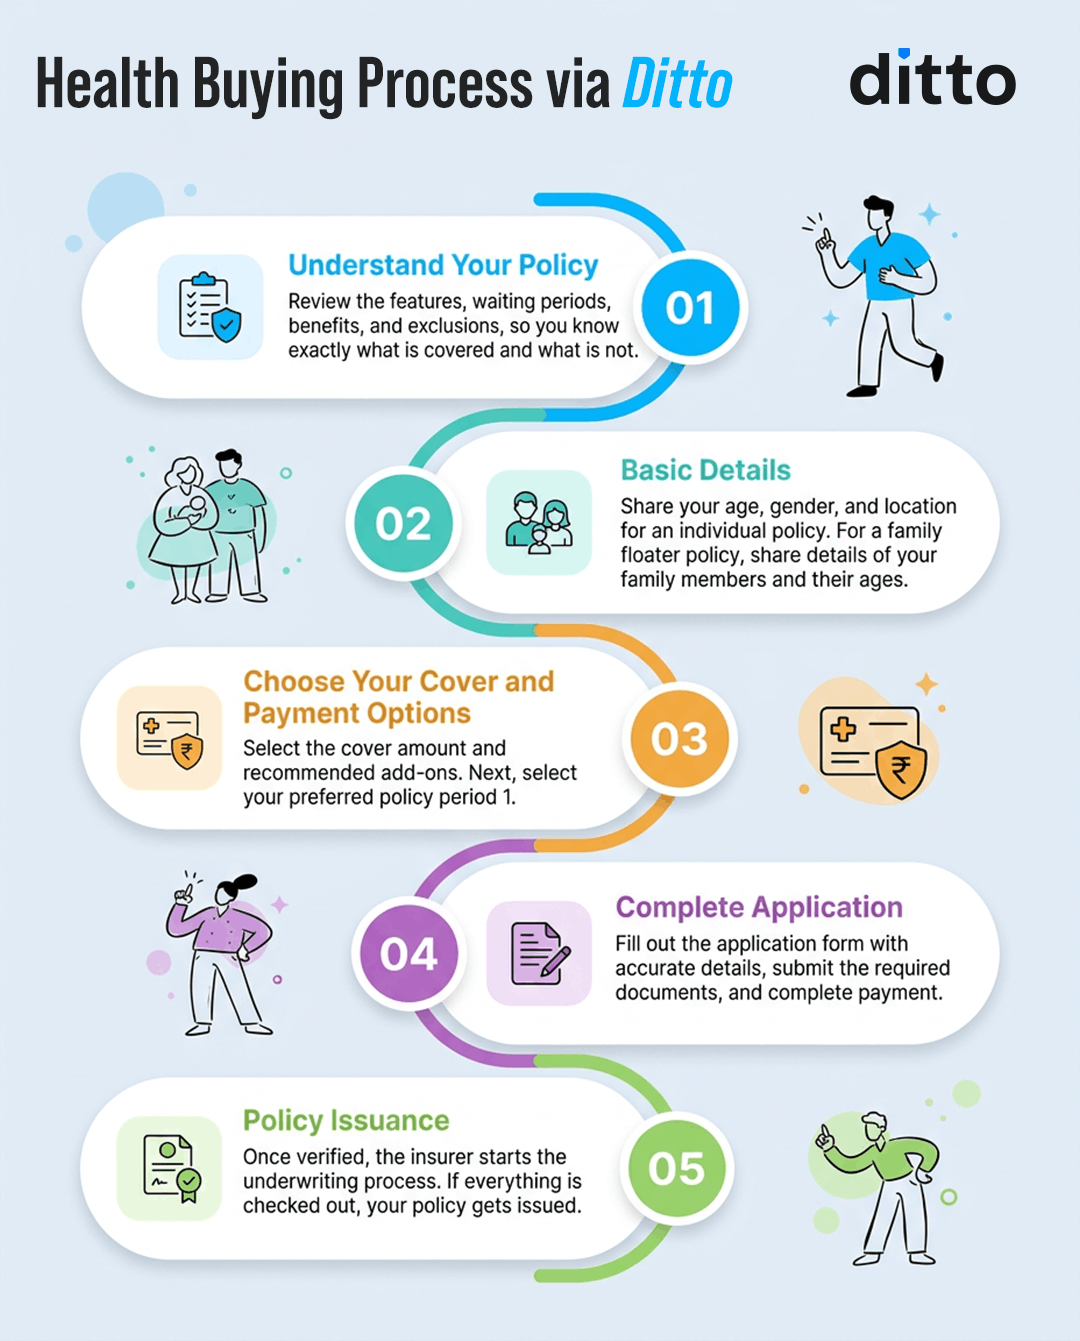
How to Buy the Best Student Health Insurance Plan?
01
Decide the Type of Cover
Are you staying on the family floater, buying your first individual plan, or going abroad? Use the table earlier in this guide.
02
Check Eligibility
Adults can buy in their own name from age 18 on many plans. Children are usually covered as dependents on a parent's policy until age 25 or 26.
03
Shortlist Plans
Use the checklist below to compare two or three options. Our Compare Health Policies tool can help.
04
Choose Your Sum Insured and Add-Ons
For most students, starting with at least ₹15 lakh to ₹25 lakh of cover is a sensible benchmark. Then add only the benefits you are likely to use, such as consumables cover, OPD benefits, or stronger bonus and restoration features, instead of paying for every available add-on.
05
Fill the Proposal Honestly
Share your full medical history, as non-disclosure can lead to claim rejection.
06
Complete KYC and Pay Online
Keep ID proof, address proof, and date-of-birth proof handy. The exact list depends on the insurer.
07
Download Your Policy
Save the policy PDF and the e-health card on your phone, and share them with a parent.
How Ditto Helps You Buy
At Ditto, we help students and parents choose the online student health insurance plan based on budget, medical needs, and study location. Our team supports you through documentation, underwriting, policy purchase, and claims assistance, making the process simpler and less stressful.
How to Claim Student Health Insurance Benefits?
You can claim in two ways, and it helps to know both before an emergency.
Cashless Claim
Use this at a network hospital. The insurer settles the eligible bill directly with the hospital.
Go to a network hospital and inform the insurer or its TPA (the third-party administrator that processes claims), ideally within 24 hours for emergency hospitalization and 48-72 hours before admission for planned treatment.
Show your student health card (the insurer's e-health card) and a valid government photo ID at the hospital's insurance desk.
The hospital sends a pre-authorization request to the insurer.
The insurer approves the eligible amount.
Pay only non-payable items, if any, and get discharged.
Reimbursement Claim
Use this at a non-network hospital, or if cashless is declined. You pay first and get reimbursed later.
Inform your insurer before admission or within 24 hours of being hospitalized.
Pay the bills and collect all original documents.
Fill out the claim form and attach documents such as the discharge summary, itemized bills, and test reports.
Submit online or at a branch, and track your claim status.
If you bought your plan through us, our claims team can help: call 080-48816818 or write to claims@joinditto.in.
What Is the Ideal Sum Insured for Student Health Insurance?
No single number fits everyone, but here's a way to think about it.
Start with the plan, not just the amount. A ₹3 lakh college cover with a ₹6,000 per-day room cap can leave you paying a large share of a metro hospital bill. A ₹10 lakh individual plan with no room rent limit can go much further. Features like restoration and bonus also stretch your cover.
As a practical starting point, most plans we shortlist for students begin at a ₹10 lakh base cover. Your ideal number depends on:
Where You Study: Metro hospitals cost more than those in smaller cities.
Whether You Share a Floater: On a floater, one sum insured is shared by every member. A large claim by a parent can leave less for you.
Plan Features: Restoration, no-claim bonus, no room rent limit, and consumables cover all make the same number work harder.
Your Health Profile: Pre-existing conditions or an active sports life may justify more cover.
Your Budget: Compare exact quotes at two or three cover levels before you decide.
Cover can usually be increased at renewal, subject to the insurer's underwriting, so a flexible plan is better than a rigid one.
How Long Does Student Health Insurance Coverage Last?
It depends on the type of cover.
Individual Plan: It runs for the policy term you choose, usually one year, though many insurers also offer 2- to 5-year terms with a discount. IRDAI requires health policies to be renewable for life, so you can keep the plan long after graduation.
Family Floater: The student stays covered as a dependent until the insurer's exit age. Most family floater plans allow dependent children to remain covered until age 25.
College or University Group Plan: It generally lasts for the course period. Once you graduate, the cover usually ends. Ask whether you can move to an individual policy, and check our guide on portability.
Study-Abroad Plan: It's usually bought for a fixed period that matches your course and visa. Check whether it can be extended if your program runs longer.
Plan the switch early. Under IRDAI rules, students who apply at least 30 days before the renewal date on which they age out can move to an individual plan while keeping continuity benefits such as waiting period credits. At Ditto, we recommend starting this process well before the exit age to avoid gaps.
Student Health Insurance vs. Regular Health Insurance: What's the Difference?
Here's the simple answer. In India, a student plan is usually a regular health plan that is bought for or by a student. The real differences come from the type of cover you choose.
Feature
Regular Individual or Family Floater Plan
College or University Group Plan
Study-Abroad Student Plan
Who It Suits
Any adult, or a dependent child on a parent's plan
Enrolled students of that institution
Students studying overseas
Where It Provides Coverage
India
India
The country of study, sometimes worldwide
How Long It Lasts
Renewable for life
Usually the course period
A fixed period matched to the course
Room Rent and Limits
Choose plans with no limits
Often capped, as in the IIM Calcutta example
Depends on the plan
Extras
Restoration, bonus, add-ons
Basic cover
Emergency evacuation, study interruption, sponsor protection
Continuity
Builds long-term benefits
Usually ends with the course
Ends with the course
Takeaway: A regular plan offers the longest-lasting, most portable protection, while group and overseas plans address short-term or location-specific needs. Many students do best with a mix of both.
Why Choose Ditto for Health Insurance?
At Ditto, we’ve assisted over 12,00,000 customers choose the right insurance policy. Why customers like Pallavi love us:
100% Free Consultation
No Spam. No Sales Pressure.
Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
Backed by Zerodha
Dedicated Claim Support Team
Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Ditto's Take on Student Health Insurance in India
Student health insurance is a financial safety net that protects students and their families' savings from unexpected healthcare costs.
Here's how we suggest you move ahead:
Start With Your Situation
If you're dependent on your parents, check your family floater's sum insured, room rent terms, and the age limit for coverage. If it's small or restrictive, consider your own plan.
Start Early if You Have No Cover
If you don't have any health coverage, buy an individual plan at a young age. This keeps costs lower and builds continuity benefits that become more valuable over time.
Treat University Plans as Temporary Support
They often come with room rent restrictions, less flexibility, and limited benefits. They work best as a short-term layer, not long-term protection.
Compare Carefully if You’re Going Abroad
Compare your university's student health insurance plan with Indian overseas student plans. The policy should comply with visa rules and be accepted locally.
At Ditto, we believe student health insurance should be treated as an early financial planning decision, not just a college requirement. A well-chosen plan protects savings, builds long-term continuity, and gives both students and parents greater confidence during important academic years.
Full Disclosure
This article is purely for informational purposes and offers an unbiased review of health insurance plans from both our partner and non-partner insurers. We sourced the information from IRDAI reports, insurer websites, policy documents, and other publicly available data. To understand how our experts evaluate and shortlist health insurance plans, explore Ditto's Cut.
Frequently Asked Questions
Is a standalone student health insurance plan necessary if my child is on my family floater?
Not necessarily. If your child is financially dependent and your family floater has adequate coverage, no room rent restrictions, and enough sum insured to share across members, staying on it can work well. A separate individual policy becomes more useful if the floater is small, heavily shared, restrictive, or your child is approaching the dependent exit age. It can also help them start building continuity benefits on a policy they can keep long term.
Does student health insurance in India cover accidents during school sports?
Usually, yes. If a student is hospitalized after an accidental injury during regular school or college sports, a standard health insurance policy generally covers the treatment. Accidental hospitalizations are also exempt from the usual 30-day initial waiting period. However, treatment linked to professional participation in hazardous or adventure sports may be excluded. It is still worth checking the exact policy wording and whether the school or college provides additional group accident cover.
Can a college student in India buy an individual health insurance policy at 18?
Yes. Once a student turns 18, they can buy an individual health insurance policy in their own name, subject to the insurer’s eligibility and underwriting rules. This can make sense if they are no longer adequately covered under their parents’ floater or want a policy they can continue after college. If they remain financially dependent and the family cover is strong enough, though, buying a separate policy immediately may not be necessary.
What is the difference between student health insurance in India and study-abroad student insurance?
For students in India, “student health insurance” usually means a regular individual policy, a parent’s family floater, or a college group plan. Study-abroad insurance is different. It is designed around the requirements of the country, university, and visa, and can include benefits such as emergency evacuation, study interruption, and sponsor protection. Students going overseas may need both: an Indian health policy for treatment back home and an overseas plan accepted in their country of study.
Do Indian schools or colleges mandate health insurance for admission?
No single national rule requires every Indian school or college student to buy health insurance for admission. Some institutions, however, provide a group health policy and include its cost in the student fee structure. So before buying anything separately, check what your institution already offers and review the sum insured, room rent limits, exclusions, and cover duration. Students going abroad should separately check their university and visa requirements, since health cover may be mandatory there.
Does student health insurance cover OPD consultations and diagnostic tests?
Not always. Most standard health insurance plans focus primarily on hospitalization, so routine doctor visits, medicines, and standalone diagnostic tests are often excluded. However, some plans include OPD benefits by default, while others offer them through an add-on. Tests and medicines linked to an eligible hospitalization may also be covered under pre- and post-hospitalization benefits. So if regular consultations matter to you, specifically check the OPD limits and conditions before choosing a plan.
Should I add my child to a family floater instead of buying a separate student policy?
For a financially dependent student, a family floater is often the simpler starting point. But check how much cover is actually available because the sum insured is shared among all family members. If one parent makes a large claim, less cover may remain for the child. A separate individual plan can make more sense if the family cover is inadequate, the student is nearing the dependent exit age, or you want them to build long-term continuity on their own policy.
Customer Reviews
4.9
20915 reviews
Ditto is doing really great. Absolutely spam free- that's the best part. They don't talk to you like they are forced to sell the product. It's more like, helping us buy better. Advisor Nuha was very patient and answered all my questions with clarity. Thanks for the service
I
INDHUMATHI M
Loved the service! Maheta Nidhi Hitesh was incredibly helpful and knowledgeable. She guided me through the whole process and made everything super easy to understand. I really appreciated how patient she was with all my questions—there was no pressure at all, just clear and honest advice. Honestly, I'm very happy with my experience at Ditto so far. Highly recommend!
RK
Ragul Kumar
I had a great experience with Ditto while exploring health insurance options. The process was smooth and everything was explained clearly.
A special thanks to Swaroop SK for patiently answering all my questions and guiding me through the policy details without any pressure. The transparency and support made it much easier to understand and choose the right plan.
Really appreciate the assistance!
PS
Pulkit Singh
Had a great experience with Ditto Insurance. Ishita Sudrania was extremely helpful in guiding me through choosing the right term plan. There was no spamming or sales pressure, and all my questions were patiently answered. She also assisted me thoroughly with the entire application process. Highly recommend!
SS
Samil Shah
I had a great experience with Ditto while filing my health insurance claim. Their team guided me clearly through the entire process, helped with the required documents, and promptly answered all my queries. Their support made the claim process much smoother and less stressful. Highly appreciate their assistance.