

Overview
What does ₹10 lakh of health insurance actually get you?
With a regular health insurance policy, it can help pay your hospital bills. With a critical illness plan, you could receive a lump sum if you're diagnosed with a specified illness.
So, two policies offering the same ₹10 lakh cover can work very differently. And unless you understand these differences, you might end up buying a policy that doesn't provide the protection you actually need.
That's why understanding the different types of health insurance plans in India matters. In this guide, we'll break down how each type works, who it's best suited for, and how to choose the right coverage without paying for benefits you don't need.
Types of Health Insurance Plans in India
IRDAI classifies types of health insurance policies into two major categories:
Indemnity-Based Health Insurance Plans
Indemnity plans reimburse eligible medical expenses, including hospitalization, surgery, diagnostic tests, and consultations related to covered treatment. Routine Outpatient Department (OPD) consultations are covered only when the policy specifically includes them.
Individual Health Insurance
- An individual health insurance policy covers one person with a dedicated SI.
- Claims don't affect other family members' coverage under separate policies, making this plan suitable for individuals who want independent coverage.
- Plan Examples: HDFC ERGO Optima Secure+ and Care Supreme.
Multi-Individual Health Insurance
- A multi-individual plan covers multiple family members under one policy document with a common renewal date and proposer.
- Each member has a separate SI, so one person's claim does not reduce another member's coverage. You manage one policy, but each member gets a separate coverage limit.
- Plan Example: Niva Bupa ReAssure 2.0 Platinum+ covers up to 6 members, including self, spouse, dependent children up to 30 years, parents, and parents-in-law.
Family Floater Health Insurance
- A family floater covers multiple family members, typically a spouse and dependent children, under one shared SI.
- Any covered member can use this common pool during the policy year.
- These plans are often more affordable for young, healthy families than separate individual policies.
- Plan Examples: Care Supreme covers up to 2 adults and 2 children, while Aditya Birla Activ One MAX covers up to 2 adults and 4 children.
Ditto’s Take
Benefit-Based Health Insurance Plans
Unlike indemnity plans, which cover eligible medical expenses, benefit-based plans pay a fixed amount when a covered event or diagnosis occurs. Payouts are independent of actual medical costs.
Critical Illness Insurance
Critical illness insurance pays a lump sum when you are diagnosed with a covered condition, such as cancer, stroke, a heart attack, or organ failure. You can use the payout for treatment, debt repayment, or household expenses while you recover. The policy may terminate after the payout, depending on its terms.
Plan Examples:
- HDFC ERGO Critical Illness Platinum covers 15 specified critical illnesses, with a SI range of ₹1 lakh to ₹50 lakh, subject to a 90-day waiting period and a 15- to 30-day survival period option.
- Bajaj General Critical Illness Insurance provides a lump-sum payout for 12 covered critical illnesses, with a SI of ₹1 lakh to ₹50 lakh, subject to age-based limits, a 90-day waiting period, and a 30-day survival period.
Personal Accident Insurance
Personal accident insurance provides financial support after a covered accident. Depending on the policy, benefits may include lump-sum payouts for accidental death or permanent disability, as well as payments for temporary disability. This cover can help replace lost income and support dependents if an accident affects your ability to work.
Plan Examples:
- Niva Bupa Personal Accident Insurance pays 100% of the SI for accidental death within 365 days, up to 100% for Permanent Total Disability (PTD). Permanent Partial Disability (PPD) benefits vary by injury, such as 70% for an arm or leg, 50% for an eye, 20% for a thumb, and 5% for a toe. Additional benefits include child education assistance and accidental medical expenses, subject to policy terms.
- ICICI Lombard Personal Protect Plan pays 100% of the SI for accidental death and a lump sum for permanent disability that prevents the insured from working. It offers worldwide, 24/7 protection, flexible coverage based on annual income, and optional hospital daily allowance and medical expense reimbursement, subject to policy terms.
Hospital Cash Plans
Hospital cash plans pay a fixed daily allowance for eligible inpatient hospitalization, regardless of the actual hospital bill. You can use this money for food, travel, and other incidental expenses. These plans are available as standalone policies or as add-on riders to a health insurance policy.
Plan Example: Star Hospital Cash Insurance offers daily cash benefits of ₹1,000 to ₹3,000 per day under the Basic Plan and ₹3,000 to ₹5,000 per day under the Enhanced Plan, subject to policy terms.
Talk to an expert
today and
find
the right
insurance for you.
Types of Health Insurance Plans Based on Specific Life Stages and Needs
Senior Citizen Health Insurance
Senior citizen plans are designed for adults aged 60 and above. They may cover age-related conditions but often include co-payments, room-rent limits, or disease-specific sub-limits.
Plan Examples:
- Care Senior Health Advantage is designed for adults aged 60+, with hospitalization coverage and ₹5 lakh or ₹10 lakh SI options. It has a 2-year pre-existing disease waiting period and comes with a 50% co-payment (60% after age 70), twin-sharing room limits, and an ICU limit of 2% of SI per day.
- Niva Bupa Senior First is available in Gold and Platinum variants. This plan has a default 50% co-payment on admissible claims. Buyers can select lower co-payment options for an additional premium, or choose an eligible annual aggregate deductible instead.
Note: Apply for a comprehensive senior citizen health insurance plan first, even if you're over 60. If insurers decline your application or offer unsuitable terms, consider senior-specific plans. Always compare their co-payments, waiting periods, and coverage limits before choosing one.
Maternity Health Insurance
Maternity coverage helps pay for pregnancy-related expenses, including delivery and, depending on the policy, prenatal care, postnatal care, and newborn benefits. Many plans have 9-month to 4-year waiting periods and caps on delivery expenses.
Plan Examples:
- Niva Bupa Aspire offers maternity coverage through its M-iracle benefit, including delivery, assisted reproduction, surrogacy, adoption, and newborn coverage, subject to variant-specific limits and waiting periods.
- Aditya Birla Activ Yuva offers optional maternity coverage with limits of ₹1 lakh, ₹1.5 lakh, or ₹2 lakh and waiting periods of 1,2, or 3 years. It also covers newborn hospitalization from day 1, provided the maternity claim is approved.
Our Take
Top-Up and Super Top-Up Health Insurance
Top-up and super top-up plans increase your health coverage at a lower premium than buying an equivalent amount of base cover. Both have a deductible, which is the amount you must pay before the plan starts covering eligible expenses.
The key difference is how the deductible is calculated. A top-up plan applies it to each individual claim, while a super top-up plan considers eligible claims cumulatively over the policy year. As a result, a super top-up can cover multiple hospitalizations that together exceed the deductible, making it a practical way to increase your overall health cover.
Plan Examples:
- HDFC ERGO my Medisure Super Top-Up offers ₹5 lakh to ₹20 lakh in additional coverage, with aggregate deductible options of ₹4 lakh to ₹5 lakh. It covers eligible hospitalization expenses once cumulative claims exceed the deductible during the policy year.
- Care Supreme Enhance offers coverage up to ₹1 crore, with aggregate annual deductible options ranging from ₹3 lakh to ₹15 lakh.
Group Health Insurance
Group health insurance covers employees or organization members under a master policy. Employer plans may include maternity benefits and reduced or waived waiting periods for pre-existing conditions, depending on the policy.
Plan Example: ICICI Lombard Health Shield 360 is a group health insurance plan available to eligible ICICI Bank customers and account holders of its subsidiaries.
Note: Group cover can be useful, but it usually ends when you leave your employer, and you have limited control over benefit changes at renewal. Consider maintaining a private health insurance policy alongside it.
Which Type of Plan Should You Choose?
When Should You Consider Benefit-Based Plans?
Benefit-based plans can provide additional financial support for specific needs, such as income loss during a serious illness, accidental disability, or incidental hospitalization expenses. However, they should support comprehensive health insurance, not replace it.
Common Mistakes to Avoid While Choosing Among the Types of Health Insurance Plans
Hiding Pre-Existing Conditions
Ignoring Room-Rent Limits and Sub-Limits
Overlooking Specific Illness Waiting Periods
Assuming Maternity Cover Includes Newborns
Ignoring Dependent Eligibility Rules
Why Choose Ditto for Health Insurance?
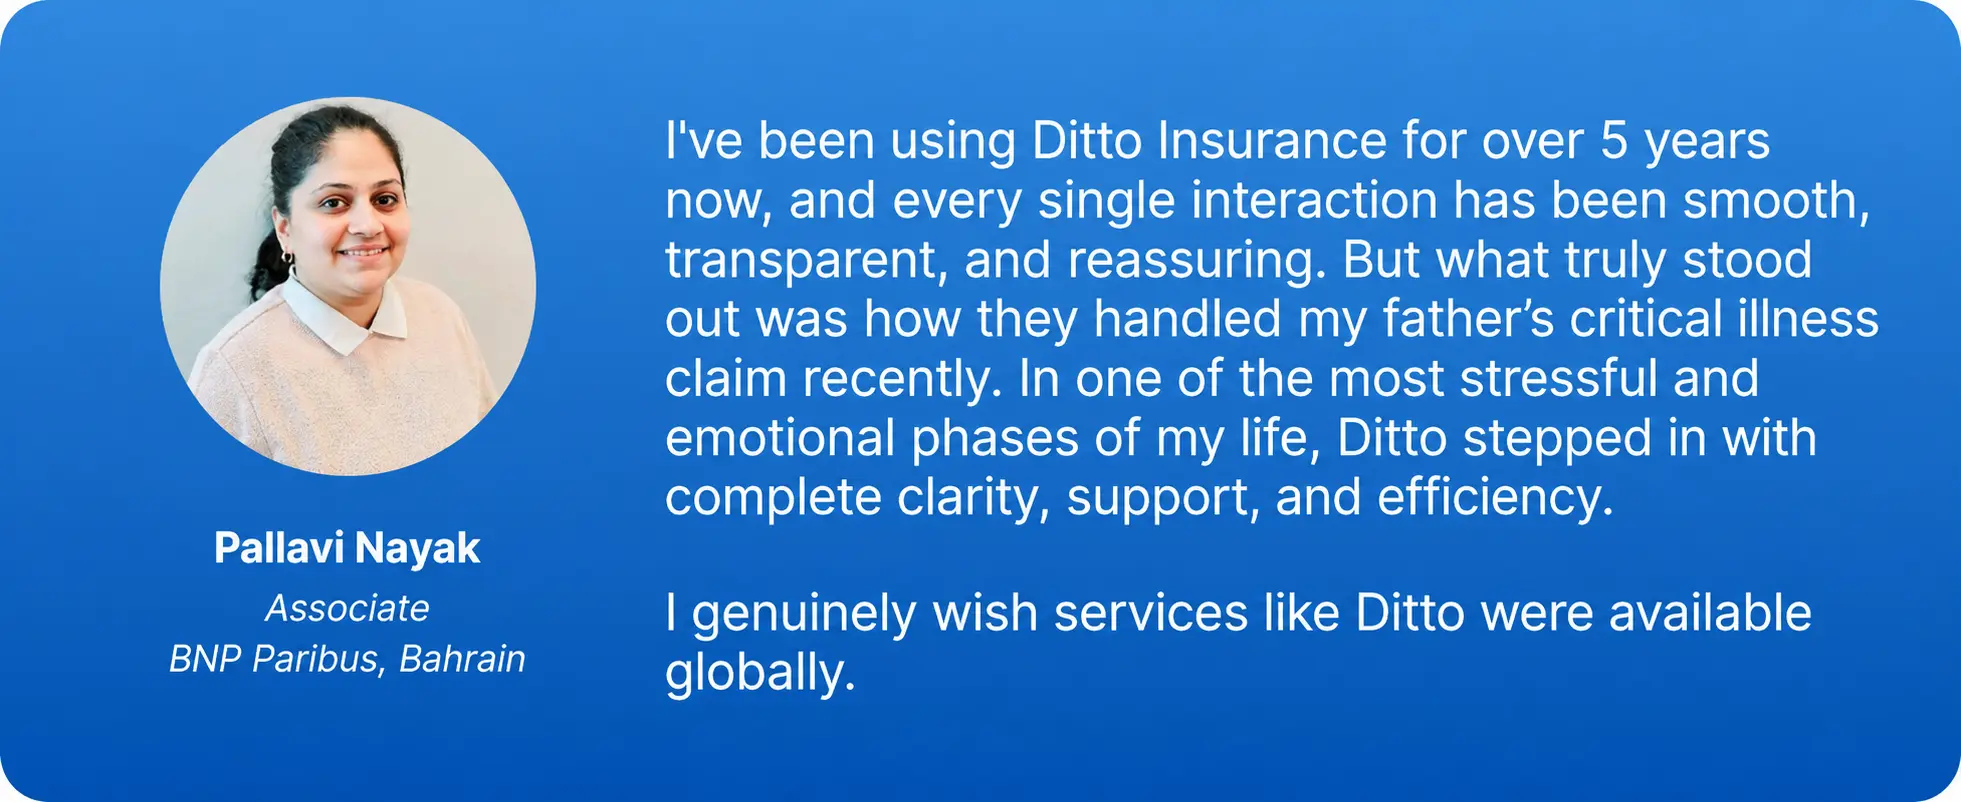
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Pallavi love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
Understanding the different types of health insurance plans helps you choose coverage that fits your needs and budget. For most people, a comprehensive policy is a good starting point, with additional coverage where necessary.
However, choosing the right type is only part of the decision. Waiting periods, exclusions, and coverage limits can affect how much you can actually claim.
Your Next Step: Decide your base SI first, then compare two or three plans on room-rent limits, waiting periods, and co-payments. To compare the top options side by side, read our guide to the best health insurance plans in India.
Frequently Asked Questions
Last updated on: